


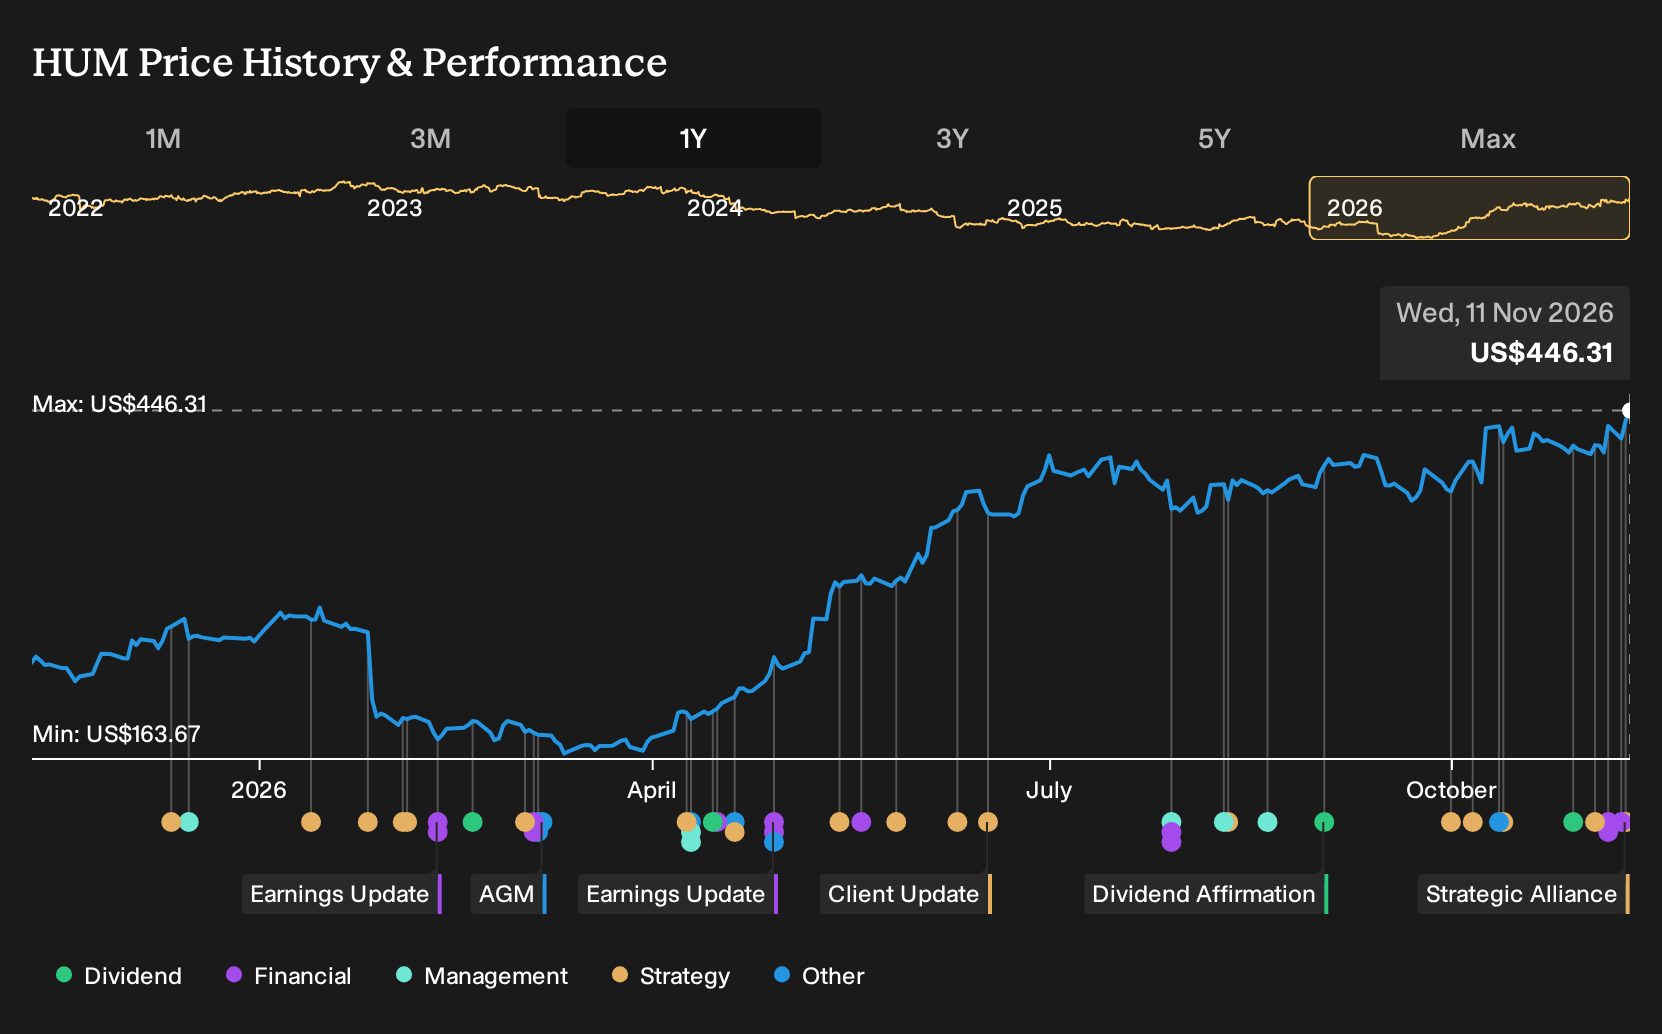
- Humana recently reported third quarter 2026 results with revenue of US$41,155 million and net income of US$162 million, alongside updated full year GAAP EPS guidance of at least US$15.09 and a declared quarterly dividend of US$0.885 per share.
- The company’s improved Medicare Advantage Star Ratings and wider use of streamlined, tech enabled prior authorization and oncology care models point to a heavier focus on quality metrics, care coordination and cost discipline within Humana’s core insurance and services engine.
- The next area of attention will be how Humana’s investment narrative is influenced by stronger Medicare Advantage Stars performance and quality driven contracts.
Scan how Humana’s quality focused oncology and prior authorization moves compare with other healthcare insurers by reviewing the hand picked 37 healthcare AI stocks now shaping tech enabled care delivery.
Humana Investment Narrative Recap
Owning Humana means buying into the analyst consensus Narrative on Simply Wall St that the Medicare Advantage margin restoration plan, value based care focus and CenterWell build out can support higher earnings over time. The short term swing factor is whether Humana can keep medical cost trends in check while exiting roughly 600,000 lower return plans without a sharp hit to membership or revenue.
The biggest risk sits on the regulatory side. Ongoing scrutiny of Medicare Advantage coding and any reset to Stars rules or diagnosis assessments could affect reimbursement and quality bonuses. The recent oncology and prior authorization moves look directionally helpful for quality metrics, although the near term financial impact from these programs alone is unlikely to be material.
The new cancer care model with Evolent Health and American Oncology Network looks closely tied to those catalysts. It leans into clinical pathways, quality programs and data driven treatment planning, which all connect back to Humana’s push on clinical excellence, medical margin discipline and better Stars performance across Medicare Advantage.
Automated reminders, performance scorecards and reduced traditional prior authorization for evidence based regimens also reflect a focus on operational efficiency rather than pure cost cutting. If this approach scales beyond the initial eight state rollout and aligns cleanly with CMS rules, it could support the multiyear margin restoration plan while helping mitigate some regulatory and compliance risks flagged in the current Medicare narrative.
Humana’s current analyst storyline points to revenues of US$191.9b and earnings of US$4.3b by 2029. This outlook is built on an assumed 7.6% yearly rise in revenue and an earnings increase of about US$3.1b from US$1.2b today.
Uncover why Humana's fair value indicates a 7% potential upside to its current price that could narrow quickly if sentiment shifts.
Exploring Other Perspectives
One alternate view on Humana leans heavily on Stars and clinical programs as a catalyst. The most optimistic analysts were already modeling about US$205.5b of revenue and US$6.2b of earnings by 2029, before this oncology model and prior authorization expansion. You can read that as a much more upbeat quality story that may now evolve further.
Explore 5 other Humana fair value estimates, including one that suggests as much as 117% potential upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Humana research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Humana. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Humana's overall financial health at a glance.
Looking for more investment ideas beyond Humana?
After you have formed a view on Humana, it can help to widen the lens and compare it with other potential opportunities using the Simply Wall St Screener.
- If you want potential value combined with quality fundamentals, start by scanning a 32 high quality undervalued stocks that pass strict balance sheet and cash flow checks.
- For investors who care about resilience first and upside second, filter for a 30 resilient stocks with low risk scores and see which businesses score well on stability metrics.
- If you prefer stocks that may be flying under the radar, check out a 20 high quality undiscovered gems that pair solid financials with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com