


- Planet Labs PBC released first light imagery from Pelican-12, its Gen 2 high-resolution satellite and first 30 cm class capable spacecraft, and also reported new collaboration, launch, and financial update milestones in early November 2026.
- Pelican-12’s edge-compute hardware and low latency communications testbed, combined with FarmQA’s AI agronomy tools, point to Planet Labs pushing harder into analytics and decision-support rather than just raw imagery supply.
- We will now explore how Planet Labs’ investment narrative could be reshaped by Pelican-12’s edge compute capability feeding higher value analytics.
Scan beyond Planet Labs PBC and line up other Earth observation and AI infrastructure plays with the hand picked 53 AI infrastructure stocks that is already filtered for you.
Planet Labs PBC Investment Narrative Recap
To own Planet Labs PBC, you need to believe its daily Earth archive can shift from selling pixels to selling answers, which is exactly where Pelican 12 and the FarmQA work are pointed. The near term catalyst is execution on higher value analytics and Satellite Services, supported by a growing constellation and new manufacturing capacity in Berlin.
The biggest near term risk is still execution against profitability targets while funding capital intensive hardware and AI investments. According to John_Eric, an investor in the Simply Wall St Community, the stock already reflects high expectations, and the business remains unprofitable with recent shareholder dilution adding pressure on management to show operating leverage.
The FarmQA collaboration ties most directly to the Pelican 12 edge compute story. Planet Labs brings near daily imagery over millions of acres. FarmQA contributes structured agronomy data and sugar beet yield models. Together, the tools aim to give agriculture customers decisions rather than just maps, which speaks directly to the higher value analytics thesis John_Eric describes.
If the sugar beet pilots prove useful across regions and more crops, this type of deployment could matter for future contracts and retention, because it shifts Planet Labs into customers’ core workflows rather than sitting at the data supplier layer that John_Eric worries could become a commodity. The operational hurdle is clear. Planet needs to ship reliable, field tested products at scale while still managing losses and capital intensity.
On John_Eric’s framework, the fair value of $31.00 reflects a scenario where Planet Labs compounds revenue at 115.8% a year and eventually reaches a 7.5% profit margin. Together, these figures describe the kind of scaled platform he thinks could justify materially higher cash generation over time.
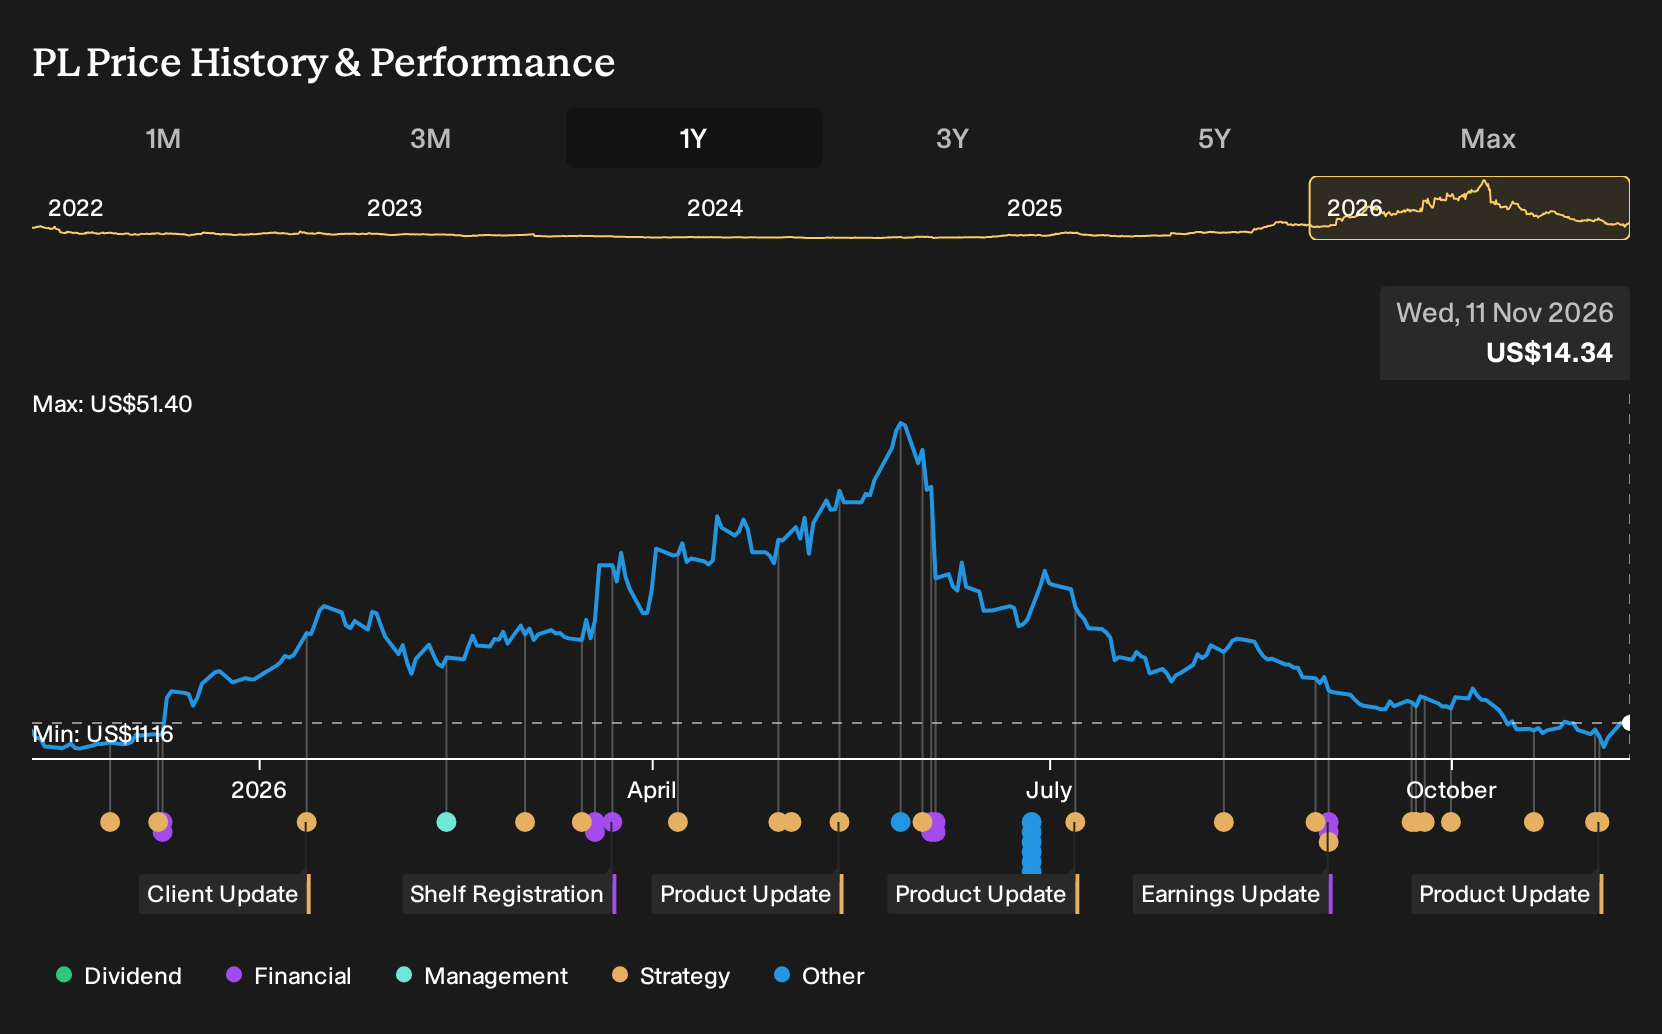
Uncover why Planet Labs PBC's fair value indicates a 116% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
For Planet Labs PBC, the lowest analysts focus on contract risk rather than Pelican 12’s tech upside. They worry that civil government demand and data access rules could leave identified pipeline underused, even while modelling roughly 28.8% annual revenue growth to about US$807.9 million and earnings near US$54.6 million by 2029. That more cautious story has not yet absorbed this week’s Pelican and FarmQA news. It is therefore worth comparing several viewpoints before you decide how persuasive that bearish case feels.
Explore 10 other Planet Labs PBC fair value estimates, including one that suggests as much as 59% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Planet Labs PBC research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Planet Labs PBC. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Planet Labs PBC's overall financial health at a glance.
Looking For More Investment Ideas Beyond Planet Labs PBC?
Once you have a view on Planet Labs PBC, it can help to compare that thesis with other opportunities that match your risk tolerance and income needs. The Simply Wall St Screener lets you filter the market quickly so you can focus on a shortlist that actually fits your plan rather than a long list of tickers.
- If capital preservation sits higher on your priority list than big swings, scan through a group of companies that screen for lower risk profiles using the 30 resilient stocks with low risk scores.
- If value is your starting point, line up candidates that combine strong fundamentals with what our models flag as potentially attractive pricing by reviewing the 32 high quality undervalued stocks.
- If income matters more than price moves, narrow in on stocks that pair higher yields with a focus on durability through the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com