


Columbia Sportswear (COLM) just posted third quarter results with higher sales, net income, and earnings per share, raised its full year outlook, issued fresh fourth quarter guidance, and reaffirmed its regular quarterly dividend.
Columbia Sportswear shares have picked up momentum in recent months, with a 30 day share price return of 26.5% and a 90 day gain of 25.7%. The 1 year total shareholder return of 35.4% contrasts with flat performance over three years and a 25.6% decline over five years, which suggests that investors may be reassessing the risk and earnings profile in light of the latest guidance and dividend commitment.
Scan how Columbia Sportswear’s rebound compares with a hand picked 32 high quality undervalued stocks that also pair recent momentum with earnings support and balance sheet strength.
After a sharp move that leaves Columbia Sportswear only a touch below the average analyst target and at a deeper discount to some intrinsic value estimates, the real question is where fair value actually sits in that spread.
Most Popular Narrative: 1% Undervalued
On the analyst consensus Narrative on Simply Wall St, Columbia Sportswear carries a fair value estimate of $73 against a last close of $72.19. This places the stock almost exactly in line with that modeled outcome while still assuming an 8.91% discount rate on future cash flows.
Footwear, women's and PFG are set up as faster growing product platforms, with Fall 2026 and Spring 2027 wholesale order books calling out double digit growth in women's and footwear and stronger adoption of newer styles. This can gradually shift the product mix toward higher velocity and support revenue and gross margin.
See why 2 investors see Columbia Sportswear as 1% undervalued.
Result: Fair Value of $73 (ABOUT RIGHT)
Still, the narrative can crack if U.S. demand weakens further, or if higher tariffs and freight costs continue to squeeze Columbia Sportswear’s underlying profitability.
Find out about the key risks to this Columbia Sportswear narrative.
Another View: What Multiples Say About Columbia Sportswear
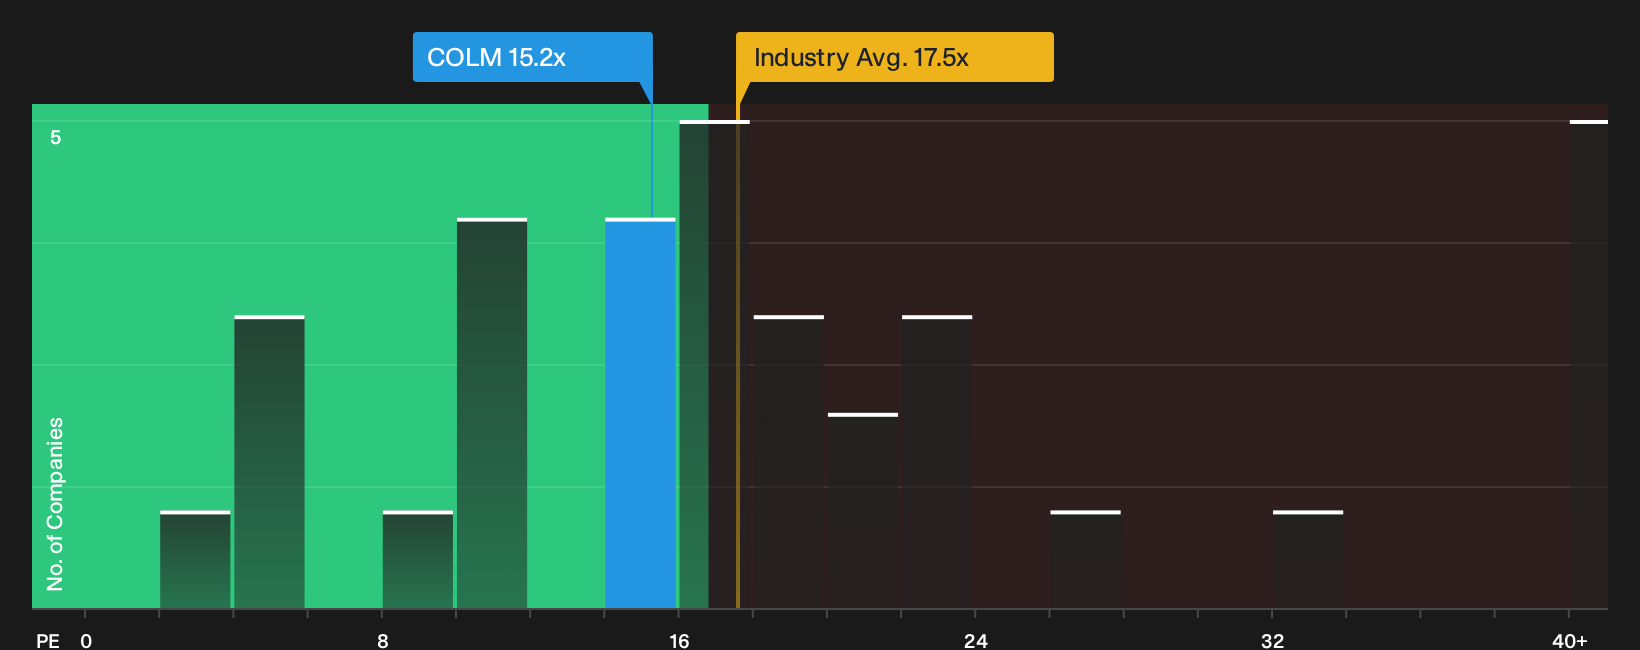
On price multiples, Columbia Sportswear tells a different story to the near at fair value analyst target. The shares trade on a P/E of 15.2x, below the US Luxury group on 17.7x but above a fair ratio of 12.5x. This suggests some valuation risk if sentiment cools.
To see how that gap might close in either direction, it helps to look at the detailed valuation breakdown and where the fair ratio comes from, not just the headline multiple. See what the numbers say about this price — find out in our valuation breakdown.
Here is how Columbia Sportswear’s current earnings multiple compares with peers and that fair ratio on one view.
Next Steps
Mixed messages in the data can cut both ways, so if you think Columbia Sportswear is at an inflection point, move fast and stress test the numbers yourself using the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Columbia Sportswear?
If Columbia Sportswear has sharpened your radar, do not stop here. The real edge comes from lining it up against other clear, data driven opportunities.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (23 results) that keeps financial strength front and center when you compare your next picks.
- Hunt for pricing gaps with a focused 32 high quality undervalued stocks that highlights companies where fundamentals and current valuations do not quite match.
- Lock in income focused ideas through a curated 6 dividend fortresses designed for investors who care about both yield and staying power.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com