


Semiconductor machinery manufacturer Applied Materials (NASDAQ:AMAT) reported calendar Q3 2026 [fiscal Q4 2026] results exceeding the market’s revenue expectations, with revenue up 53.1% year on year to $10.41 billion. Guidance for next quarter’s revenue was $11.1 billion at the midpoint, 2.1% above analysts’ consensus estimates. Its non-GAAP profit of $4.16 per share was 2.6% above analysts’ consensus estimates.
For more on Applied Materials, read our free full research report.
Applied Materials Q3 CY2026 highlights:
- Revenue $10.41 billion vs S&P analysts' consensus estimates of $10.33 billion (53.1% year-on-year growth, 0.8% beat)
- Adjusted EPS $4.16 vs S&P analysts' consensus estimates of $4.05 (2.6% beat)
- Adjusted operating income $3.68 billion vs analysts' consensus estimates of $3.61 billion (35.3% margin, 1.7% beat)
- Revenue guidance $11.1 billion at the midpoint for Q4 CY2026, above analysts' consensus estimates of $10.87 billion
- Adjusted EPS guidance $4.35 at the midpoint for Q4 CY2026, above analysts' consensus estimates of $4.23
- Operating margin 35.1%, up from 25.2% in the same quarter last year
- Free cash flow margin 25.1%, down from 30% in the same quarter last year
- Inventory days outstanding 122, down from 132 in the previous quarter
- Market capitalization $313.5 billion
“Applied Materials delivered record results in fiscal 2026, and we are on track to grow our Semiconductor Systems business more than 40 percent in our calendar 2026,” said Gary Dickerson, President and CEO. “AI continues to fuel strong incremental demand for semiconductors and Applied has built the most-enabling portfolio to advance the AI-computing roadmap, putting us in a great position for multi-year revenue and profit growth.”
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Even a weak business can perform well for one or two quarters, but a top-tier one grows for years. Applied Materials’s revenue grew at a solid 8.4% compounded annual growth rate over the last five years. Its growth was slightly above the average semiconductor company and shows its offerings resonate with customers. Semiconductors are a cyclical industry, and long-term investors should be prepared for periods of high growth followed by periods of revenue contractions.
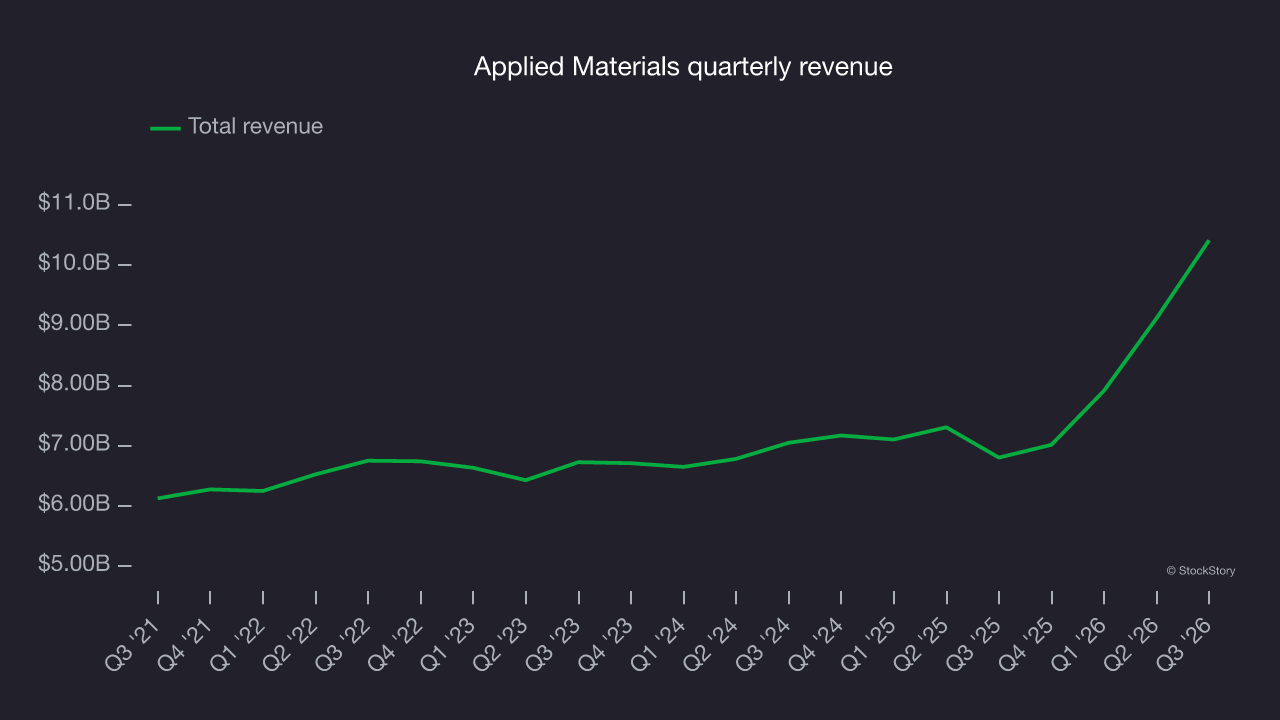
Long-term growth is the most important, but short-term results matter for semiconductors because the rapid pace of technological innovation (Moore’s Law) could make yesterday’s hit product obsolete today. Applied Materials’s annualized revenue growth of 12.6% over the last two years is above its five-year trend, which is encouraging.
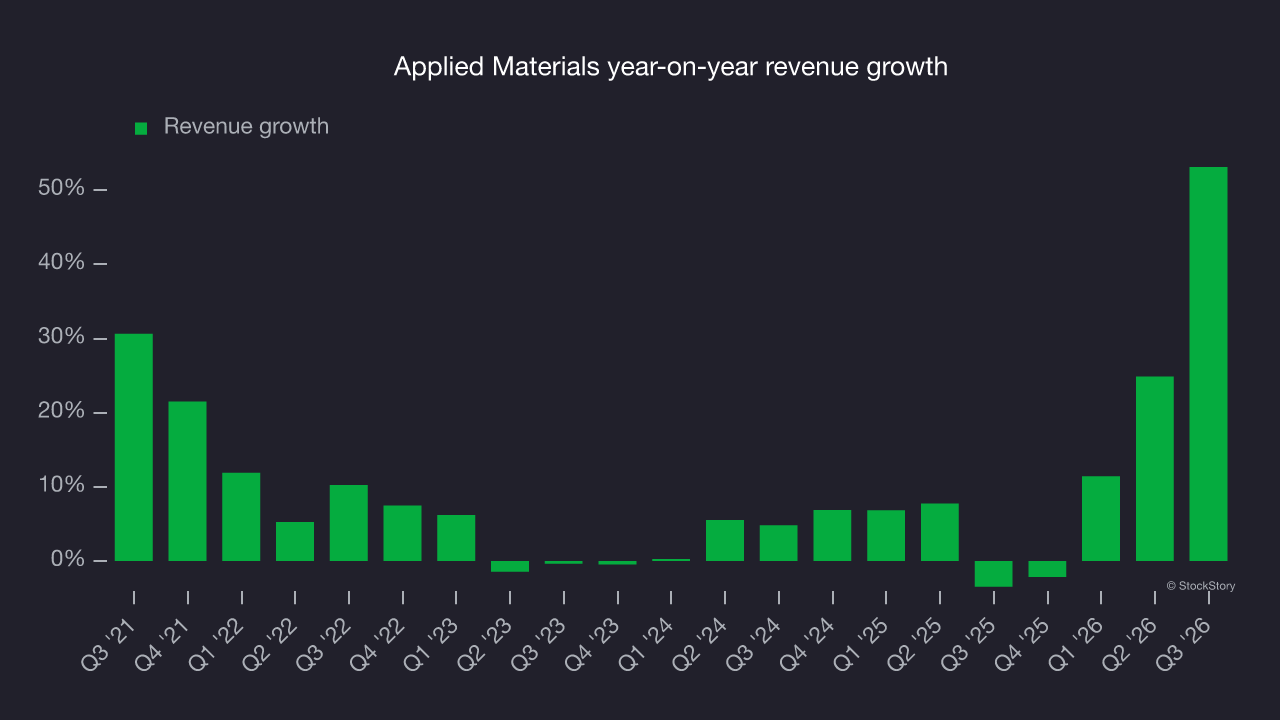
This quarter, Applied Materials reported strong year-on-year revenue growth of 53.1%, and its $10.41 billion of revenue beat Wall Street’s consensus estimates by 0.8%. Beyond the beat, the company appears to be in the early stages of an upcycle, as this was the third consecutive quarter of growth. A typical upcycle tends to last 8-10 quarters. Management is currently guiding for a 58.3% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 36.9% over the next 12 months, according to S&P, an improvement versus the last two years. This projection is above the sector average and suggests its newer products and services will fuel better top-line performance.
Product demand & outstanding inventory
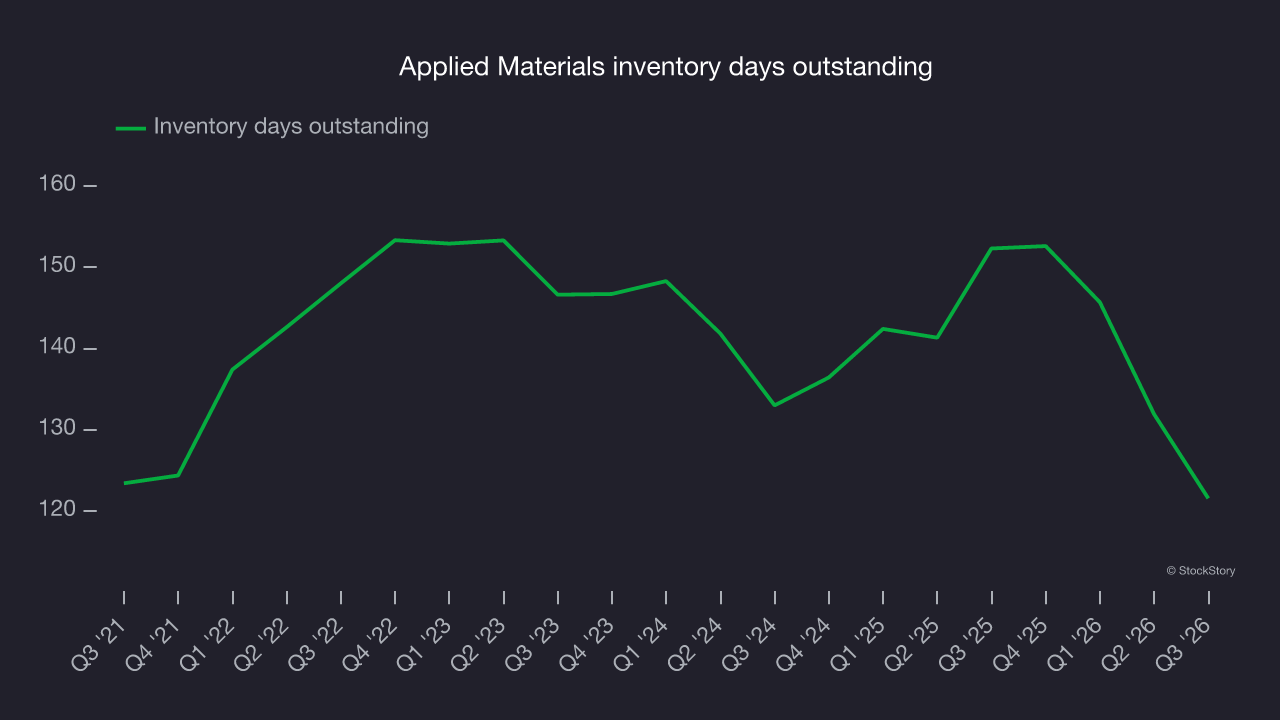
Days inventory outstanding, or DIO, is an important metric for chipmakers, as it reflects a business’s capital intensity and the cyclical nature of semiconductor supply and demand. In a tight supply environment, inventories tend to be stable, allowing chipmakers to exert pricing power. Steadily increasing DIO can be a warning sign that demand is weak, and if inventories continue to rise, the company may have to downsize production.
This quarter, Applied Materials’s DIO came in at 122, which is 21 days below its five-year average. These figures show no indication of an excessive inventory buildup.
Key takeaways from Applied Materials’s Q3 results
A strong improvement in inventory levels and EPS above Wall Street’s consensus estimates were key positives in Applied Materials’s quarter. Shares remained flat at $383.64 immediately after the results.
Applied Materials may have had a good quarter, but that alone does not make it an investment opportunity. An investment decision should consider valuation and business quality as well as the latest earnings. Read our full research report here (it’s free).