


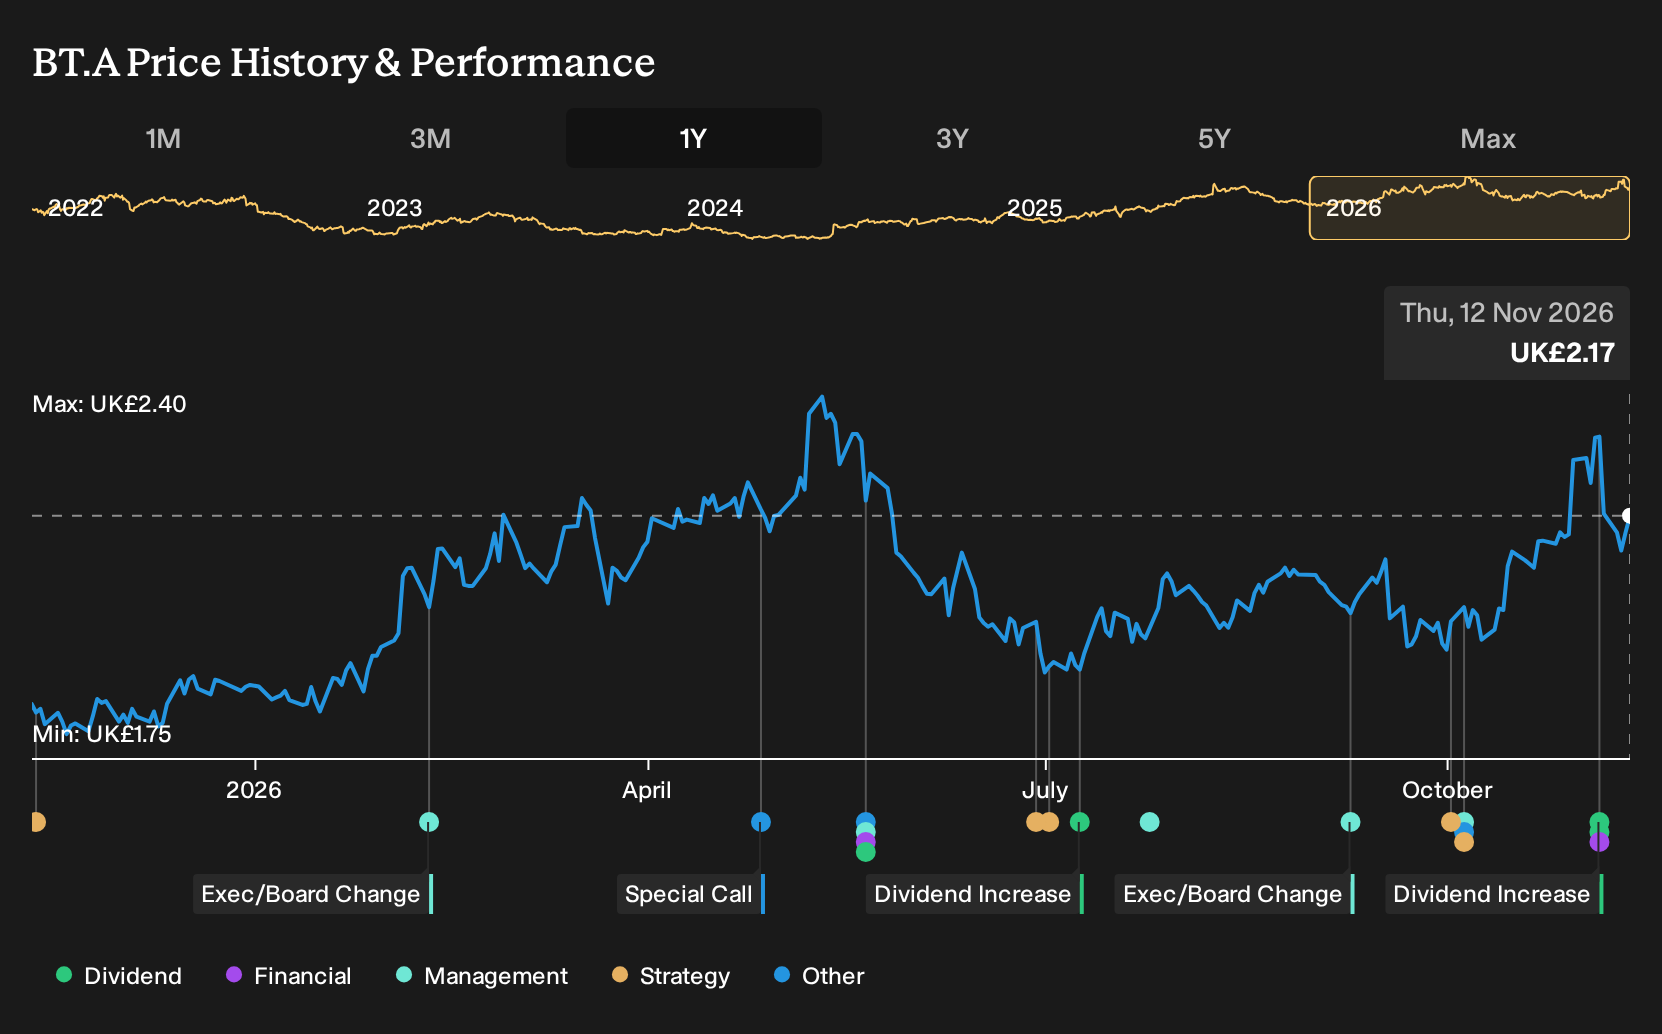
- BT Group reported half year 2026 results with sales of £8,753m and net income of £809m, and the Board approved an interim dividend of 2.50 pence per share to be paid in February 2027 while guiding for low to mid single digit dividend growth for fiscal 2027.
- The Board’s policy to keep the interim dividend at 30% of the prior full year payout gives income focused investors a clearer, rules based framework for how BT Group intends to share future cash flow.
- We will examine how BT Group's investment narrative is influenced by rising earnings and the Board's guidance for dividend growth.
BT Group Investment Narrative Recap
To own BT Group, an investor needs to believe that the heavy lifting on fibre, 5G and cost cutting can translate into steadier earnings and cash generation while legacy voice and international revenues come under pressure. The latest half year figures, with £8,753m of sales and £809m of net income, point to a business that is at least holding its ground while this shift plays out.
The most important short term catalyst remains execution on the extended cost and simplification program described in the analyst consensus Narrative on Simply Wall St, alongside continued fibre migration in the Consumer and Openreach arms. The biggest risk sits in Business and international operations, where weaker demand and contract delays could offset progress elsewhere. The new dividend guidance does not materially change these operational priorities.
The dividend framework update is the announcement that matters most here. The Board has approved an interim dividend of 2.50 pence per share for the half year, with a stated policy that the interim will be 30% of the prior full year payout and that dividends are expected to grow at a low to mid single digit rate in fiscal 2027. For income focused holders, that is a clear signalling tool for how future cash might be shared.
This payout structure connects directly to the catalysts highlighted in the analyst consensus Narrative on Simply Wall St, which link higher normalized free cash flow to potential dividend growth. Execution now needs to support that objective. That means BT Group delivering on fibre build and migration targets, managing pension and debt obligations, and limiting further revenue pressure from legacy voice and the Business segment so the dividend policy remains supported by actual cash generation rather than financial stretch.
BT Group's narrative projects £18.4b revenue and £1.6b earnings by 2029. This implies revenue is expected to decline by 2.2% per year and earnings to rise by about £0.5b from £1.1b today.
Uncover why BT Group's fair value indicates a 4% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
You can see a sharper contrast if you focus on the bearish narrative around BT Group’s earnings power. The lowest analysts were pencilling in revenue of about £16.8b and earnings near £899.2m by 2029, which is far below consensus. That cohort assumes dividend guidance proves too optimistic, so explore both views before relying on the new policy.
Explore 4 other BT Group fair value estimates, including one that suggests as much as 34% downside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your BT Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for BT Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BT Group's overall financial health at a glance.
Looking for more BT Group investment ideas?
If BT Group has you thinking about income, value, or resilience, it can help to line it up against a wider field of opportunities using a structured stock filter.
- For investors who want income paired with staying power, focus on companies that resemble dividend workhorses and review a curated set of 5 dividend fortresses.
- If capital preservation and steadier return profiles matter most, consider starting with a universe of companies screened as 5 resilient stocks with low risk scores.
- For those hunting for quality that flies under the radar, widen the search to a group of 5 high quality undiscovered gems that combine fundamentals with lower crowding.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com