


Mirum Pharmaceuticals has delivered a sharp multi year share price run, and the question now is whether the current valuation can be supported by its sales base. With the stock closing at US$94.61, investors are starting to ask how much of Mirum's rare liver disease pipeline story is already reflected in the price versus what its present revenue footprint can justify.
- Over the past 5 years the stock has generated a very large return of about 7x, which puts extra focus on whether the business's existing sales can carry that kind of re rating.
- Recent positive Phase 3 data for brelovitug in chronic hepatitis delta virus and Mirum's plan to seek approval may support expectations for higher future product sales, which feeds directly into how investors think about today's price to sales relationship.
- The analysts covering Mirum Pharmaceuticals have run their own numbers. See what analysts think Mirum Pharmaceuticals's shares could be worth.
The issue now is whether Mirum's current share price can be explained by its sales when set against the Fair Ratio benchmark.
If you want more ideas with a similar rare disease focus, a targeted stocks list is a useful second starting point for research, especially a screen of 37 healthcare AI stocks.
Where Does Mirum Pharmaceuticals Sit on Sales?
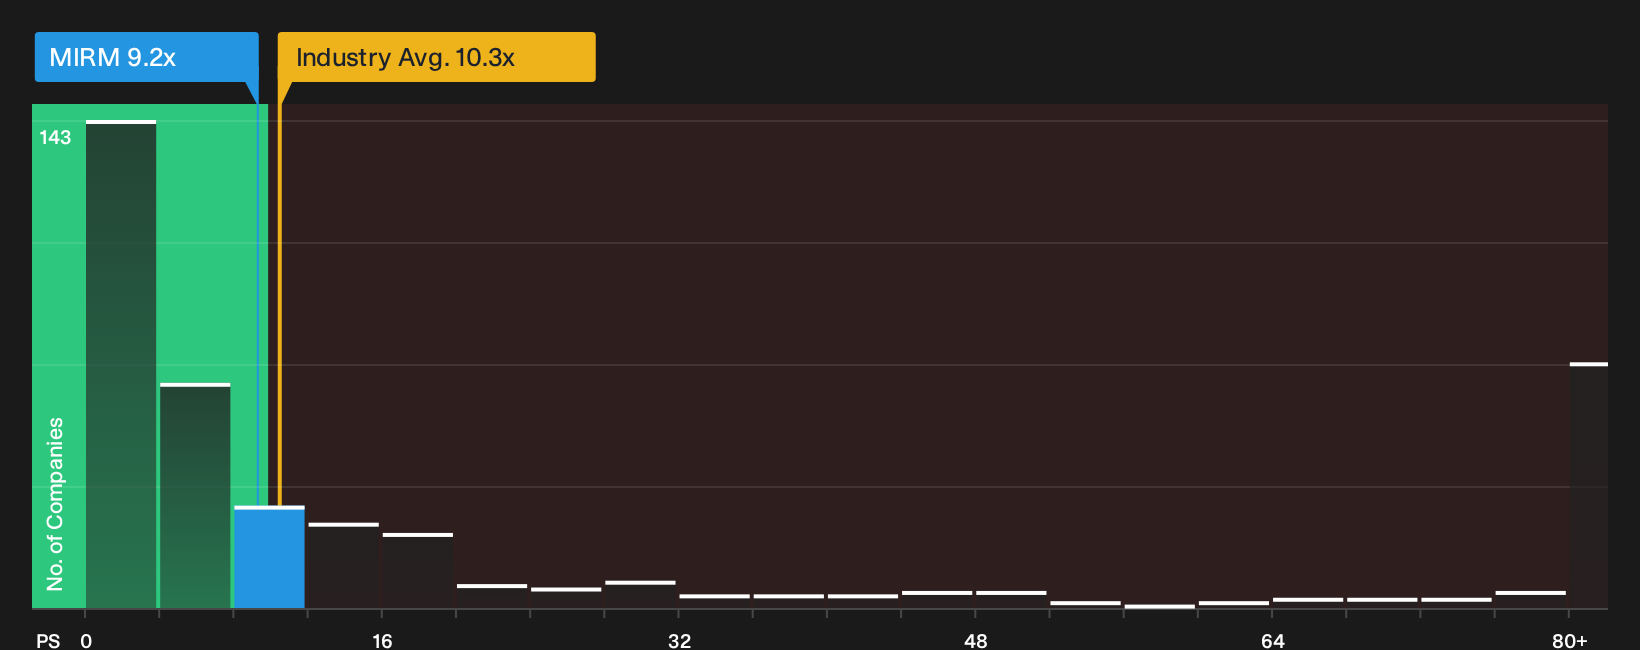
The P/S ratio suits Mirum Pharmaceuticals because investors are still focusing on revenue potential rather than current earnings. On this metric, the stock trades on a P/S of 9.2x, which is below the broader biotech industry average of 10.3x and also below the 12.5x peer group average. This indicates that the market is not assigning a premium sales multiple despite the rare disease focus.
The Fair Ratio, which blends Mirum Pharmaceuticals' sector, scale, growth profile and risk into a single benchmark, points to a level slightly above where the current P/S sits. Because brelovitug's Phase 3 success in chronic hepatitis delta virus has already put future sales potential firmly on the radar, the gap between the live P/S and this tailored benchmark suggests investors are pricing Mirum with expectations that are broadly aligned with what the model implies for its revenue base. Explore the numbers behind Mirum Pharmaceuticals's P/S valuation.
The Mirum Pharmaceuticals Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Mirum Pharmaceuticals valuation question leaves off by spelling out which assumptions for growth, profitability and earnings would need to hold for the stock to trade meaningfully above or below today's level. Each scenario ties a fair worth estimate to a particular view of Mirum Pharmaceuticals' possible catalysts and risks, so you can track over time which storyline seems closest to what is actually unfolding.
One of the top narratives on Mirum Pharmaceuticals: 38% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The main requirement for this strategy is successful execution on label expansions and new launches, particularly LIVMARLI in additional cholestatic indications, and Brelovitug and Atebrioz reaching under-served hepatitis delta and FOP patients at meaningful scale..."
Discover why this Narrative puts Mirum Pharmaceuticals at 38% undervalued.
One more Mirum Pharmaceuticals check that sits beside the price tag
Before you stop at the P/S and narrative work, it is worth asking who is actually steering Mirum Pharmaceuticals and how their pay packets line up with your priorities as a shareholder. See who runs Mirum Pharmaceuticals and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com