


- Orica reported full year 2026 results for the period ended 30 September, with sales of A$8,263.5 million and net income of A$264.2 million, alongside higher basic earnings per share from continuing operations of A$0.568.
- The widening gap between sales and net profit compared with the prior year highlights changes in Orica’s cost base and mix of earnings, with earnings per share increasing at a faster rate than revenue.
- We will now look at how Orica's stronger net income and earnings per share trend relates to the broader investment narrative.
Scan how Orica's profit rebound compares with peers by reviewing a hand picked list of solid balance sheet and fundamentals (12 results) that may handle earnings swings with more resilience.
Orica Investment Narrative Recap
To stay invested in Orica, you need to be comfortable with a mining services group that leans heavily on execution in explosives, specialty chemicals and digital monitoring, rather than broad top line expansion. The analyst consensus Narrative on Simply Wall St emphasizes earnings quality improving over time. The latest full year result, with A$8,263.5 million in sales and A$264.2 million in net income, feeds directly into that earnings story.
In the near term, the key swing factor remains how effectively Orica can keep lifting profitability while managing fully utilized sodium cyanide assets, thermal coal volume pressure and the integration of Nelson Brothers, Terra Insights and Cyanco. The biggest risk is still operational. Any slip in debottlenecking or integration could dull the impact of this earnings step up.
The most relevant update is the full year 2026 earnings release itself. Sales reached A$8,263.5 million compared with A$8,144.5 million a year earlier, while net income was A$264.2 million compared with A$162.3 million. Basic earnings per share from continuing operations were A$0.568 compared with A$0.335, with diluted earnings per share at A$0.563 compared with A$0.332.
This profit profile intersects directly with the catalysts outlined in the analyst consensus Narrative on Simply Wall St, including recurring digital revenue, cost reduction plans and specialty mining chemicals expansion. Stronger earnings give management more room to pursue debottlenecking, absorb acquisition integration risk and fund decarbonisation and digital projects, though the high level of debt and P/E premium still require close attention to execution.
Orica's current earnings are A$250.7 million, with analysts forecasting revenue of A$8.7 billion and earnings of A$727.2 million by 2029. This outlook is based on 2.3% yearly revenue growth and an earnings increase of about A$476.5 million from today to the 2029 consensus estimate.
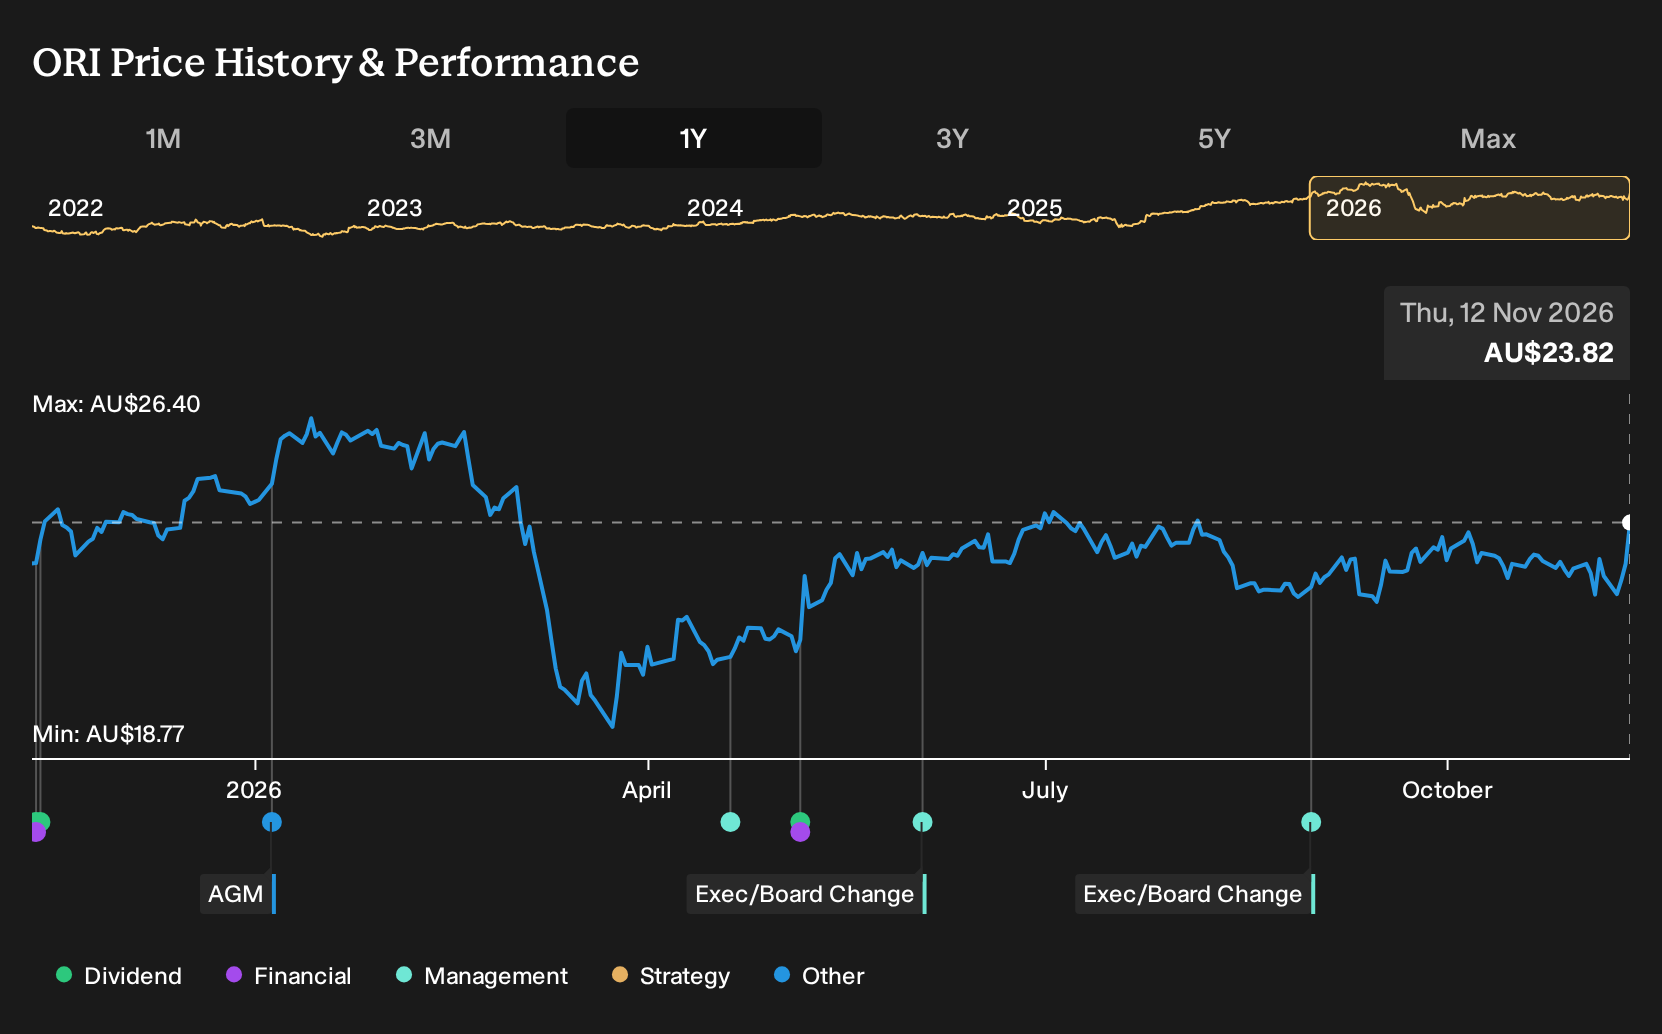
Uncover why Orica's fair value indicates a 9% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Only two fair value estimates from the Simply Wall St Community currently span a wide band, from about A$25.91 to A$38.81 per share, which shows how far opinions on Orica can stretch. Those views pre date the latest earnings release, so you may want to weigh them against risks around debottlenecking and acquisition integration before forming your own stance.
Explore another Orica fair value estimate, including one that suggests there could be as much as 63% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Orica research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Orica. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Orica's overall financial health at a glance.
Looking For More Ideas Beyond Orica?
Once you have formed a view on Orica, it can help to widen the lens and compare it with other businesses that share similar qualities, or offer something completely different, using the Simply Wall St Screener.
- If you prefer companies that already combine balance sheet strength with solid fundamentals, take a look at a curated list of solid balance sheet and fundamentals (12 results) that could help you narrow the field quickly.
- For investors hunting for potential mispricing, review a 3 high quality undervalued stocks that filters for quality metrics alongside attractive valuations.
- If you are searching for stable income streams, consider a 6 dividend fortresses that focuses on higher yielding payouts with an emphasis on resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com