


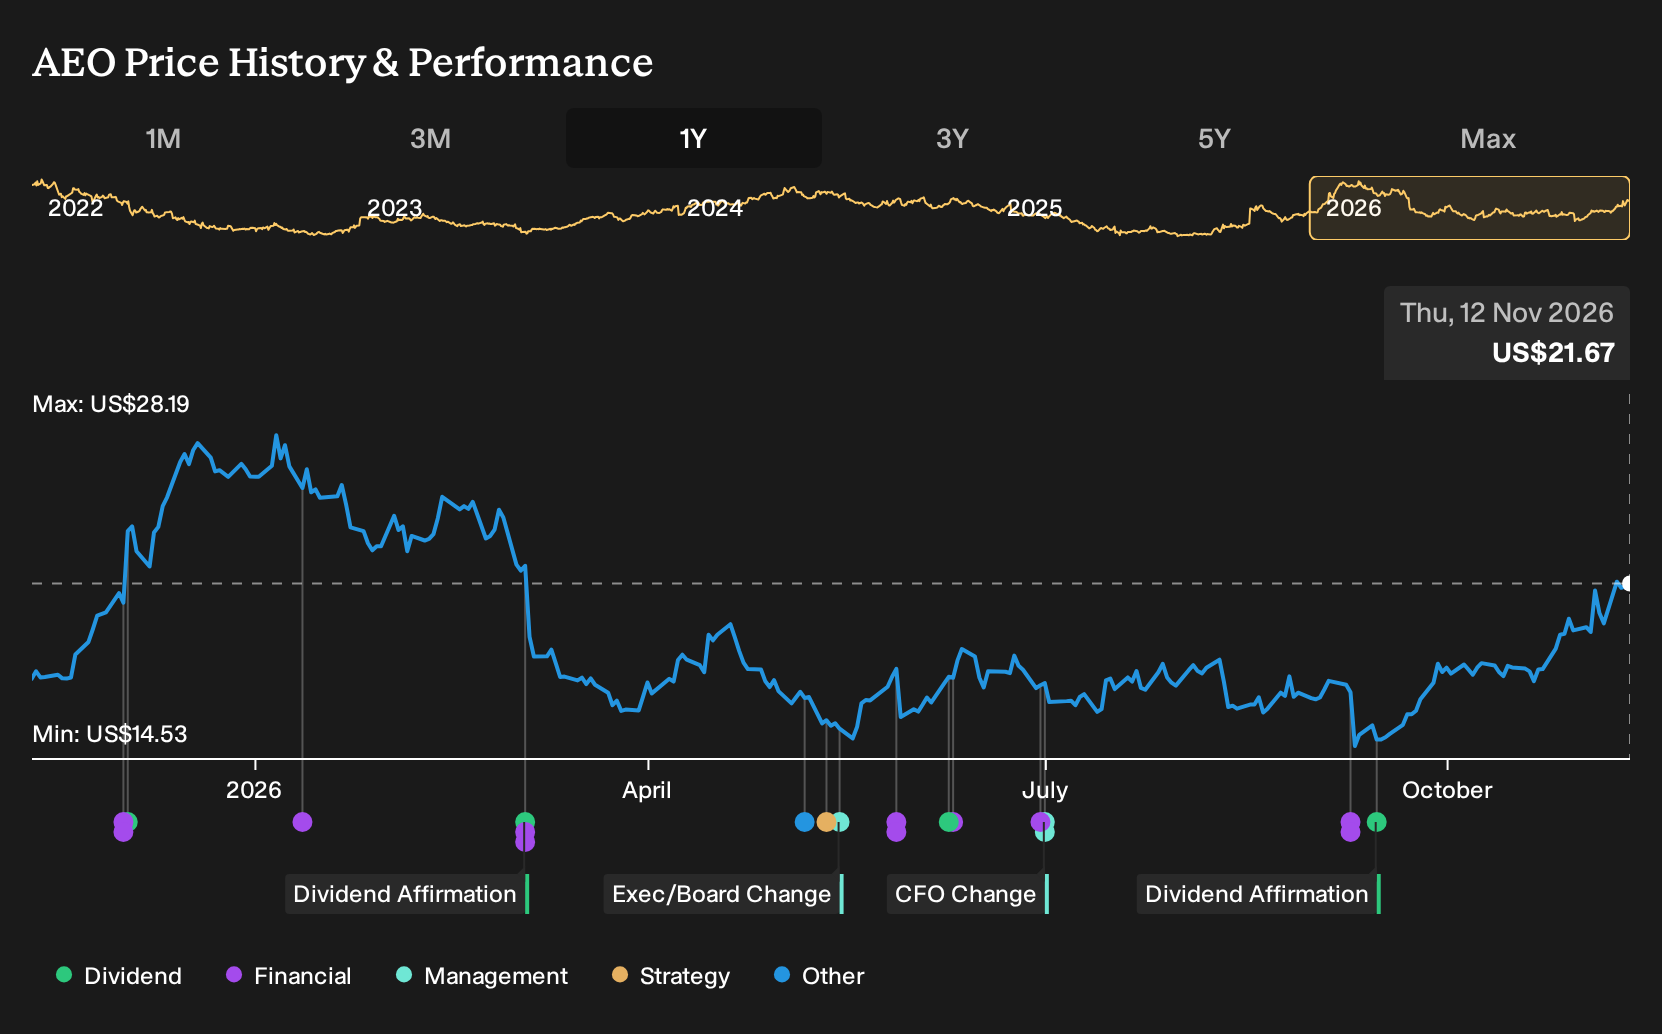
If one product captured how American Eagle Outfitters changed the conversation this year, it was Aerie’s intimates and activewear lines, which pushed that brand past US$2b in trailing revenue while the flagship label worked through softer women’s bottoms. Investors who held American Eagle Outfitters over the past year are up 24.2%, including dividends. If you were deciding whether to buy on 11 November 2025, what did you need to believe about Aerie’s surge and the weaker core brand?
If the move has made American Eagle Outfitters harder to judge, start where the gap is still open and scan 32 high quality undervalued stocks.
The Two Stories Investors Had To Choose Between On American Eagle Outfitters
The shares cost US$17.48 at the start of the period, and American Eagle Outfitters sat between two very different but reasonable stories about where Aerie, OFFLINE, and the core stores could head next.
The bullish view saw a Fair Value of US$19, a price implied by expectations, built on Aerie, digital channels, and sustainability helping revenue grow 4.1% a year and profit margins rising toward 6.3%.
The more cautious narrative put Fair Value at US$15.94, again an implied level, and focused on consumer uncertainty, tariffs, and softer sales that might require heavier markdowns and keep pressure on earnings and the P/E multiple.
What The Evidence Around American Eagle Outfitters Actually Tested
Aerie and OFFLINE kept surging for American Eagle Outfitters, with Aerie’s comparable sales jumping 19% and trailing revenue above US$2b while core American Eagle comps slipped 1% and women’s bottoms stayed weak. Group revenue and net income both rose between Q2 2026 and Q2 2027, and net margin widened from 6.0% to 9.7%, so the period cut both ways.
The hinge assumption was whether Aerie’s strength could support the whole group while the flagship label struggled. For any retailer with a breakout sub-brand, track segment sales, comparable trends, and margin by banner, and test the claim that one fast grower can offset a softer main line.
What American Eagle Outfitters' Run Now Prices In
American Eagle Outfitters trades at US$21.55 after a 24.2% gain over the past year. The bearish analyst narrative on Simply Wall St sees fair value below that level and frames the gap around whether brand mix, marketing spend, and tariff refunds can keep supporting earnings.
To pay today’s price, you would need to believe Aerie and OFFLINE stay strong while the American Eagle women’s reset, inventory clean up, and marketing shift all land without cutting into margins.
"Management is repositioning American Eagle women’s denim and bottoms. However, the early 2026 experience of underperforming women’s bottoms and seasonal categories that required elevated markdowns suggests the reset could take longer and require more discounting than expected, which would weigh on merchandise margin and net income."
The price and this Narrative do not agree. → Uncover what this Narrative says American Eagle Outfitters is actually worth
Find Your Own Contrarian Opportunity
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 34% below our estimate - ties expanding AI workloads to a shared cloud and subscription infrastructure base.
- Company 2 - 38% below our estimate - tackles complex technical failures and regulatory questions for multidisciplinary client projects.
- Company 3 - 44% below our estimate - targets large AI data centre builds that depend on its GPU and software ecosystem.
Those are three of them. See every one of the 23 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com