


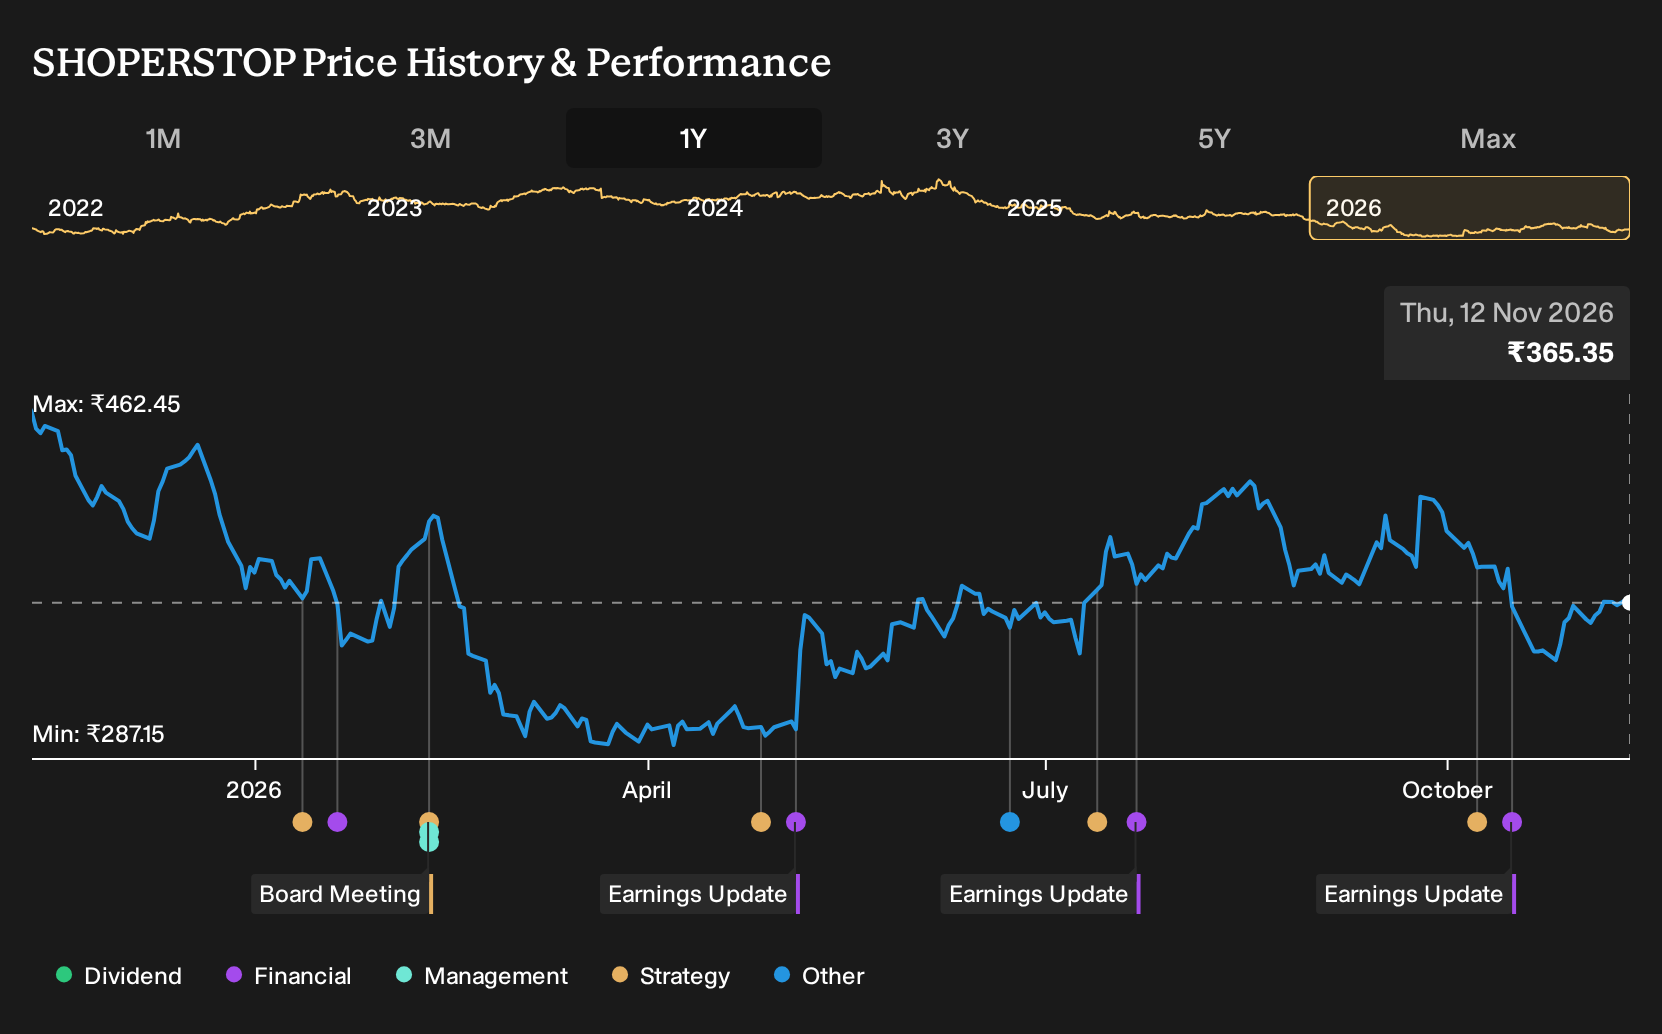
Shoppers Stop just reported that quarterly revenue reached ₹13,662.7m and net income turned to a ₹31.1m profit, a shift from a loss in the same quarter a year earlier. Investors who held Shoppers Stop over the past year are down 20.3%, including dividends. If you had put money in a year ago on either a bullish or bearish analyst case, this mix of better margins but weaker share performance may prompt you to reconsider how you assess the company and its risks.
Shoppers Stop has already moved. See which of 194 high quality undervalued stocks still trade below our estimates.
The Two Shoppers Stop Stories Investors Were Weighing
At that point the shares cost ₹461, so anyone looking at Shoppers Stop had to decide which story felt closer to reality and which risks mattered more.
The bullish narrative pointed to a fair value of ₹807, a price that would only make sense if premiumization, private brands, and city expansion supported higher margins and stronger digital sales over time.
The bearish view argued for a fair value of ₹327, built on the risk that online rivals, discounting, and Intune store costs could keep pressure on operating profitability.
What The Results Changed For The Shoppers Stop Debate
The clearest fact is that Shoppers Stop moved from a ₹201.1m loss in Q2 2026 to a ₹31.1m profit in Q2 2027, with net margin shifting from a -1.6% result to 0.2%. That tilt into the black supports the bullish focus on profitability; however, the slim margin and still modest earnings keep plenty of fuel for the cautious case.
The useful takeaway is simple. When a thesis rests on better profitability, do not just track revenue. Watch whether net margin and absolute profit both move in the direction the story promised.
What Shoppers Stop’s Lower Price Asks You To Believe
Shoppers Stop now trades at ₹365, with the analyst consensus Narrative on Simply Wall St suggesting a Fair Value that sits above this level. That view leans on premium stores, beauty formats and digital channels doing more of the heavy lifting than the share price currently credits.
For that higher figure to hold, a buyer today would need confidence that beauty and omni channel operations genuinely shift the earnings mix and cash generation, rather than just adding complexity and capital needs.
"The current valuation implies the share price does not fully reflect the contribution from growing beauty distribution, a higher premium mix and loss reduction in newer formats if these trends persist."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Looking Beyond Shoppers Stop
Shoppers Stop keeps you focused on physical stores, premium labels and in-store experience. That is only one side of modern retail.
Online, another giant is investing in warehouses, logistics technology and data systems. The aim is to make ordering feel instant and almost invisible.
Those investments shape cloud tools, media businesses and advertising built around shopping behavior.
When you consider Shoppers Stop and its omni channel plans, this parallel matters. The same customer expects speed, content and convenience working in one loop.
So a harder question emerges. How much retail strength sits inside the pipes, not just the storefronts?
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 68% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com