


ArcBest (ARCB) just reported third quarter results that showed higher sales of US$1,210.5 million and net income of US$51.66 million, a backdrop that helps explain recent investor focus on the stock.
ArcBest’s latest earnings release lands after a powerful run in the share price, with a year to date share price return of 76.12% and a 1 year total shareholder return of 108.85%. Momentum has cooled slightly, with the share price down 7.38% over the past 90 days and up 4.81% across the last month, as investors weigh strong recent results and dividend continuity against how much good news is already reflected in the current US$135.91 level.
Scan for other ArcBest style value opportunities that are benefiting from strong earnings revisions with our hand picked 32 high quality undervalued stocks.
ArcBest’s surge this year and the recent pullback both sit against the same backdrop of solid third quarter figures and upbeat analyst revisions. How much of that story already sits in the current valuation?
Most Popular Narrative: 20% Undervalued
On the analyst consensus Narrative on Simply Wall St, ArcBest screens as undervalued, with a fair value estimate of about $169.77 against the recent $135.91 close. The gap is anchored in how future earnings and margins are expected to develop under an 8.47% discount rate.
Ongoing network and cost-structure optimization, including terminal rationalization, brand consolidation and workforce reductions that are expected to reach about US$40 million in annualized savings by early 2027, positions ArcBest to convert incremental revenue into stronger net margins.
See why 4 investors see ArcBest as 20% undervalued.
Result: Fair Value of $169.77 (UNDERVALUED)
Still, the ArcBest story could change quickly if muted freight demand lingers or a heavier freight mix continues to pressure yield and hold back margin progress.
Find out about the key risks to this ArcBest narrative.
Another View: What ArcBest’s P/E Is Telling You
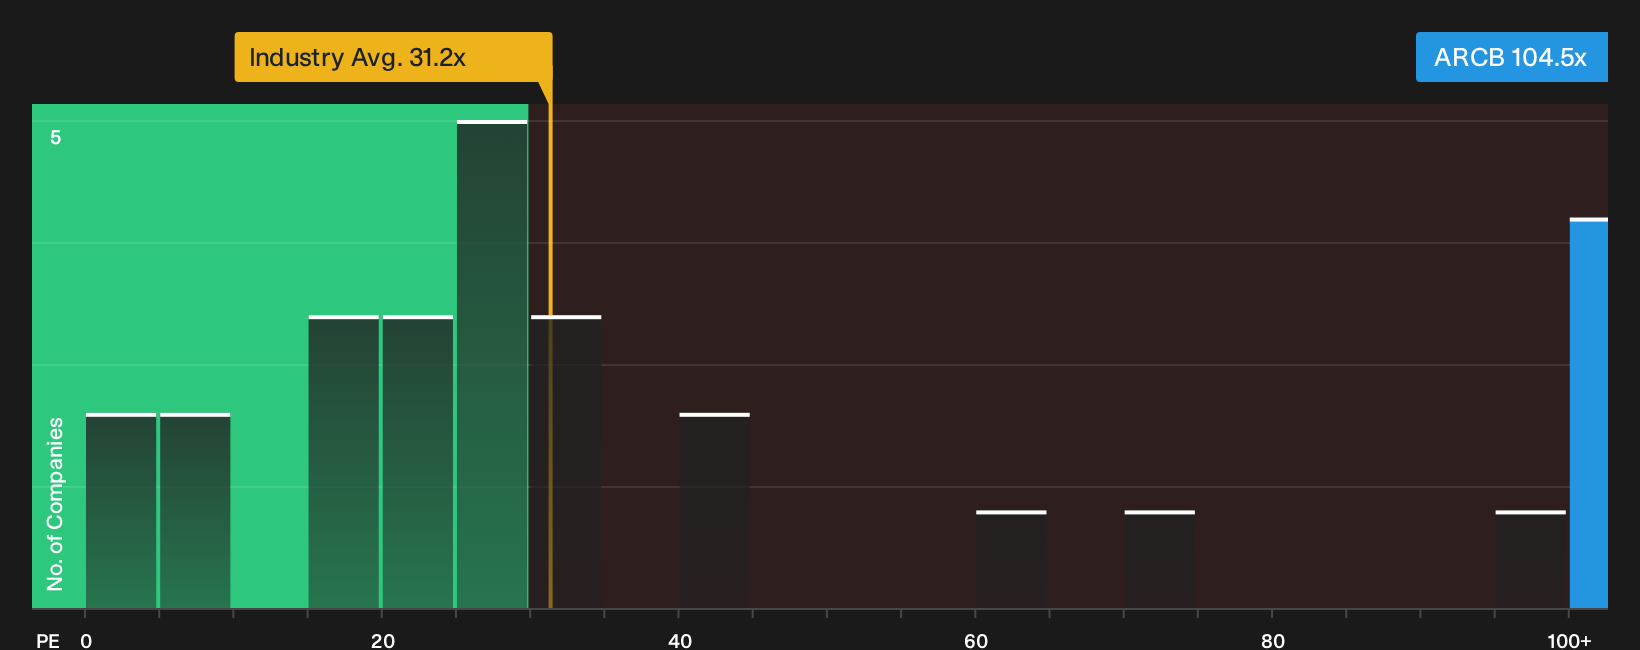
There is a very different message coming from ArcBest’s P/E ratio. The stock trades at about 104.5x earnings compared with 30.9x for the wider US Transportation group and 51.7x for closer peers, while the fair ratio is flagged at 53.2x. That gap points to valuation risk if sentiment cools or earnings stumble, so how much of a premium are you really comfortable with?
See what the numbers say about this price in the detailed valuation work, then weigh that against your own expectations for margins and growth potential: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals appear throughout this ArcBest story, so take this as your cue to examine the data yourself and decide quickly where you stand. To see both sides of the ledger in one place, review the 3 key rewards and 3 important warning signs
Looking for more ArcBest style investment ideas?
If you stop with ArcBest, you ignore other opportunities that fit your style. Use the Simply Wall St screener to quickly surface candidates that match your checklist.
- Target potential mispricing by scanning a curated pool of companies where quality and valuation meet using the 32 high quality undervalued stocks.
- Strengthen your downside protection by focusing on businesses with robust finances through the list of solid balance sheet and fundamentals (23 results).
- Hunt for future leaders that may be off most investors' radar by working through the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com