


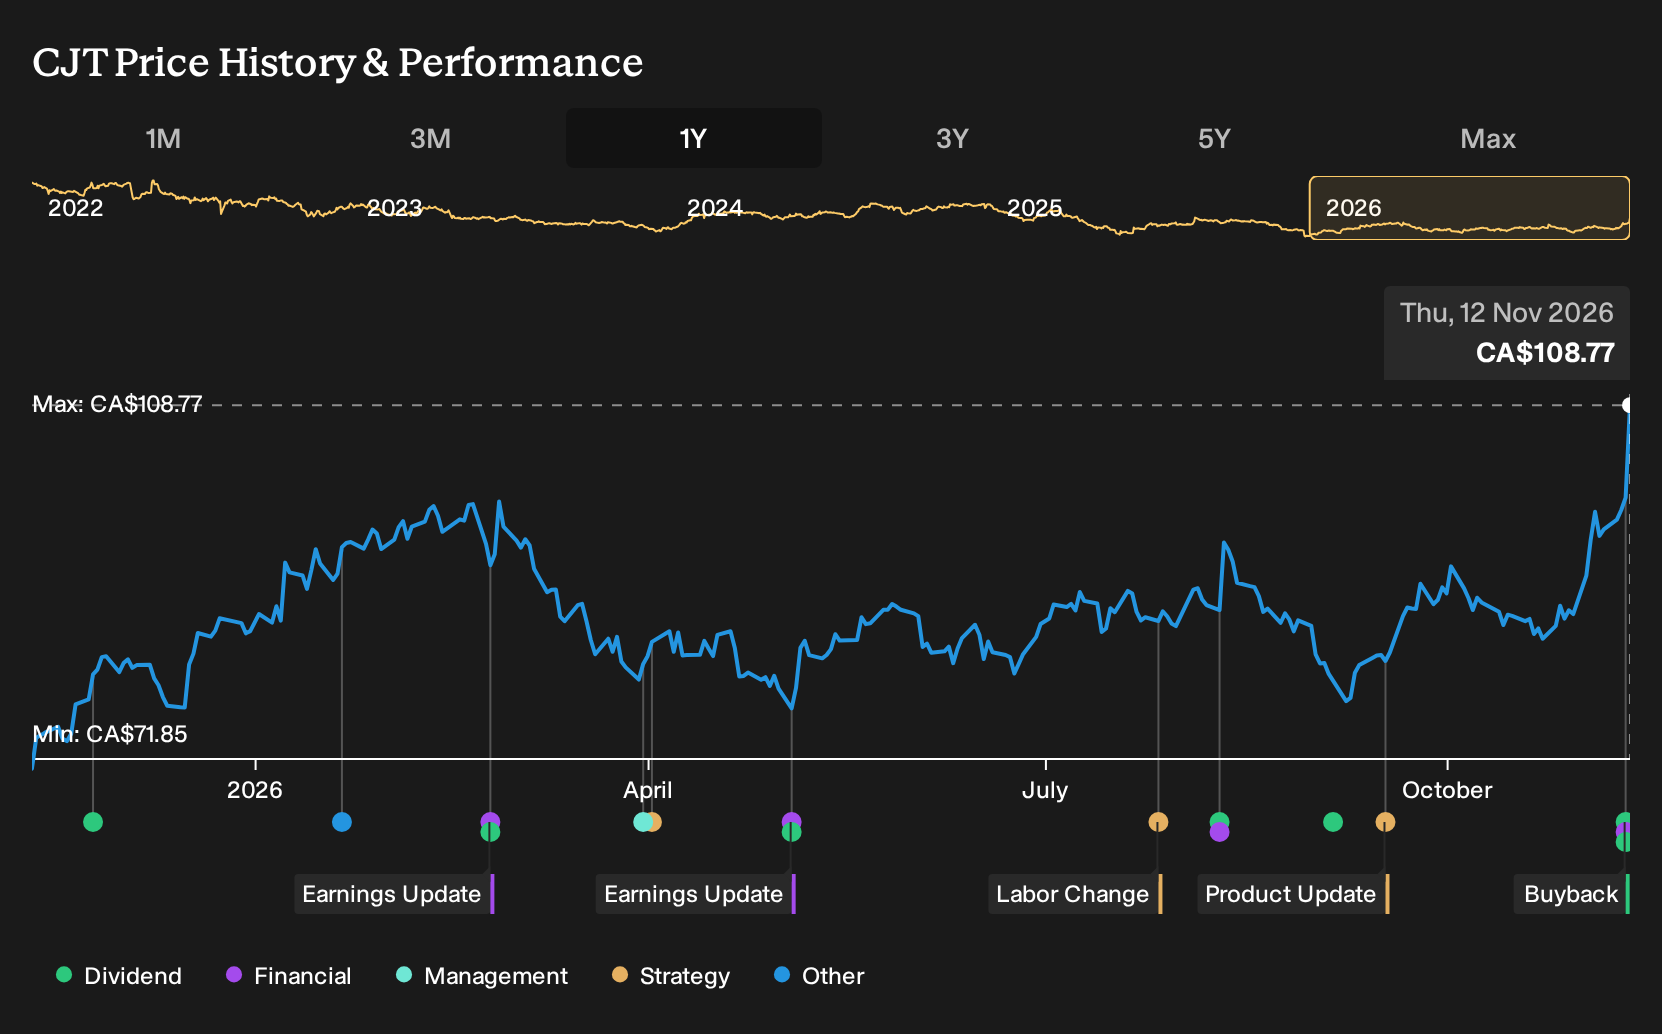
- Cargojet reported third quarter 2026 sales of C$286.5 million and net income of C$19.1 million, alongside an ongoing dividend and active share repurchases that reduced the share count over several tranches.
- The combination of record quarterly revenue with lower year-to-date earnings, higher pilot wage commitments and a renewed buyback program highlights how Cargojet is managing growth investment, labour costs and capital returns at the same time.
- The focus now turns to how Cargojet's record quarter and renewed buyback could influence its existing investment narrative for long-term holders.
Scan Cargojet's latest quarter against a curated 6 high quality undervalued stocks that also pairs revenue strength with disciplined balance sheets and active capital returns.
Cargojet Investment Narrative Recap
Cargojet shareholders need to believe that contracted e commerce volumes, the One Fleet model and international flying can keep aircraft busy enough to support higher labour costs and interest expense. The record Q3 revenue and higher quarterly profit help that story. The softer year to date earnings and lower margin trend flagged in the analyst consensus Narrative on Simply Wall St keep execution risk in focus.
Right now the key short term swing factor is how well Cargojet prices contracts and fills aircraft as peak season traffic runs through the network. The biggest risk is that major customers resist pricing or trim volumes while hybrid ACMI routes are still being reshaped, which could leave utilization and margins under pressure.
The renewed normal course issuer bid to purchase up to 1,400,000 shares, roughly 9.51% of the share base, is the clearest new signal tied to this update. Recent buyback tranches already retired 372,876 shares for C$28.88 million before the prior plan expired on November 10, 2026. The fresh authorization followed on November 11.
For you as a holder, that places more weight on Cargojet's ability to keep free cash flow coming through and interest costs manageable while margins have been trending lower and earnings have been uneven. If aircraft utilization, contract renewals with Amazon and DHL and pilot cost pass throughs all track well, the reduced share count can amplify per share outcomes. If not, leverage and weaker interest cover could matter more than the bid itself.
Cargojet's current analyst narrative points to revenue of CA$1.2b and earnings of CA$83.2 million by 2029. That profile is built on 4.9% yearly revenue growth and an earnings increase of about CA$36.7 million from CA$46.5 million today.
Uncover why Cargojet's fair value indicates a 12% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic Cargojet analysts were already leaning hard into the international charter angle, expecting revenue of about CA$1.3b and earnings near CA$94.1 million by 2029. That outlook treats higher margin flying as the big swing factor. With this record quarter and fresh buyback in hand, those narratives may shift again, in either direction. It makes sense for you to compare several viewpoints before deciding how you feel about the stock.
Explore 4 other Cargojet fair value estimates, including one that suggests potential upside of up to 29% from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Cargojet research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Cargojet. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cargojet's overall financial health at a glance.
Looking For More Ideas Beyond Cargojet?
Once you have a view on Cargojet, it can help to compare it with a wider watchlist built around the kinds of opportunities you care about most. The Simply Wall St Screener lets you filter by balance sheet strength, income focus or potential mispricing so you are not relying on a single story.
- If resilience is your priority, start with companies that pair defensive business models with lower perceived risk and see which ones make it into the 9 resilient stocks with low risk scores.
- If income matters more, scan for higher yielding payers that back their distributions with real cash flows using the 3 dividend fortresses.
- If you are hunting for potential bargains with solid fundamentals, widen your search to a curated 8 high quality undiscovered gems that may not yet be on every investor's radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com