


- CAE reported fiscal Q2 2027 results with CAD 1,204.7 million in sales and CAD 58.6 million in net income, reaffirmed full year revenue guidance for low single digit growth, raised its adjusted EPS and margin outlook, and advanced its plan to sell Flightscape for US$500 million.
- The potential shift from IFRS to U.S. GAAP, paired with cost focused transformation moves and a planned divestiture, puts CAE’s reporting, balance sheet and long term margin ambitions under a sharper spotlight for investors tracking execution.
- We will now look at how CAE’s raised adjusted earnings outlook could reshape the investment narrative that analysts outlined previously.
CAE Investment Narrative Recap
To own CAE, you need to believe the multi year transformation can convert a training and simulation portfolio into higher quality earnings while the balance sheet carries meaningful debt. The latest quarter showed softer sales and lower reported net income, yet stronger adjusted profitability and free cash flow. Reaffirmed low single digit revenue guidance and a higher adjusted EPS outlook suggest the operational plan for fiscal 2027 remains intact in the near term.
The key short term swing factor is execution on cost savings and transformation while civil training demand stays resilient despite pressure in that segment. The biggest risk remains funding this plan with leverage and one off items still affecting margins. Based on the analyst consensus Narrative on Simply Wall St, any stumble in free cash flow conversion or civil utilization would weigh heavily on that thesis, and the new results do not remove that risk.
The consent and proxy solicitation tied to a potential move from IFRS to U.S. GAAP is one of the most relevant recent announcements here. A change in reporting framework can alter how investors interpret adjusted metrics, leverage ratios and progress on margin targets, especially while CAE is investing US$200m to US$250m into its program.
For you as a shareholder, that shift adds another execution checkpoint on top of the Flightscape sale and the wider transformation. Clean, comparable disclosure will matter for tracking catalysts such as structural cost savings and defense margin trends, and it will also influence how easily lenders and bondholders assess risk at a time when the balance sheet already carries a high level of debt.
CAE's narrative projects CA$5.4b revenue and CA$523.0 million earnings by 2029. That outlook assumes 2.7% yearly revenue growth and an earnings increase of about CA$236 million from CA$286.9 million today.
Uncover why CAE's fair value indicates an 11% potential upside to its current price, which could narrow quickly.
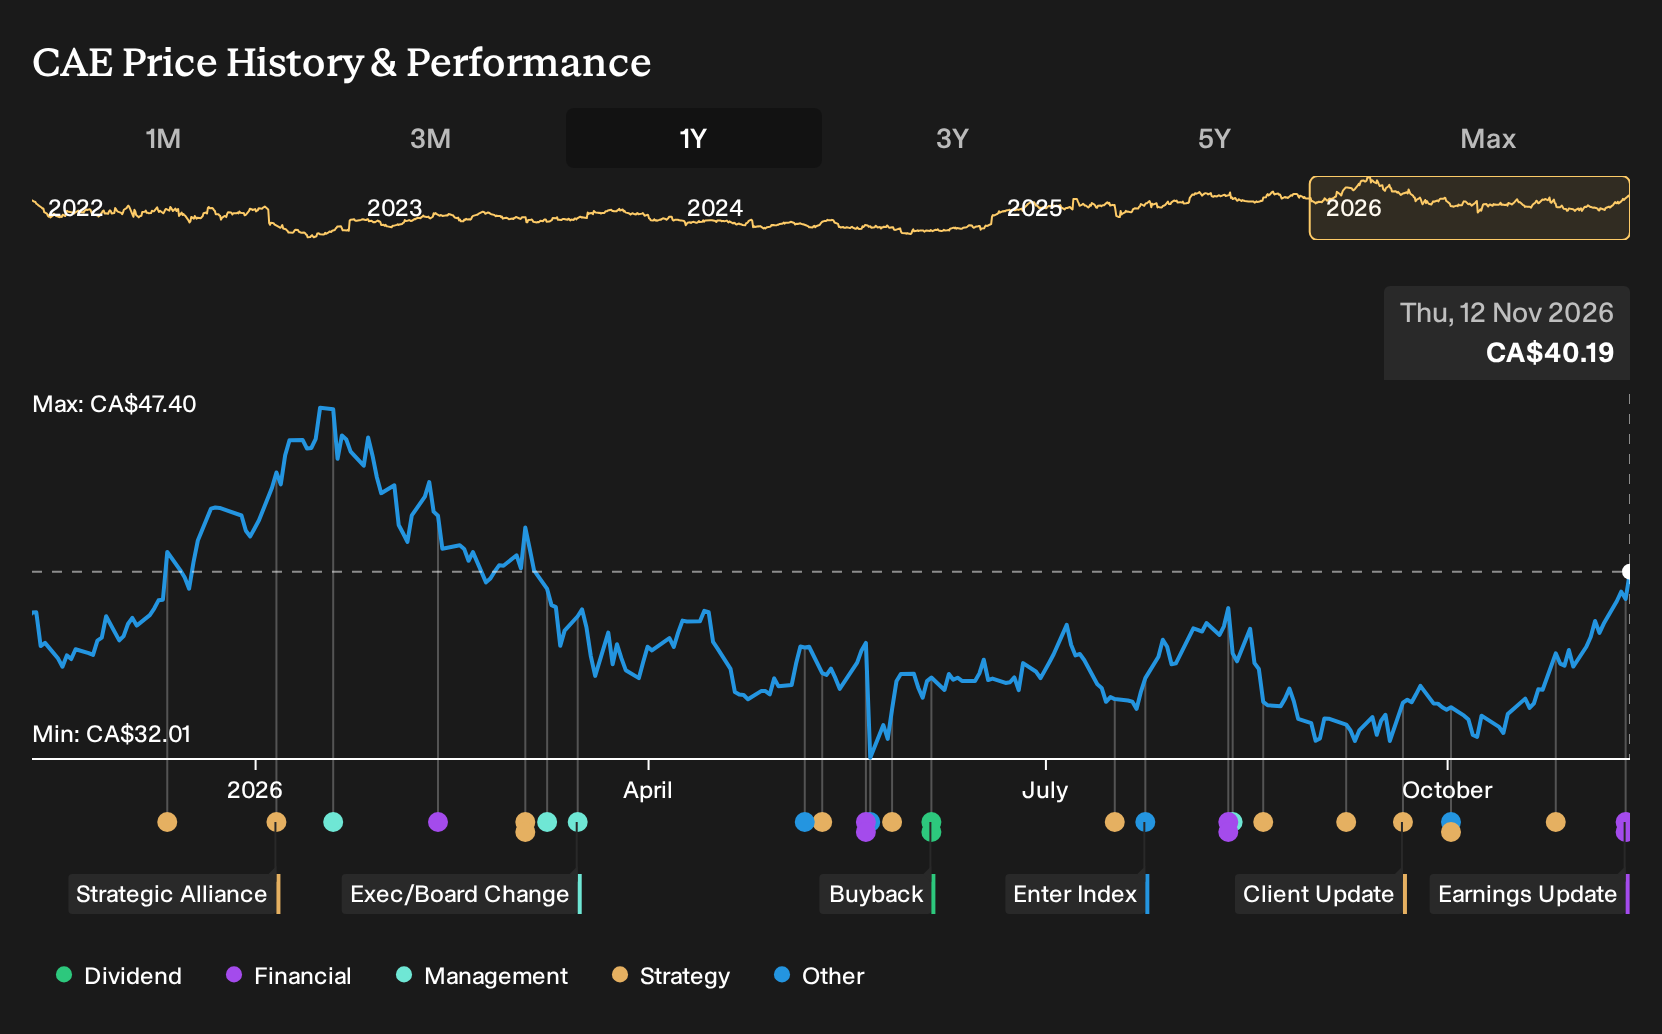
Exploring Other Perspectives
One alternate angle on CAE leans hard into the Flightscape divestiture as a potential accelerator. The most optimistic analysts were already pencilling in CA$5.8b of revenue and CA$572.2 million of earnings by 2029. You might see today’s guidance confirmation and accounting shift as reasons their more upbeat storyline could evolve further.
Explore 3 other CAE fair value estimates, including one that suggests as much as 34% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your CAE research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for CAE. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CAE's overall financial health at a glance.
Looking for more investment ideas beyond CAE?
Once you have a view on CAE, it helps to compare that thesis with other opportunities that share similar qualities or offer a very different risk profile. The Simply Wall St Screener can surface groups of shares that match the themes you care about most so you can pressure test your thinking across a wider watchlist.
- If capital preservation sits near the top of your priorities, filter for companies that score well on resilience and risk using our 9 resilient stocks with low risk scores as a starting universe.
- For investors who care most about financial strength, build a watchlist around businesses with robust balance sheets and solid fundamentals by scanning the list of solid balance sheet and fundamentals (5 results) and seeing what stands out.
- If you prefer stories that have not already attracted heavy attention, widen your search to under-followed opportunities with strong fundamentals by reviewing the 8 high quality undiscovered gems and seeing which ones merit a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com