


Harbour Energy (LSE:HBR) caught investor attention after lifting its 2026 free cash flow forecast to $2.6b, supported by higher oil prices, a 9% production increase in Q3, and the integration of Wintershall Dea assets.
The share price tells a mixed story. Harbour Energy’s stock has gained 11.3% over the past 90 days, and the year-to-date share price return of 37.17% points to building momentum, even though the 30-day share price return is down 6.17%.
Scan other energy producers with similar momentum and balance sheet support by checking the hand-picked 15 high quality undervalued stocks along with Harbour Energy’s latest move.
After a sharp rerating on the upgraded free cash flow outlook, Harbour Energy now sits at an interesting crossroads. Is the recent move already pricing in the heavy lifting, or does valuation still leave meaningful upside on the table?
Most Popular Narrative: 22% Undervalued
At a last close of £2.74 compared with a fair value estimate of £3.52, the analyst consensus Narrative on Simply Wall St frames Harbour Energy as trading at a meaningful discount while anchoring that view in detailed production and earnings forecasts built on an 8.48% discount rate.
The integration of the Wintershall Dea acquisition has significantly increased Harbour Energy's production scale and asset diversification, substantially reducing reliance on mature UK North Sea assets and enabling expanded exposure to resilient international demand, which supports future revenue growth and earnings resilience.
See why 46 investors see Harbour Energy as 22% undervalued.
Result: Fair Value of £3.52 (UNDERVALUED)
Still, the Harbour Energy story depends on UK fiscal pressure not worsening and on European gas prices remaining high enough to support the current earnings narrative.
Find out about the key risks to this Harbour Energy narrative.
Another View on Harbour Energy’s Valuation
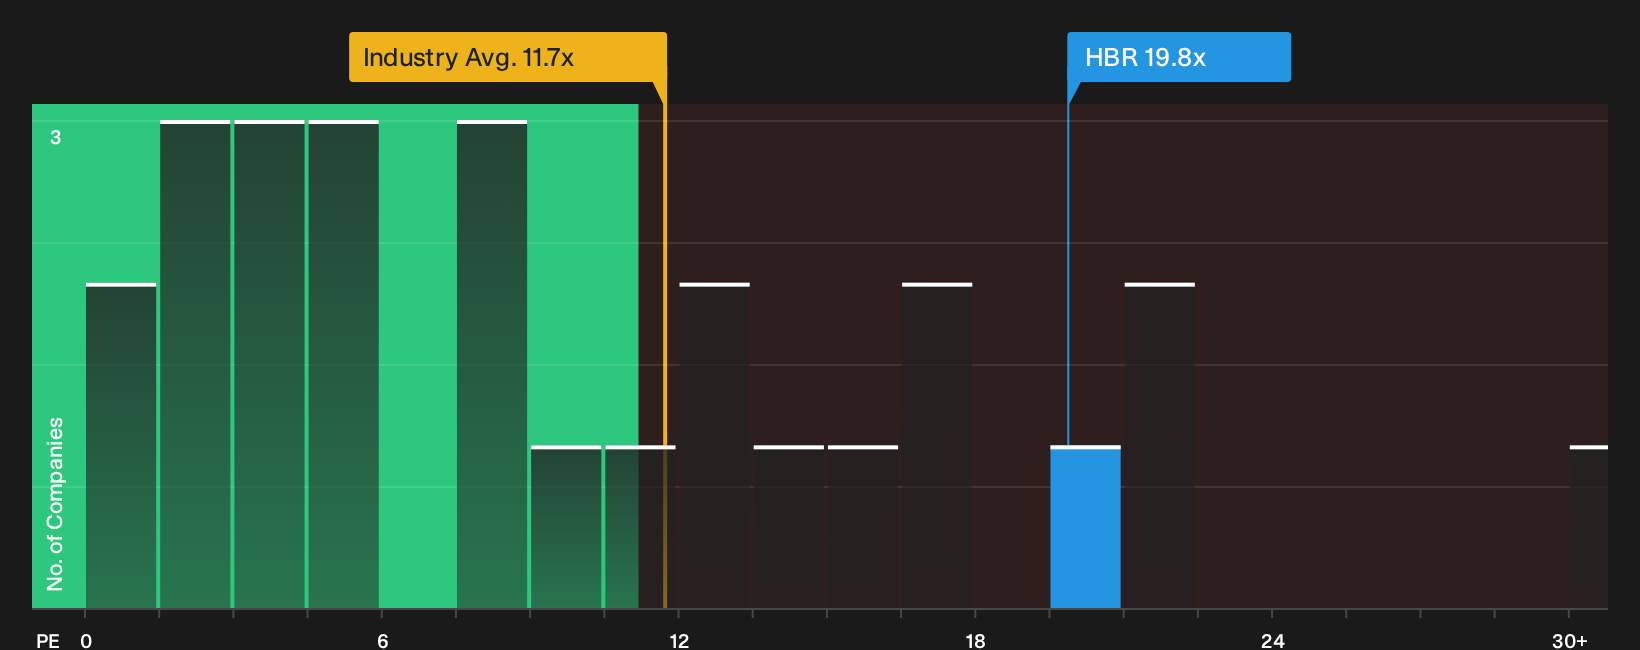
The story looks different once you step away from the SWS DCF model and focus on what investors are actually paying per pound of earnings. Harbour Energy trades on a P/E of 19.8x compared with a fair ratio of 19x, a peer average of 16x and a wider European oil and gas average of 11.7x.
That gap means the share price already asks you to pay more than the sector and more than peers for each unit of profit, even as analysts still debate the long term earnings path. If the market drifts closer to the fair ratio or industry level, how comfortable are you with the valuation cushion built into your thesis.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Harbour Energy share price and valuation debate call for your own judgment, not just a headline takeaway. Move quickly, pull up the numbers that matter most to you, then weigh both the upside potential and the pressure points through the 3 key rewards and 2 important warning signs.
Looking for more Harbour Energy investment ideas?
If you like Harbour Energy but do not want all your capital tied to one story, use the Simply Wall St Screener to spot other opportunities before they move.
- Target quality at a discount by scanning companies with strong fundamentals through the 5 high quality undiscovered gems.
- Prioritise staying power in tougher conditions and filter for financially resilient businesses using the list of solid balance sheet and fundamentals (9 results).
- Dial down portfolio swings and focus on steadier performers with the 5 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com