


Preformed Line Products (PLPC) drew attention after an analyst upgrade to Outperform, citing strong third quarter sales and operating income, rising U.S. electrical infrastructure demand, and management’s focus on international expansion.
Recent trading has been choppy for Preformed Line Products, with the share price down 24.57% over 30 days and 36.76% over 90 days, even after a strong 16.58% 7 day share price return following the Outperform upgrade and third quarter results.
Compare this Outperform story with other grid and infrastructure suppliers by scanning our hand picked 43 power grid technology and infrastructure stocks that are also tied to U.S. power and transmission spending trends.
After a sharp pullback and a fast 7 day rebound, Preformed Line Products now forces a choice. Is this a window to trade the volatility, or a setup to wait for a cleaner valuation entry?
Preferred P/E of 24.5x: Is it justified?
Valuation for Preformed Line Products currently hinges on a P/E of 24.5x at a last close of $293.82, which puts the stock at a richer earnings multiple than its own fair P/E estimate yet below key peer benchmarks.
The P/E ratio compares what investors pay for each dollar of earnings. For an equipment supplier tied to grid buildout and communications networks, that matters because earnings power is influenced by long project cycles, capital budgets, and contract visibility rather than short term sentiment alone.
In this case, the SWS fair P/E is estimated at 21.8x. The market is paying more than that reference level, which suggests investors are willing to ascribe a premium to Preformed Line Products relative to that model. At the same time, the current 24.5x P/E is below the broader US Electrical industry average of 27.9x and also below the peer group average of 29.2x, a gap that signals investors are discounting PLPC compared to similar businesses even as the fair ratio model points to a lower level the multiple could move toward.
Explore the SWS fair ratio for Preformed Line Products.
Result: Price-to-earnings of 24.5x (ABOUT RIGHT)
Still, the recent share price slide over 30 and 90 days, along with the richer P/E versus the fair estimate, leaves Preformed Line Products exposed if sentiment or earnings expectations cool.
Find out about the key risks to this Preformed Line Products narrative.
Another View: What the SWS DCF model says about Preformed Line Products
The SWS DCF model comes to a different conclusion for Preformed Line Products. On this view, the stock at $293.82 trades above an estimated future cash flow value of $241. That points to the shares looking overvalued on cash generation rather than reported earnings.
For anyone weighing these two signals side by side, the key question is which measure you trust more: the earnings multiple or the cash flow math, given how wide the spread is between $241 and $293.82.
Look into how the SWS DCF model arrives at its fair value.
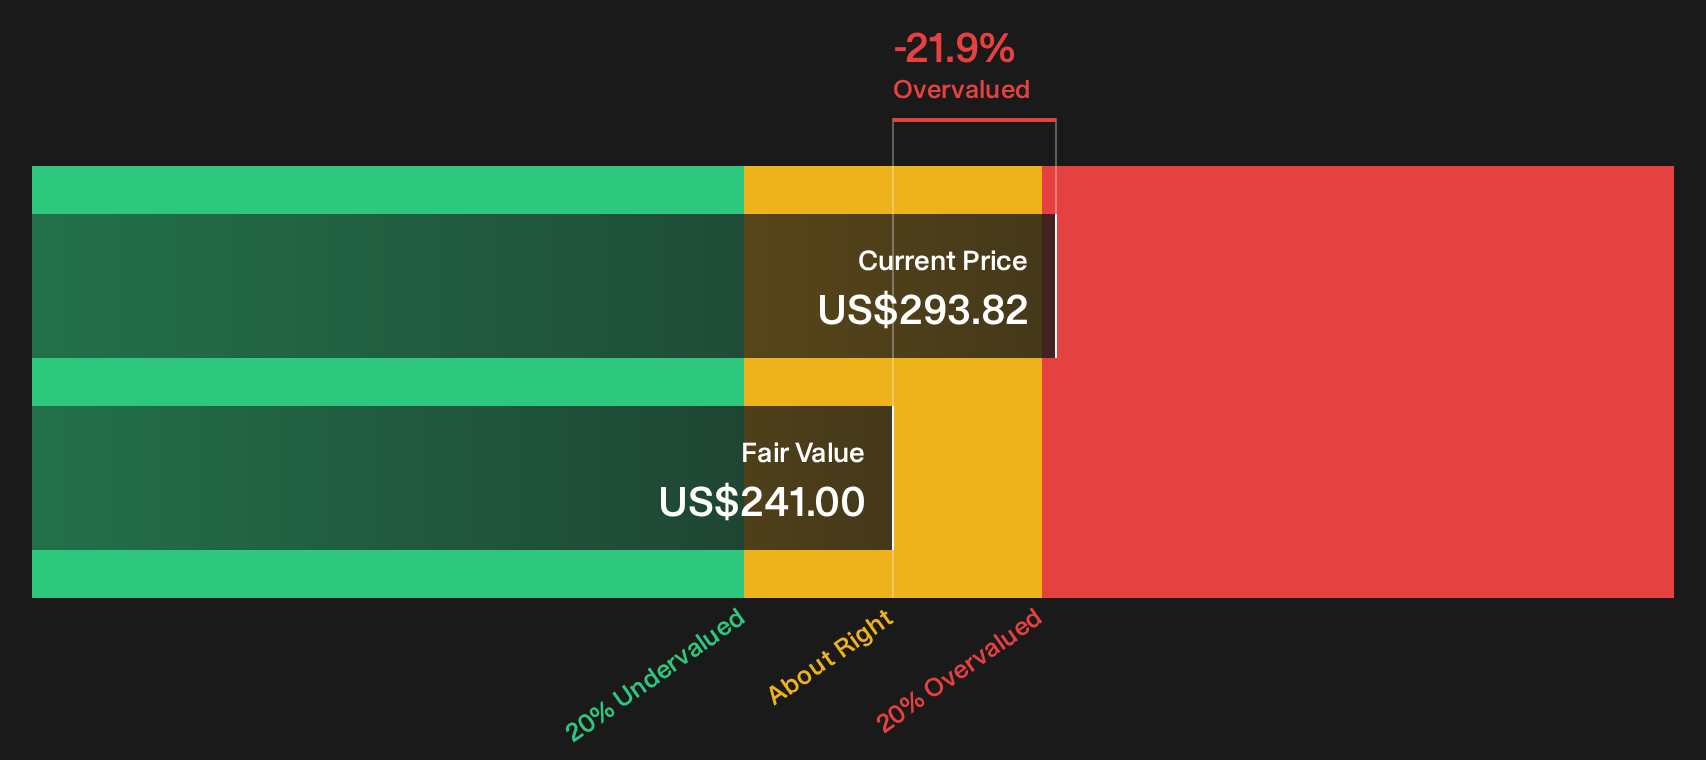
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Preformed Line Products for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around valuation and sentiment can be useful if you move quickly and test the numbers yourself instead of relying on headlines. To weigh both the concerns and the potential upside in Preformed Line Products, start with the 3 key rewards and 1 important warning sign
Looking for more Preformed Line Products investment ideas?
Once you have a view on Preformed Line Products, do not leave your portfolio hinged on a single story. Put a few strong alternatives on your radar.
- Spot potential mispricing early and size up companies trading on appealing valuations with the 31 high quality undervalued stocks.
- Build a steadier core by focusing on income opportunities through the 6 dividend fortresses.
- Dial back portfolio stress and lean into stability by scanning the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com