


- Cintas reported its first fiscal 2027 quarter in the past, with revenue above $3 billion, a record operating margin, and a 15.6% dividend increase alongside ongoing share repurchases.
- The combination of higher shareholder distributions and strong first aid and safety services performance highlights how Cintas is using cash generation to reinforce its service-led business model.
- This article now examines how Cintas’ recent record operating margin shapes the broader investment narrative and what that could mean for investors.
Scan how Cintas uses cash generation, then size up other service-led businesses through our curated list of list of solid balance sheet and fundamentals (23 results).
Cintas Investment Narrative Recap
To own Cintas, you need to be comfortable with a service heavy operation that depends on steady customer retention, efficient routes, and disciplined cost control. The recent record operating margin supports that story in the near term. The key short term catalyst is whether management can keep extracting efficiency gains as fuel and other input costs move around. According to LunaRodas, an investor in the Simply Wall St Community, margin expansion already relies on a long list of small process wins.
The biggest risk right now sits in execution rather than demand. Management has already flagged workday timing, fuel, and Fire Protection margins as areas that can swing from quarter to quarter. That means the recent quarter does not remove the possibility of softer margins later in fiscal 2027. It shows what the model can produce when conditions line up and projects run on schedule.
The UniFirst acquisition review is the announcement that now matters most for this story. Cintas has bridge financing in place and expects roughly US$4m of net interest expense from that in fiscal 2027. That is not large against a business with more than US$11.5b of revenue, but it still adds another execution task to track alongside normal capital allocation.
LunaRodas argues that previous calls leaned heavily on cross sell runway, route efficiency projects like SmartTruck, and margin work in Fire. The UniFirst deal, if completed, would plug directly into that operating playbook and could test how scalable those efficiency levers really are. The flip side is clear. Any delay or heavy integration cost would land directly on the same operating margin investors are now watching so closely.
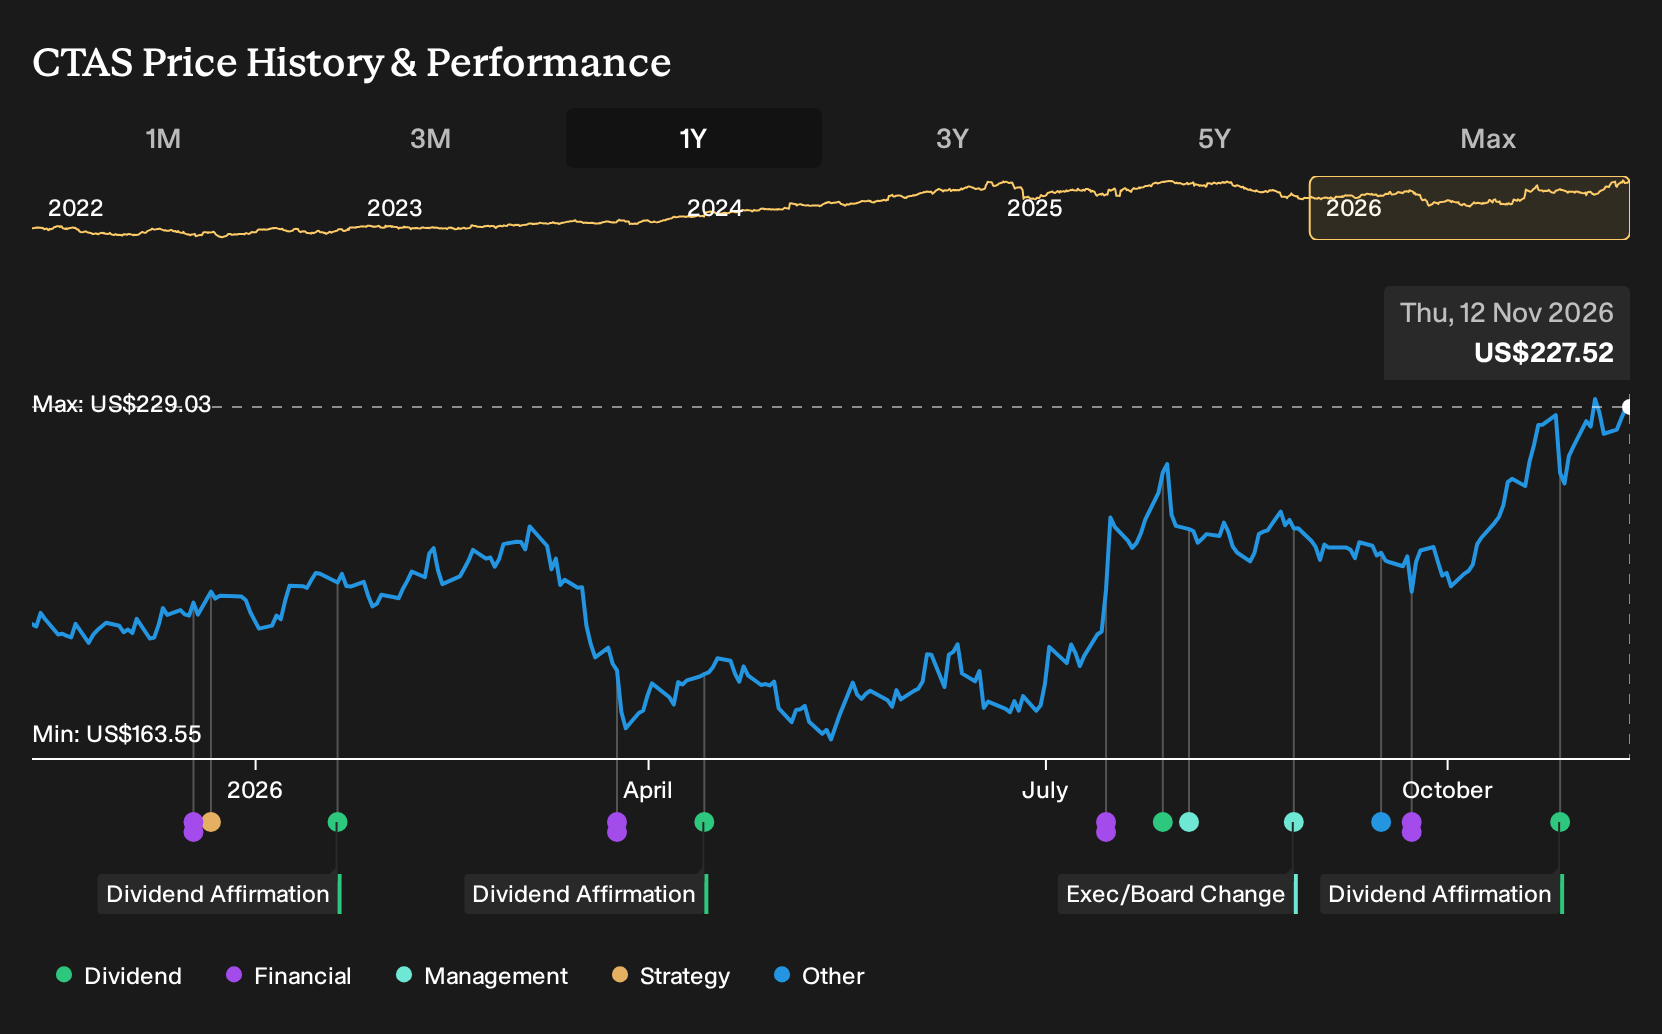
LunaRodas anchors the fair value at US$183.22 on the idea that Cintas’ record operating margin, tighter incremental guidance and disciplined use of cash for dividends, buybacks and the UniFirst bridge all point to an earnings profile that, in that narrative, justifies that valuation level.
Uncover why Cintas' fair value indicates a 19% potential downside to its current price, suggesting that the current premium may not be sustainable.
Exploring Other Perspectives
One alternate view on Cintas leans heavily on automation and remote work as long-term drags on uniform demand. Those analysts were already cautious before this record margin quarter and were assuming revenue of about US$14.1b and earnings near US$2.7b by 2029. That is a much cooler story. Use it as a prompt to test your own assumptions around this latest update.
Explore 6 other Cintas fair value estimates, including one that suggests there could be as much as 30% downside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own view.
- A great starting point for your Cintas research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Cintas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cintas' overall financial health at a glance.
Looking for more Cintas-like investment ideas?
If the Cintas story has sharpened your thinking on quality, capital allocation, and consistency, it makes sense to widen the search to other stocks with similar traits. The Simply Wall St Screener can help you quickly narrow the field to companies that better fit your preferred mix of resilience, income, and upside potential.
- For investors who want staying power at the top of the list, start with companies that score well on balance sheet strength and fundamentals by scanning our list of solid balance sheet and fundamentals (23 results).
- If you are hunting for under-the-radar opportunities with quality metrics that still look reasonable, cast a wider net across our 20 high quality undiscovered gems.
- Income focused investors who care about durability as much as headline yield can zero in on potential cash generators with the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com