


Fortinet (FTNT) has drawn attention after raising its 2026 outlook for the third time this year, following third quarter results that exceeded guidance and the rollout of new AI security services.
Recent trading captures the push and pull around Fortinet. The 7 day share price return of 5.74% follows a much sharper 30 day drop of 32.09%, even though the year to date share price return sits at 66.33% and the 3 year total shareholder return is 156.92%. This points to strong long term momentum despite a reset in expectations as investors weigh the raised 2026 outlook, new AI security launches like FortiAIGate on the Equinix Distributed AI Hub, and concerns about decelerating product growth and margins.
Capitalize on the AI security momentum around Fortinet by benchmarking it against a curated set of peers using our 53 AI infrastructure stocks.The recent slide followed by a sharp bounce leaves Fortinet at an interesting crossroads. Has the bulk of the re rating already played out, or does the current price still leave meaningful upside on the table based on fundamentals?
Most Popular Narrative: 3% Overvalued
Against a last close of $129.54, the narrative fair value of $125.56 suggests Fortinet is pricing in a small premium, which puts extra focus on how durable its AI security angle really is. According to rdiab, an investor in the Simply Wall St Community, the narrative turns on Fortinet’s role as a core supplier to AI data center build outs rather than a pure software story.
AI isn't just about software; it requires massive physical data centers, and those data centers need to be secured. Fortinet recently launched its new FortiGate G series appliances specifically designed for AI-centric enterprise workloads, as well as new AI-powered endpoint security tools.
See why 18 investors see Fortinet as 3% overvalued.
Result: Fair Value of $125.56 (OVERVALUED)
Still, the Fortinet narrative could be shaken if AI data center security budgets tighten, or if competitors undercut pricing on high end firewall hardware.
Find out about the key risks to this Fortinet narrative.
Another View: Fortinet Through A Cash Flow Lens
While the Simply Wall St community narrative frames Fortinet as about 3% overvalued at $129.54 versus a $125.56 fair value, the SWS DCF model tells a different story. On that framework, the stock is trading around 11% below an estimated future cash flow value of $145.61. That gap raises a simple question for investors: Which signal carries more weight, sentiment around rich multiples or a cash flow model pointing to undervaluation?
Look into how the SWS DCF model arrives at its fair value.
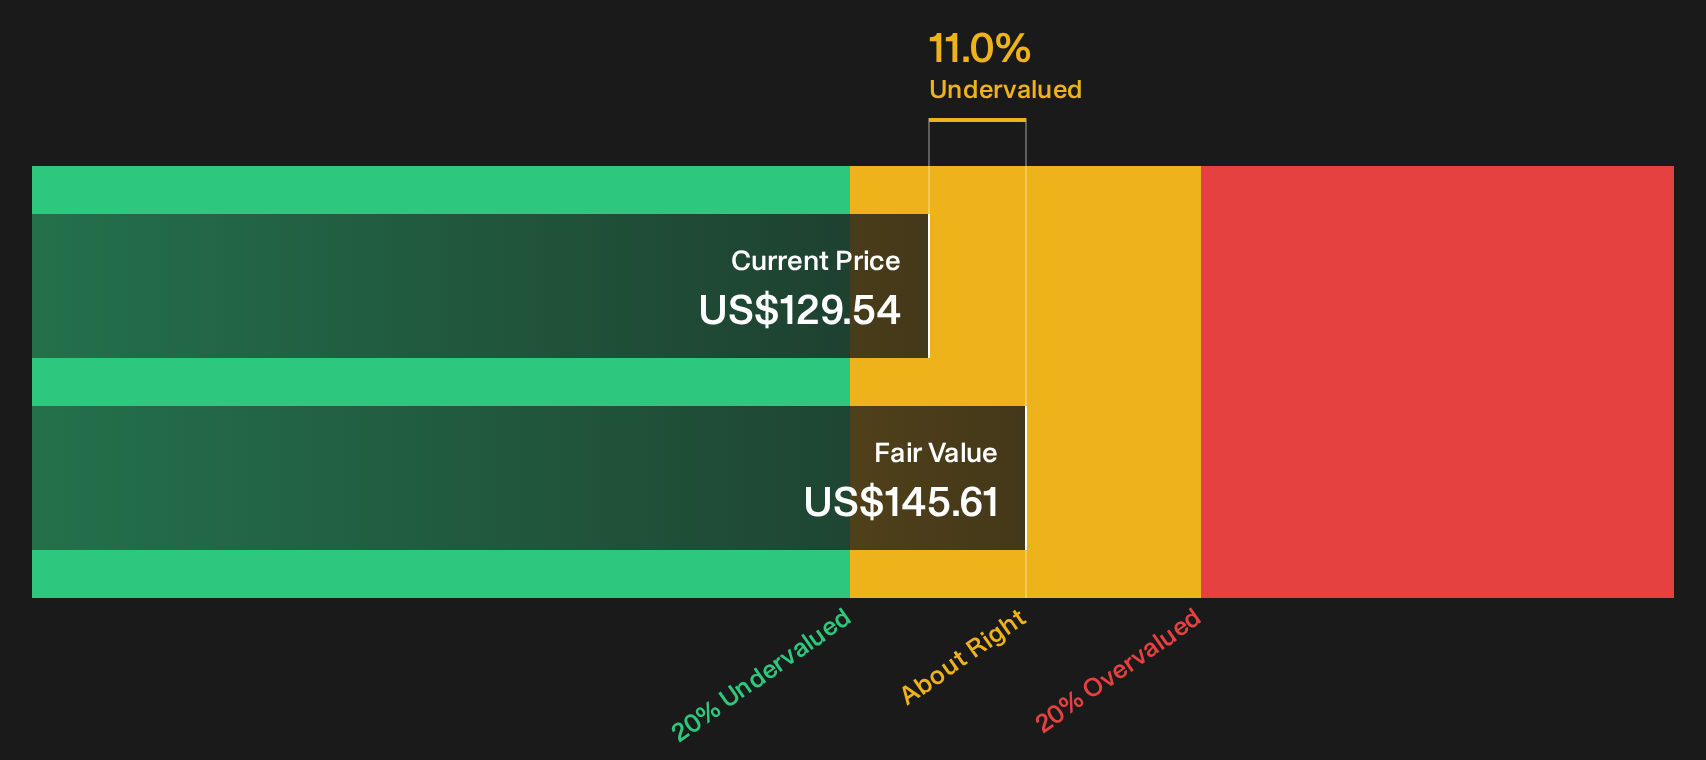
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Fortinet for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If sentiment in this Fortinet piece feels mixed, that is exactly why checking the underlying data yourself matters, and doing it soon keeps you ahead. To see which potential bright spots investors are already watching, review the 3 key rewards.
Looking for more investment ideas beyond Fortinet?
If Fortinet has sharpened your focus on quality, cast the net wider and use the Simply Wall St Screener to pressure test other ideas before capital moves.
- Target steadier potential returns by reviewing companies on our 29 resilient stocks with low risk scores.
- Hunt for mispriced opportunities by scanning the 31 high quality undervalued stocks.
- Strengthen your watchlist with balance sheets that can handle shocks using the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com