


How the latest earnings update frames Canadian Utilities for investors
Canadian Utilities (TSX:CU) has put fresh numbers on the table with third quarter earnings, giving investors a new look at how this regulated utility is currently trading and performing.
Recent trading has reflected that mixed earnings picture. Canadian Utilities has climbed to CA$53.24, with a 10.53% 1 month share price return and a 24.42% year to date share price gain. The 1 year total shareholder return of 29.04% and 3 year total shareholder return of 95.87% point to momentum that has been building over time rather than fading.
Scan how Canadian Utilities compares with other regulated players by running through our curated list of 43 power grid technology and infrastructure stocks.
Canadian Utilities now trades close to its CA$53.24 share price, while analyst targets sit higher and an intrinsic estimate signals a wider gap. Where does fair value realistically land between those two anchors?
Most Popular Narrative: 6.6% Undervalued
On the analyst consensus Narrative on Simply Wall St, Canadian Utilities screens as undervalued, with a fair value of CA$57 against the latest CA$53.24 close. This frames a modest discount that depends on how future growth and profitability develop.
Substantial investment in grid modernization and expansion, including major projects like the Central East Transfer-Out and the 90% contracted Yellowhead pipeline, is described as positioning Canadian Utilities to benefit from rising power and gas demand from electrification and industrial activity, which in turn is expected to support potential increases in rate base and long-term revenue.
See why 43 investors see Canadian Utilities as 7% undervalued.
Result: Fair Value of CA$57 (UNDERVALUED)
Still, the narrative around Canadian Utilities could be knocked off course if Alberta regulatory outcomes cut into allowed returns, or if heavy project spending strains cash flow and leverage.
Find out about the key risks to this Canadian Utilities narrative.
Another view on Canadian Utilities’ valuation
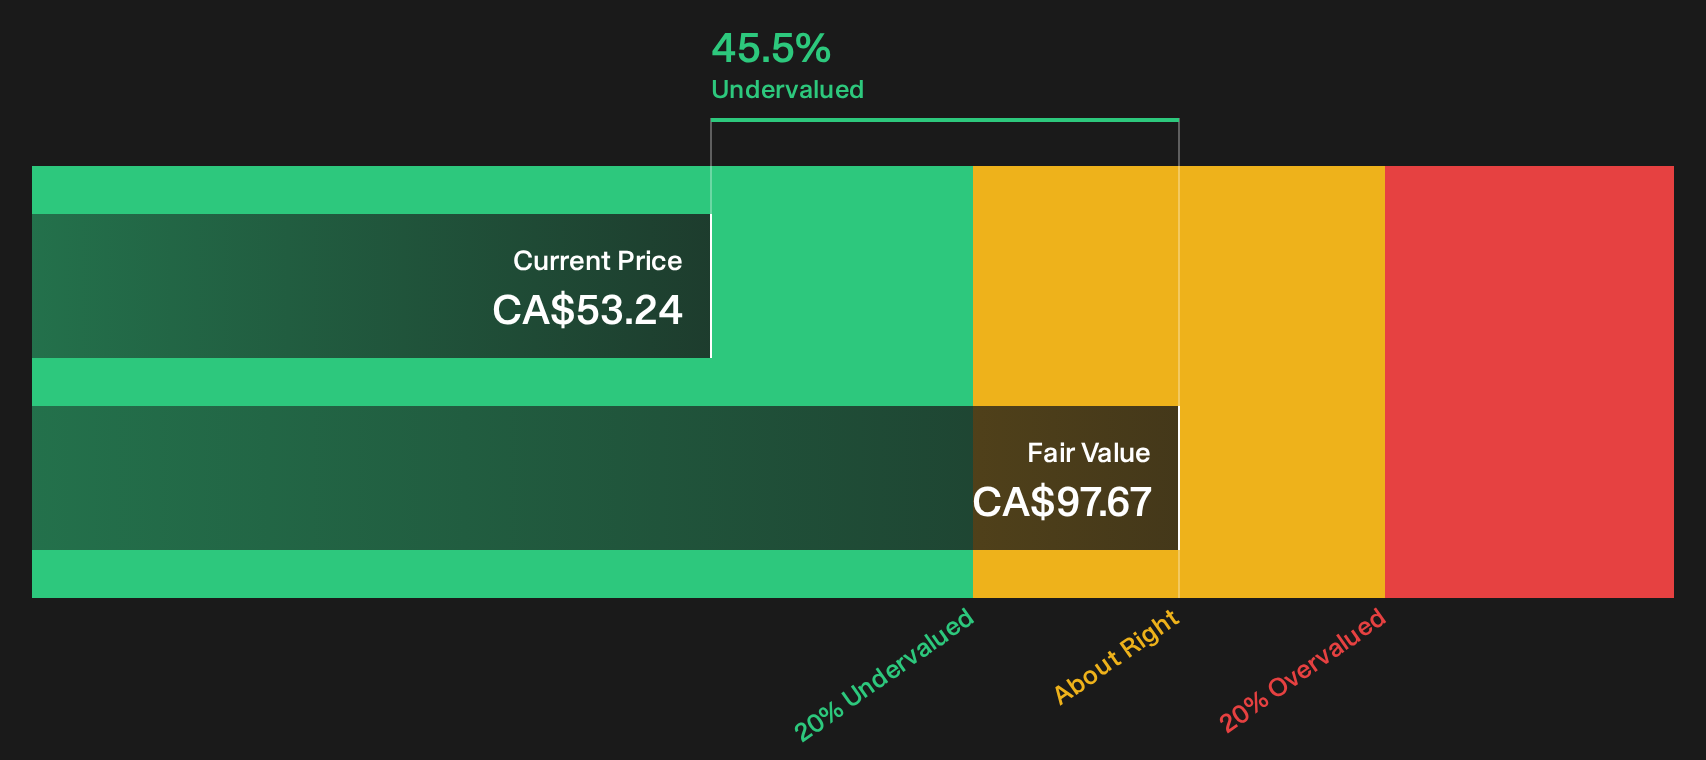
The first take on Canadian Utilities leans on analyst targets and a narrative fair value of CA$57. Our DCF model paints a very different picture, with an estimate of CA$97.67 that points to a far deeper undervaluation. Which set of assumptions do you trust more?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Plenty of signals around Canadian Utilities point in different directions, so now is the time to review the evidence yourself and stress test your stance. To see the balance of risk and upside that other investors are focused on, start with these 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Canadian Utilities?
If Canadian Utilities has sharpened your thinking, now is the moment to widen the net and line up a few fresh ideas before the crowd catches on.
- Hunt for underpriced quality by checking stocks in the 6 high quality undervalued stocks that combine solid fundamentals with room for sentiment to catch up.
- Prioritise resilience and sleep-better-at-night balance sheets by scanning companies in the list of solid balance sheet and fundamentals (5 results) that keep financial risk in tighter check.
- Get ahead of the market by reviewing the 8 high quality undiscovered gems that pair strong fundamentals with lower investor attention before they draw wider interest.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com