


Suncor Energy has delivered a powerful run for long term holders, so the question now is whether the current share price is still grounded in what the business is earning. After such a strong stretch, investors are rightly asking if the earnings story has kept pace with the move in the stock.
- Over the past 5 years, Suncor Energy has returned about 277.6%, which puts a lot of weight on whether its earnings can continue to support a price near the recent C$98.80 close.
- Record cash generation, higher dividends, larger buybacks and the planned exit from offshore assets all point to management reshaping Suncor Energy around projects that can influence future margins and cash flow per barrel.
- There is a second opinion on Suncor Energy worth weighing. See what analysts think Suncor Energy's shares could be worth.
The issue now is whether Suncor Energy's current valuation is justified by the earnings power that its integrated operations are delivering today.
If you want a wider starting list while you assess Suncor Energy's earnings story, it can help to run the same questions across 6 high quality undervalued stocks.
Does Suncor Energy Look Undervalued on Earnings?
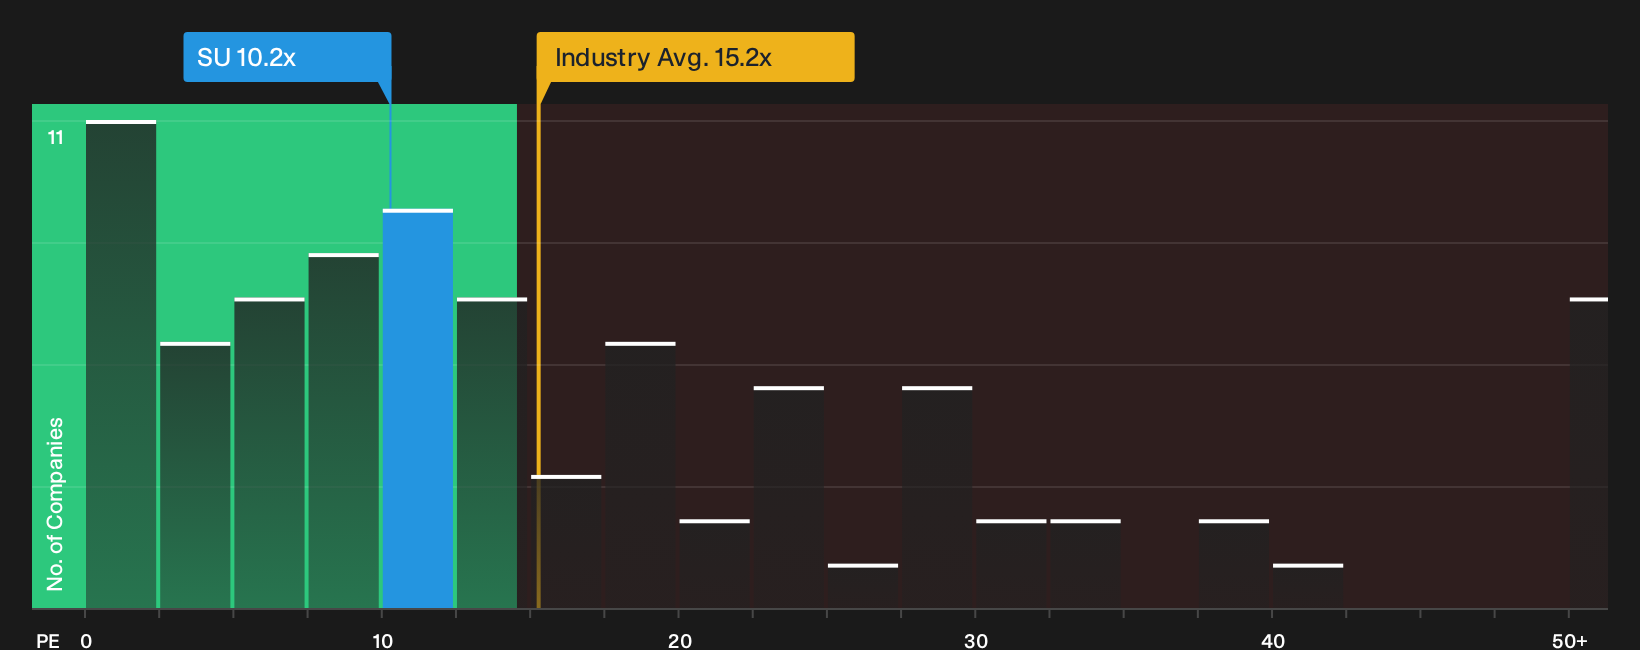
The P/E ratio is a useful lens for Suncor Energy because earnings are a central piece of how investors judge integrated oil and gas groups. On this measure, Suncor trades at about 10.2x earnings. The broader Oil and Gas industry shows an average P/E of roughly 15.2x, while direct peers cluster near 14.4x.
Recent record Q3 2026 cash generation and higher capital returns have not pushed Suncor Energy up to those peer levels, so the stock currently changes hands at a discount to both the industry yardstick and similar companies. A valuation framework that adjusts for the firm’s own growth profile, margins, size and risk points to a higher P/E as more in line with those fundamentals, which leaves the present 10.2x multiple screening as undervalued on this earnings yardstick. Explore the numbers behind Suncor Energy's P/E valuation.
The Suncor Energy Narrative: What Would Justify Today's Price?
Suncor Energy's valuation gap raises a simple question for investors: what type of future would need to play out for that discount to close or widen? Simply Wall St Narratives sit on the Community page and turn that question into explicit earnings paths for Suncor Energy. Each conclusion about upside or downside links back to a specific view on how growth, profitability and risk could evolve, and can be reconsidered as fresh information comes through.
Bulls see Suncor Energy as a cash machine being reshaped around higher margin barrels, while bears focus on how hard it could be to keep current margins intact.
Bull case: 14% undervalued
The analyst consensus Narrative on Simply Wall St frames the upside around cash generation from an integrated system that already looks more efficient.
"Record adjusted funds from operations of $5.3b in Q2 2026 at WTI levels about $15 per barrel below the prior peak period indicate that Suncor Energy’s integrated oil sands, refining, and marketing system is already delivering higher cash generation efficiency…"
Discover why this Narrative puts Suncor Energy at 14% undervalued.
Bear case: roughly fairly valued
The bearish analyst Narrative on Simply Wall St stresses how dependent the story is on keeping very high utilization and capital discipline going.
"Reliance on very high utilization of existing oil sands and refining assets, including refinery runs consistently at or above 100% and upgrader utilization above 100%, leaves little unused capacity to offset unplanned outages…"
Explore why this Narrative puts Suncor Energy at roughly fairly valued.
Suncor Energy’s valuation still leaves one crucial angle unexplored
Suncor Energy’s pricing story only goes so far without weighing the underlying pressure points that our checks have picked up, and those potential weak spots are what could reshape how you judge the whole case. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com