


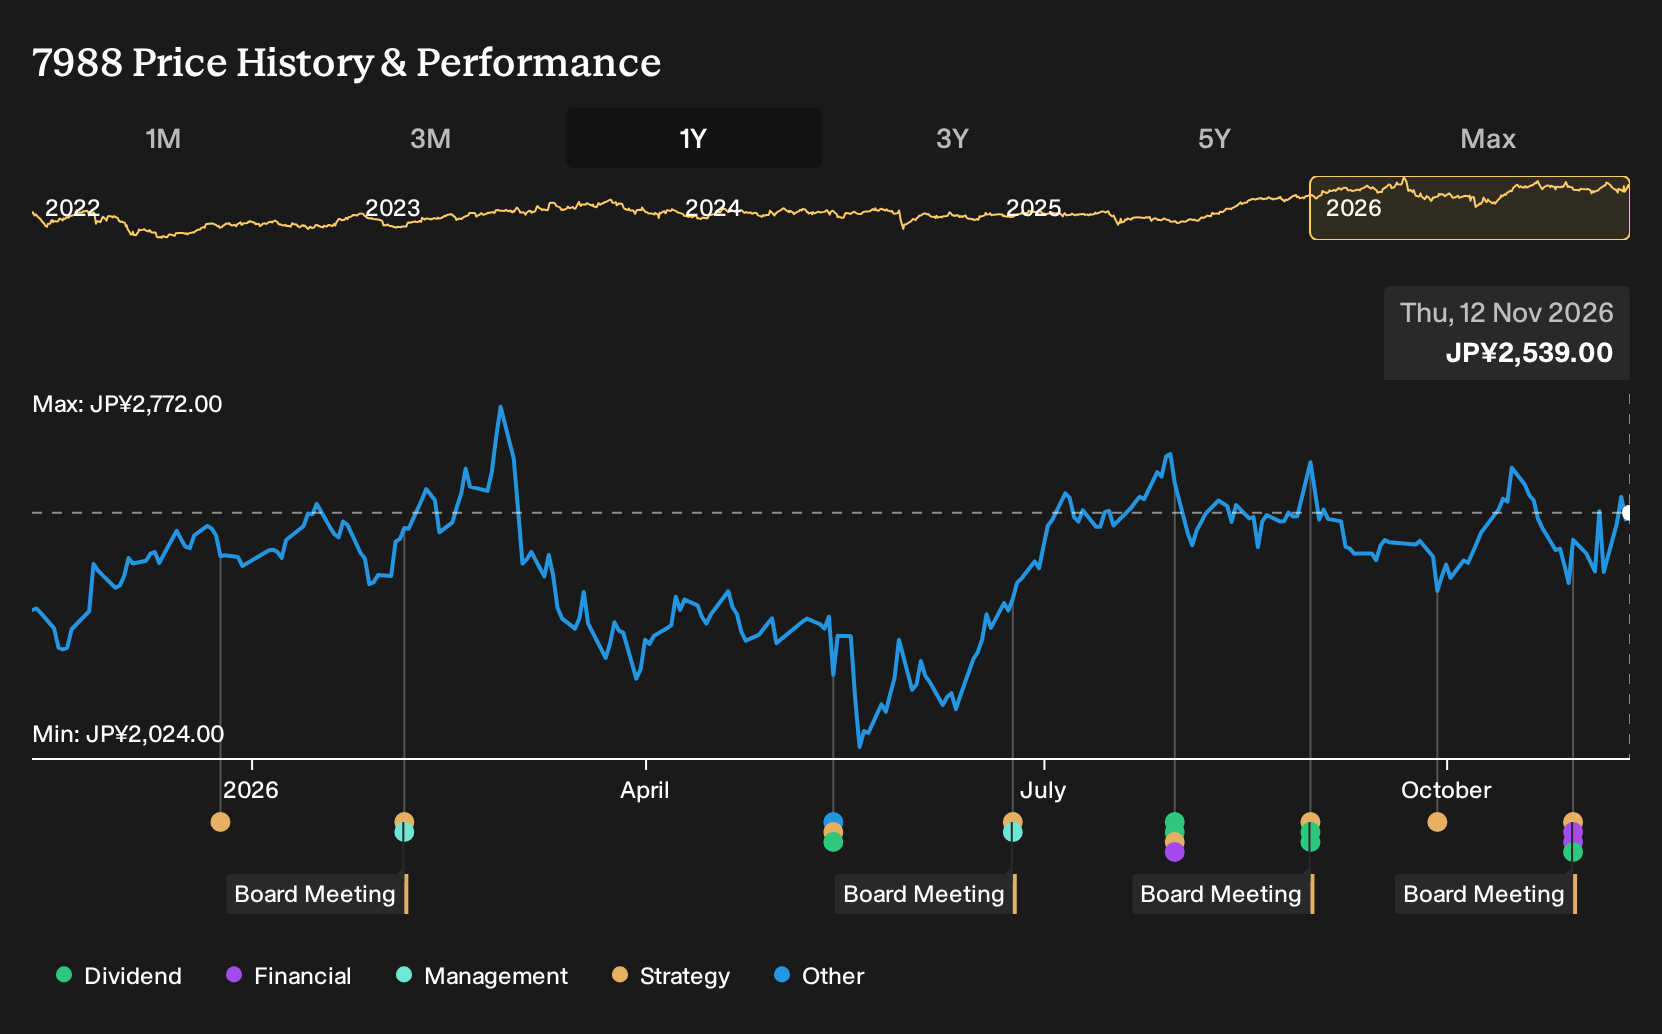
- Nifco reported half year sales of ¥185,950 million and net income of ¥17,214 million, raised the second quarter dividend to ¥56.00 per share, and issued consolidated earnings guidance for the fiscal year ending March 31, 2027.
- The combination of a higher interim dividend and specific profit and earnings per share targets provides investors with clearer insight into Nifco's capital return approach and earnings profile.
- The focus now turns to how Nifco's higher interim dividend may shape the broader investment narrative for the business.
What Is Nifco's Investment Narrative?
Nifco’s story really hinges on whether you believe a focused industrial plastics group can keep turning steady demand into acceptable returns, even as growth stays moderate. The latest guidance for the year to March 2027 sketches out a business that is aiming for ¥367,000 million in net sales and ¥34,000 million in profit attributable to owners, while also funding a richer dividend and new stock based incentives. That mix suggests that management is leaning into shareholder returns, while still maintaining ongoing investment in operations.
The new stock ownership allocation and special incentive scheme tie employees and directors more tightly to earnings per share targets around ¥198.53. In the short term, the big swing factors are still execution on auto and industrial volumes, pricing power in a competitive components market, and the impact of these factors on already compressed net margins around 9%. Dividend growth and equity compensation are secondary. They matter because they raise questions about cash needs if demand softens again or capital intensity increases.
Yet there is one part of Nifco’s capital return story that could look very different once you consider ...
There's only one way to know the right time to buy, sell or hold Nifco. Head to Simply Wall St's company report for the latest analysis of Nifco's Fair Value.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Nifco research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Nifco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nifco's overall financial health at a glance.
Looking For More Ideas Beyond Nifco?
If Nifco has sharpened your focus on dividends, cash generation, and earnings guidance, it can be useful to line those themes up against a wider field of listed businesses. The Simply Wall St Screener lets you filter for companies that match your priorities, whether you care most about income, balance sheet resilience, or stocks that the market might be overlooking.
- If capital preservation and a smoother ride matter most to you, start with companies that screen as more resilient using our 20 resilient stocks with low risk scores to see which ones fit that brief.
- If the priority is finding quality businesses that the market might be underpricing, check out a curated set of potential bargains through the 74 high quality undiscovered gems for fresh ideas.
- If you prefer stocks that pair fundamental strength with cleaner balance sheets, filter for companies with stronger financial footing using the list of solid balance sheet and fundamentals (25 results) and compare how they stack up against Nifco.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com