


When a long time tech architect like Jensen Huang steps down from Nvidia, it reminds investors how much leadership can shape entire industries, not just single companies. Australian founder led businesses put that same personal imprint on decision making, often with founders heavily tied to long term outcomes. This article explains why that matters now and highlights three founder driven Australian stocks from the screener to put on your watchlist.
The three stocks highlighted here offer a compelling starting point if you want exposure to founder led businesses where leadership is tightly aligned with long term performance. However, if you want the standouts, these 8 top founder-led companies are the most outstanding.
Flight Centre Travel Group (ASX:FLT)
Overview: Flight Centre Travel Group runs founder-linked leisure and corporate travel brands that connect customers with airlines, hotels, cruises and broader travel services worldwide.
Operations: Flight Centre Travel Group generates about A$1.43b from Leisure, A$1.18b from Corporate and A$248 million from Global HQ support functions.
Market Cap: A$2.44b
For investors drawn to founder-led legacies, Flight Centre Travel Group brings long standing leadership continuity to a global travel intermediary that is still reshaping where it focuses its effort and capital. This is exactly what the bearish analyst Narrative on Simply Wall St puts under the microscope.
"Although Flight Centre is reallocating capital toward cruise, luxury, Meetings & Events and foreign exchange, the recent guidance cut linked to a mix shift toward lower margin carriers highlights a risk that product mix and supplier choice continue to dilute yield, which can cap revenue per transaction and keep operating margins under pressure."
What happens if one quiet shift in how high value customers are served meaningfully changes the balance between volume growth and profitability?
That trade off is exactly where the story gets interesting, and the full narrative for Flight Centre Travel Group shows how Flight Centre Travel Group’s founder legacy could turn mix pressure into accelerating upside.

Pro Medicus (ASX:PME)
Overview: Pro Medicus develops founder-led Visage medical imaging software and related services that help hospitals and clinics manage and interpret diagnostic scans efficiently.
Operations: Pro Medicus generates about A$261.7 million from integrated healthcare software, mainly in Australia and North America, with smaller European contributions.
Market Cap: A$21.2b
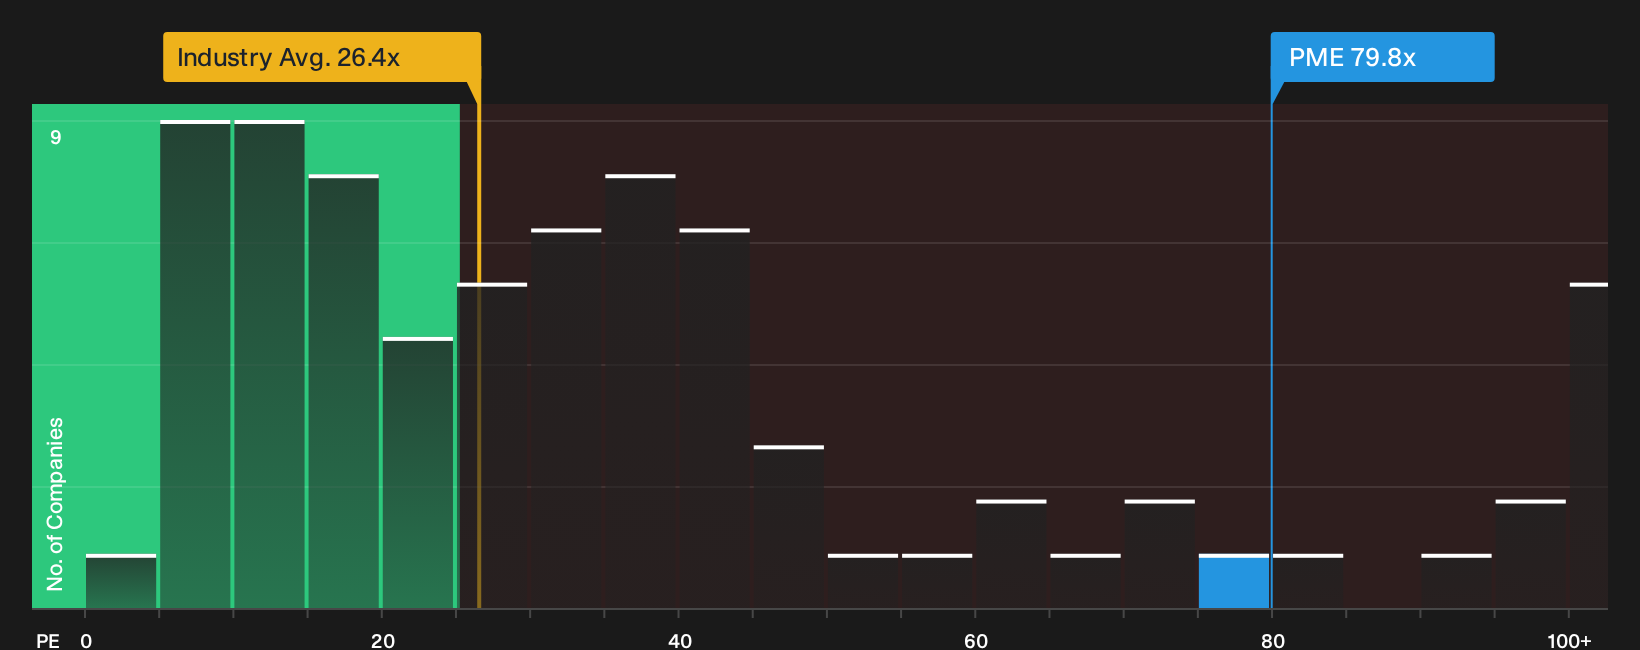
Pro Medicus fits the Founder-Led Companies theme because its Visage platforms still reflect the product vision of long-serving founder leadership, and according to ZayaanS, an investor in the Simply Wall St Community, that culture shows up most clearly in how radiologists actually use the software.
"Radiologists at top US hospitals have started demanding it as a condition of employment. They simply won't join institutions that don't run Visage, the company's flagship imaging platform."
What happens if even a small shift in that kind of practitioner pull changes how much pricing power and contract quality Pro Medicus can sustain.
If that pricing power story intrigues you, read the full narrative for Pro Medicus to see how radiologist demand could be accelerating a much bigger Pro Medicus opportunity.
Mesoblast (ASX:MSB)
Overview: Mesoblast develops founder-led regenerative medicine therapies based on mesenchymal lineage cells to treat severe inflammatory, cardiac and pain-related diseases.
Operations: Mesoblast generates about $120 million from developing and commercializing its allogeneic cellular medicines platform across its therapy pipeline.
Market Cap: A$2.54b
Mesoblast matters for a founder-led screen because the same leadership that built its mesenchymal cell platform is still steering Ryoncil and the wider pipeline. This is a point the bullish analyst Narrative on Simply Wall St highlights when it connects long term decisions in the lab to potential earnings power.
"The planned “Generation 2” manufacturing process that adds a proprietary recombinant growth-factor supplement, together with automation and US onshoring of production, points to a step change in cell yields and cost of goods. This could widen gross margins as higher volume indications come through."
What happens to Mesoblast’s long term earnings profile if one quiet change in how each vial is made keeps compounding through every new indication?
If that compounding effect on each vial has your attention, go to the full narrative for Mesoblast to see how Mesoblast’s risk and upside profile could be decoupling.

Seeking Alternatives Before The Crowd
Fresh opportunities rarely stay quiet for long. Some tickers are building breakout momentum while they are still under the radar for now. Do not get caught dropping in late, consider taking action in a timely and well-researched way.
- Spot potential turning points early by scanning 3 high quality undervalued stocks before other investors fully recognize strong balance sheets and solid cash generation.
- Explore income-focused ideas by checking 6 dividend fortresses while yields remain elevated and market attention is still elsewhere.
- Review opportunities in the energy build out by using 43 power grid technology and infrastructure stocks before grid upgrade spending reaches a broader range of companies.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com