


Fresh off third quarter results and a higher full year revenue outlook, Ralliant (RAL) is back in focus as investors weigh guidance of US$2.34b to US$2.36b against recent share performance.
Ralliant’s strong third quarter update and fresh guidance arrived after a choppy few months for the shares. A 7 day share price return of 12.32% helped to offset earlier weakness and contributed to a 37.78% year to date share price gain and 49.69% total shareholder return over the past year, suggesting that momentum has recently picked up as investors reassess the earnings outlook and dividend affirmation together with the upcoming investor conference.
Scan how Ralliant’s latest guidance compares with peers re-rating on earnings strength by reviewing the hand-picked 20 high quality undiscovered gems in similar sectors.
After that sharp swing higher and a richer full year revenue range on the table, Ralliant now asks a simple question: Does the current price still leave enough upside to justify the risk?
Most Popular Narrative: 11.8% Undervalued
Against Ralliant’s last close at $70.57, the analyst consensus Narrative on Simply Wall St pins fair value at $80.00. This implies a discount that frames the recent guidance upgrade through a long term lens built on forecasted earnings and cash generation using a 9.21% discount rate.
Planned growth focused CapEx at 2% to 3% of revenue and reinvestment of 50 to 100 basis points of margin into commercial, innovation and manufacturing initiatives are aimed at expanding capacity in defense and utilities and accelerating product refresh cycles, which can support medium term revenue growth and earnings power.
See why 1 investors see Ralliant as 12% undervalued.
Result: Fair Value of $80.00 (UNDERVALUED)
Still, the narrative can crack if Test & Measurement remains under pressure from weaker EV and semiconductor demand, and if China struggles continue to cap Ralliant’s growth options.
Find out about the key risks to this Ralliant narrative.
Another View: Our DCF Model Flags Less Upside
The analyst narrative pegs Ralliant at a fair value of $80.00 and calls the stock undervalued. Our DCF model tells a different story. On Simply Wall St’s cash flow approach, Ralliant at $70.57 trades above an estimated future cash flow value of $55.45, which points to an overvalued outcome instead. Which lens do you trust more when the share price already reflects a lot of future improvement?
To understand how those cash flow assumptions stack up against your own expectations, it helps to see the full mechanics behind the model, not just the headline number. Look into how the SWS DCF model arrives at its fair value.
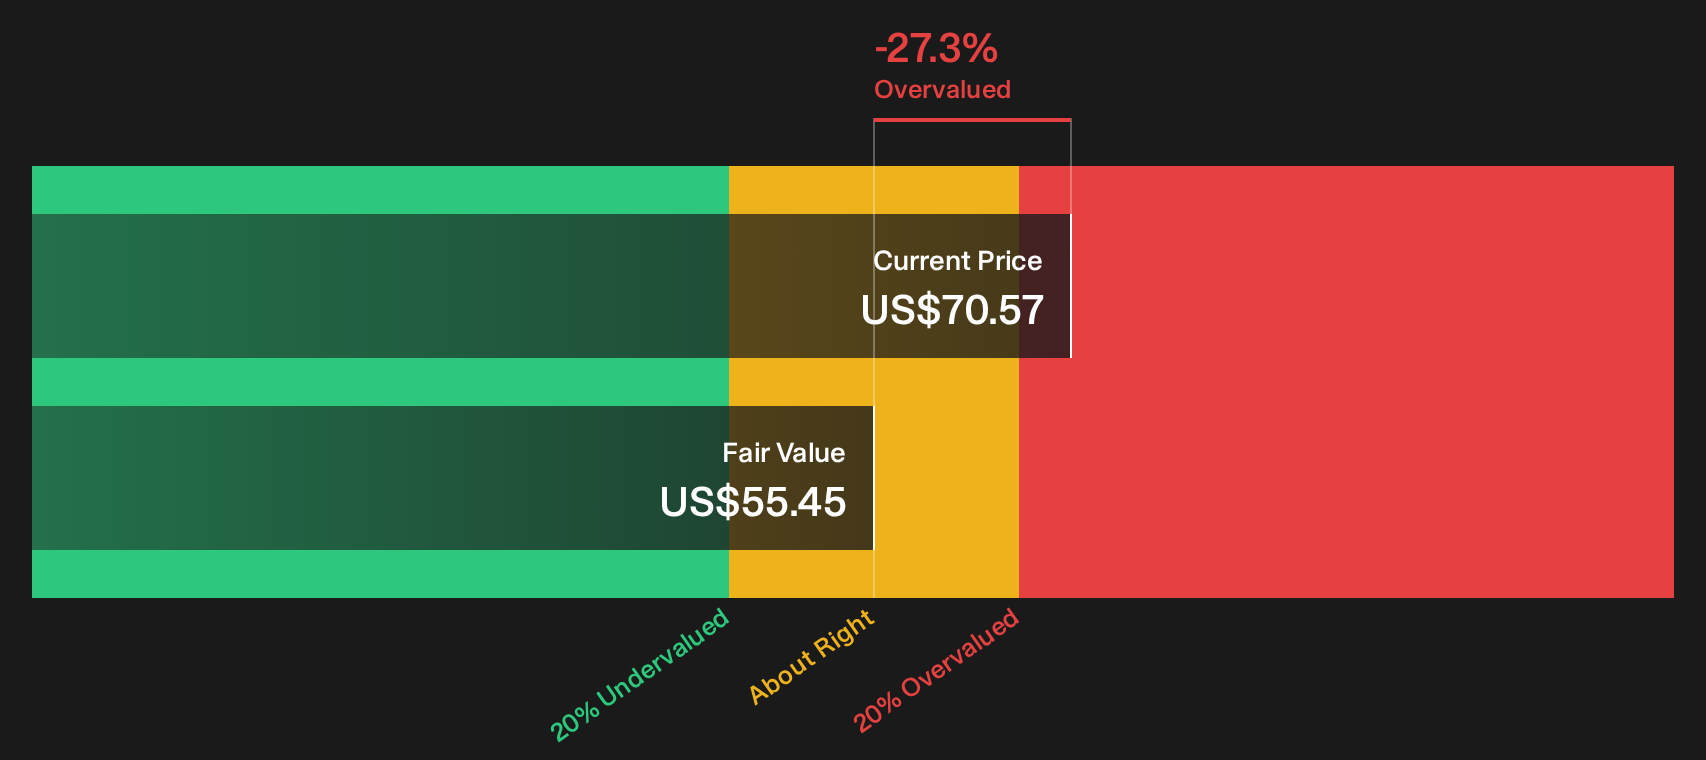
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ralliant for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Ralliant is mixed enough that it pays to move fast and inspect the raw numbers yourself before the story shifts again. To see what optimism in the data looks like in one place, start with the 1 key reward.
Looking for more investment ideas beyond Ralliant?
If you stop with Ralliant, you risk missing other opportunities that fit your goals just as well. Give yourself options and keep your opportunity set wide.
- Target dependable cash generation and stability by reviewing a curated list of solid balance sheet and fundamentals (23 results) that can handle tougher business conditions.
- Hunt for quality at a sensible entry point through a focused 31 high quality undervalued stocks that filters for strength and pricing discipline.
- Prioritise resilience first by scanning a 29 resilient stocks with low risk scores that highlights businesses with fewer red flags and steadier profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com