


ENEOS Holdings (TSE:5020) has just raised its full-year revenue and profit guidance and lifted its dividend forecast, after stronger crude prices and overseas petroleum product markets supported higher expected earnings.
ENEOS Holdings has seen mixed momentum, with the share price down about 10% over the past month and roughly 3% over the last quarter, yet still showing an 11.41% year to date share price return and a 24.36% total shareholder return over one year. This signals that today’s upgraded guidance and higher dividend forecast arrive against a backdrop of longer term strength rather than a sudden rebound.
Scan how ENEOS Holdings compares with other energy plays benefiting from stronger commodity trends by running your eye over our hand picked 18 high quality undervalued stocks.
ENEOS Holdings now pairs upgraded earnings guidance with a richer dividend stream, yet the share price has slipped in recent weeks. That mix of stronger forecasts and weaker momentum raises a simple question: Is the stock already expensive or still reasonable value?
Most Popular Narrative: 25% Undervalued
ENEOS Holdings last closed at ¥1,249.5 against an analyst consensus Narrative fair value of ¥1,665, which points to a material valuation gap. That analyst consensus Narrative on Simply Wall St builds this view on detailed assumptions about portfolio reshaping, overseas refining exposure and capital returns, all discounted at a 5.19% rate.
Expansion of ENEOS Holdings’ overseas refining and marketing through the planned acquisition of Chevron’s assets in Singapore, Australia, Malaysia, the Philippines, Vietnam, and Indonesia for about US$2.17b, which is expected to lift overseas revenue contribution toward 50% by FY 2030 and add to operating profit.
See why 3 investors see ENEOS Holdings as 25% undervalued.
The Narrative assumes relatively flat long term revenue in yen terms, shrinking profit margins and earnings declining to ¥357.3b by around 2029, yet still arrives at a higher fair value than the current share price. That combination suggests the market may be placing a heavier weight on execution risks, governance questions and restructuring costs than the Narrative, which prices ENEOS Holdings using a higher future P/E multiple and a 5.19% discount rate.
Result: Fair Value of ¥1,665 (UNDERVALUED)
Still, the story for ENEOS Holdings can change quickly if governance issues around the Antimonopoly case deepen or if planned refinery and group restructurings drag on earnings.
Find out about the key risks to this ENEOS Holdings narrative.
Another View: ENEOS Holdings And The DCF Gap
The narrative fair value of ¥1,665 paints ENEOS Holdings as undervalued. The SWS DCF model points in the opposite direction. On that cash flow view, the shares around ¥1,249.5 trade well above an estimated future cash flow value of ¥386.72, which leans toward an overvalued call instead.
These two approaches lean in different directions. It helps to understand how cash flow heavy the second model is before deciding which lens you trust more for ENEOS Holdings. Look into how the SWS DCF model arrives at its fair value.
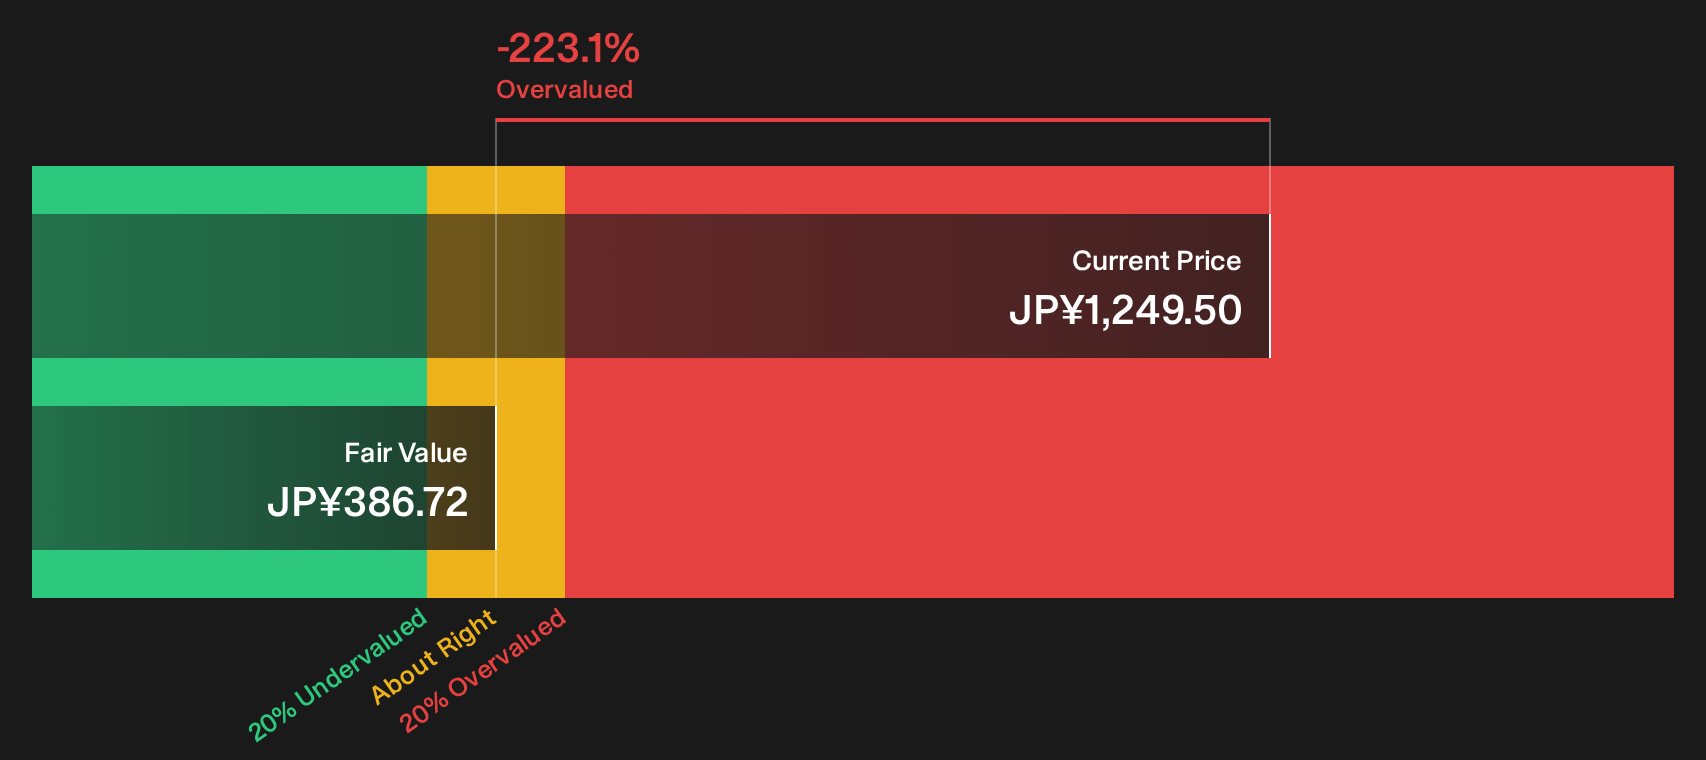
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ENEOS Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around ENEOS Holdings are exactly when you should lean into the data yourself and move quickly to frame your own thesis using the 5 key rewards and 1 important warning sign.
Looking for more ENEOS Holdings sized investment ideas?
If ENEOS Holdings has you thinking harder about price versus quality, use this moment to widen your watchlist with other opportunities that fit your approach.
- Target sturdier portfolios by scanning a list of solid balance sheet and fundamentals (25 results) that can help you stress test ideas beyond ENEOS Holdings.
- Hunt for mispriced potential by reviewing a 74 high quality undiscovered gems that may not yet be crowded with attention.
- Dial down volatility risk by working through a 20 resilient stocks with low risk scores tailored for investors who prize resilience when conditions turn choppy.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com