


Sempra has pulled back over the past year even after a strong multi year run, which puts a spotlight on whether the current share price lines up with what its earnings can support. With fresh news around its Texas and infrastructure operations, the question now is how much of that story is already reflected in the valuation.
- Over the past 5 years, Sempra has returned about 50.5%, which makes the current pullback an important test of how firmly its earnings underpin that longer term gain.
- The decision to increase Oncor's multi year capital plan and simplify the business around core utilities can reshape future profit growth expectations and the timing of cash flows that support the stock's earnings profile.
- There is a second opinion on Sempra worth weighing. See what analysts think Sempra's shares could be worth.
The issue now is whether Sempra's current share price is justified by its earnings when set against this recent performance and business reshaping.
If you want a wider set of ideas built around similar earnings driven stories, a focused stock screen is a useful next step. You can start with 32 high quality undervalued stocks.
Is Sempra Still Cheap on Earnings?
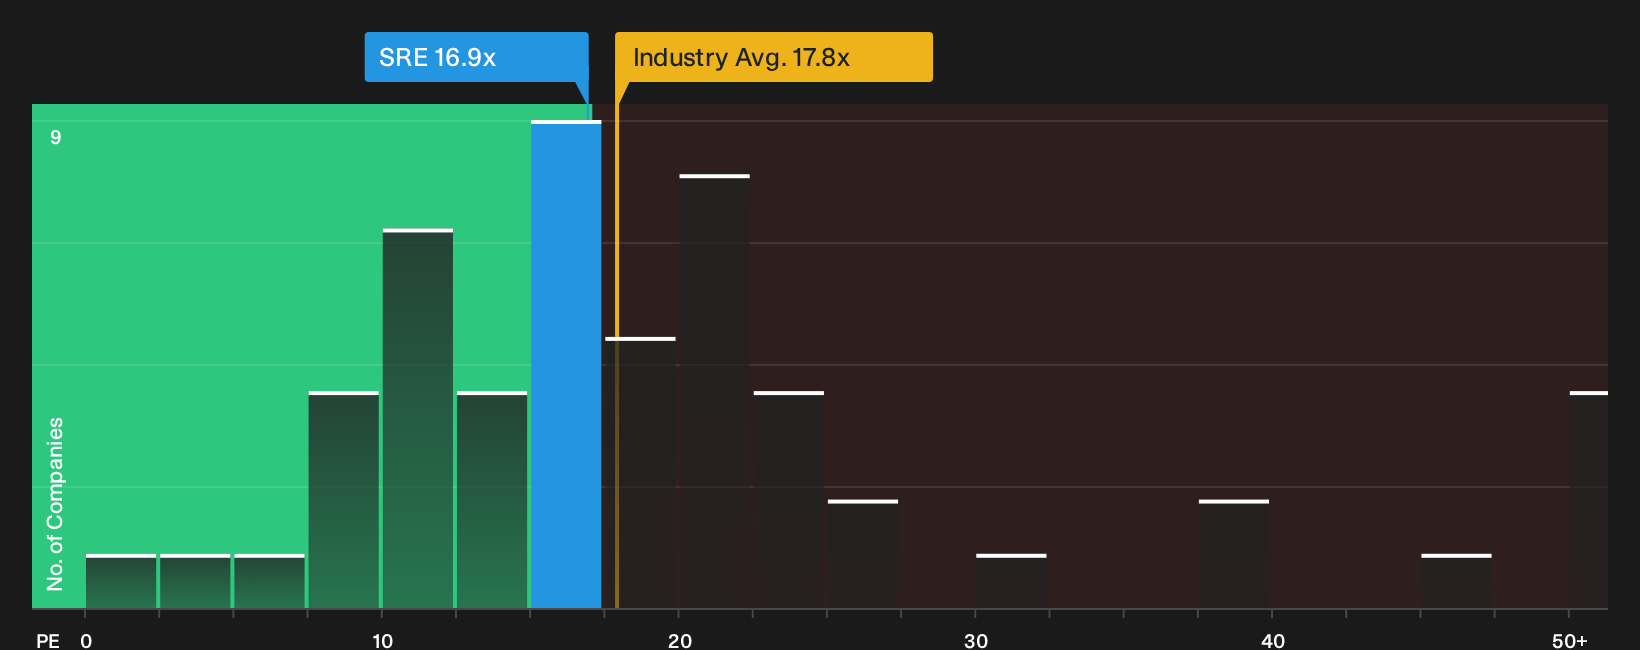
The P/E ratio suits Sempra because earnings are still the main anchor for how investors judge a regulated utility. On this lens, Sempra trades on about 16.9x earnings, which is slightly below the integrated utilities sector on roughly 17.8x and sits at a clearer discount to the broader peer group on around 21.0x. Based on a tailored fair multiple that weighs Sempra's size, risk mix and profitability, the current P/E screens below where you might expect it to trade.
Because Sempra has just increased Oncor's capital plan and reshaped its infrastructure exposure, the lower P/E suggests investors are still pricing in some caution around execution and regulatory risk rather than paying up for the Texas growth story. Despite the strong 2026 earnings report and higher full year guidance, the stock still changes hands at a discount to the peer group on this earnings measure. Explore the numbers behind Sempra's P/E valuation.
The Sempra Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Sempra's P/E puzzle leaves off. They spell out which combinations of future growth, profitability and earnings power would need to play out for the stock to be worth meaningfully more or less than today. Each one turns Sempra's implied fair value into a concrete, testable story about the business that you can revisit over time as new information arrives.
One of the top narratives on Sempra: 20% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The current valuation implies the share price does not fully reflect the capital recycling into regulated U.S. utilities, the multi decade Texas grid capital expenditure runway, and the earnings contribution from contracted LNG projects..."
Discover why this Narrative puts Sempra at 20% undervalued.
Sempra’s share price is only one piece of the decision
Before you lean too hard on valuation alone, it is worth knowing that Simply Wall St’s broader checks have highlighted specific areas of concern that could change how you view Sempra altogether. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com