


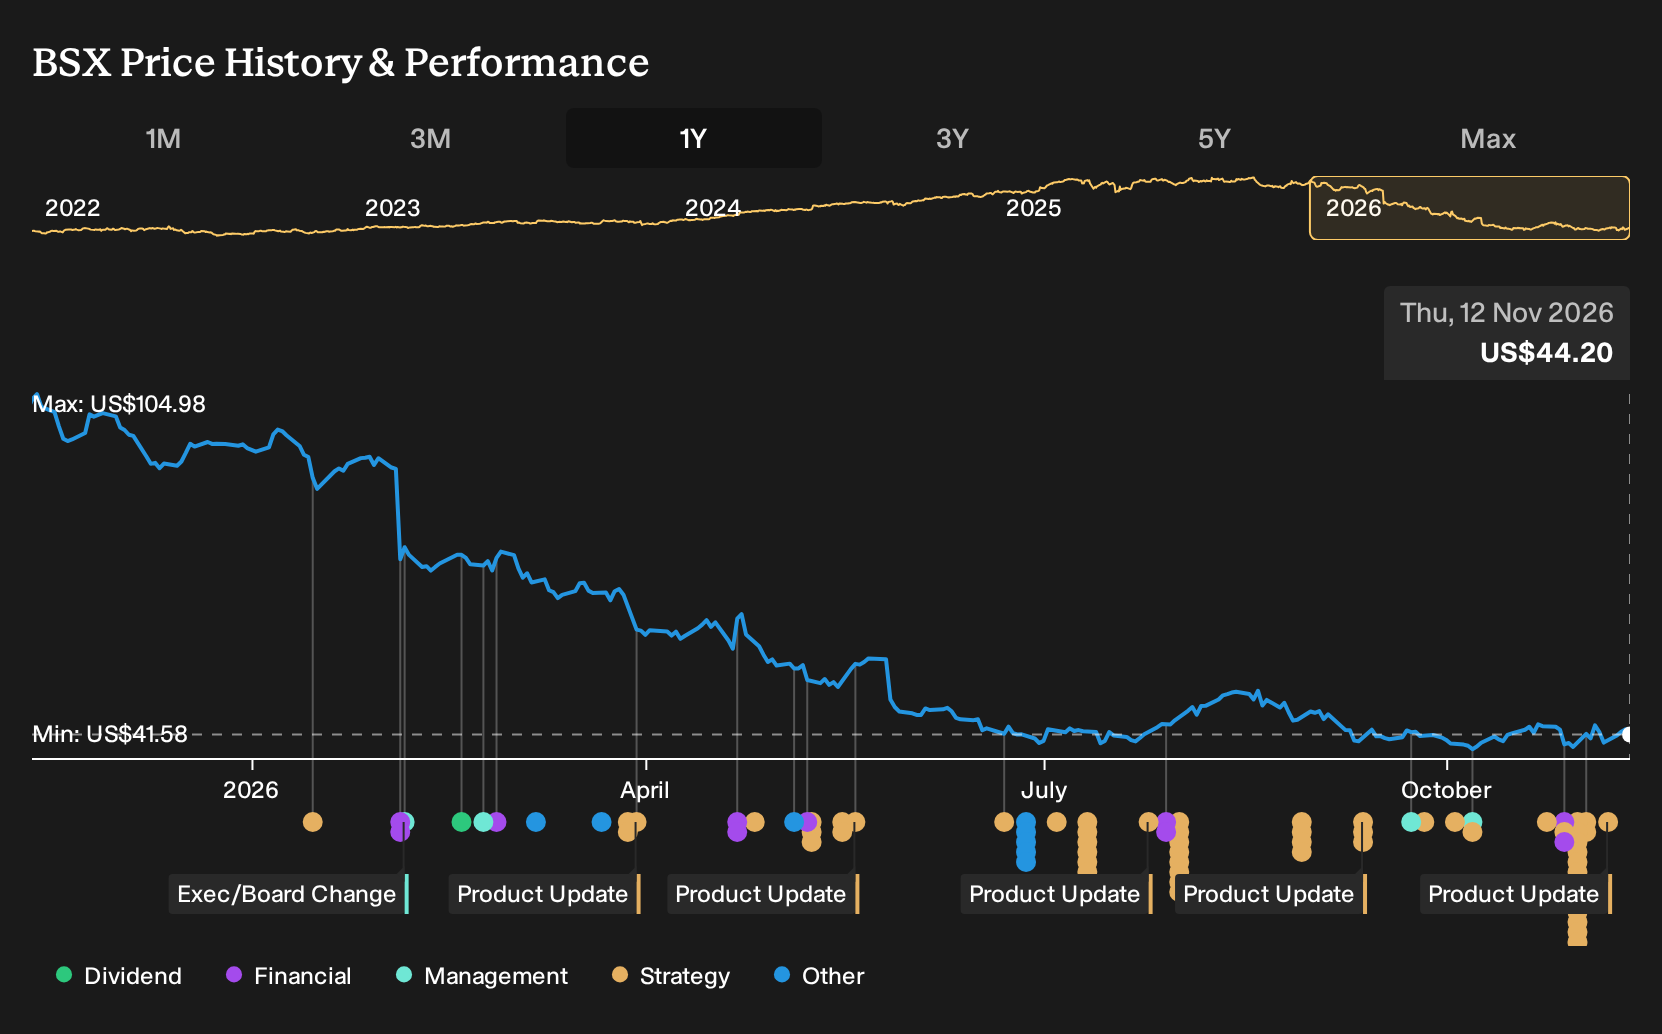
- Boston Scientific has been dealing with a cluster of voluntary Class II recalls in 2026, including firmware issues in a Neuromodulation therapy disc and manufacturing defects in Direxion Torqueable Microcatheters distributed across the US and multiple international markets.
- These quality problems create real business pressure for Boston Scientific, from potential rework and remediation costs to tighter regulatory oversight and possible disruption in key interventional and neuromodulation product lines.
- Next, the focus shifts to how Boston Scientific's investment narrative holds up in light of these recall driven quality control and regulatory questions.
Boston Scientific Investment Narrative Recap
To own Boston Scientific, you need to believe the medtech group can keep using its broad cardiovascular and MedSurg portfolio to offset current weakness in Electrophysiology and WATCHMAN. The analyst consensus narrative on Simply Wall St emphasizes interventional cardiology, restructuring savings and acquisitions such as Penumbra as potential supports for earnings, even as guidance already incorporates softer EP and LAAC trends.
The key near term swing factor is execution on quality and supply. Multiple Class II recalls in Neuromodulation and Direxion microcatheters have increased the risk of added cost, regulatory friction and product disruption. These issues come on top of existing pressures in PFA, WATCHMAN volumes and integration risk related to large deals and restructuring.
The SIMPLAAFY data for the WATCHMAN FLX Pro LAAC device is particularly important at the moment because it relates directly to one of Boston Scientific's weaker lines. Trial results showed that aspirin alone or reduced dose NOAC regimens achieved noninferiority to dual antiplatelet therapy at six months, with similar ischemic stroke rates and less bleeding, while device related thrombus was lowest on reduced dose NOAC.
For investors, this suggests that WATCHMAN still has a clinical narrative that could support volumes if the current flat to declining trends in LAAC stabilise. It does not resolve execution questions around recalls, PFA competition or large deal integration, but it gives the LAAC franchise a clearer evidence base at a time when the analyst consensus narrative on Simply Wall St is focused on future platforms such as WATCHMAN Elite as a potential medium term catalyst.
Boston Scientific's narrative projects US$23.0b revenue and US$4.0b earnings by 2029, based on analysts assuming 2.9% yearly revenue growth and an earnings increase of US$0.5b from US$3.5b today.
Uncover why Boston Scientific's fair value indicates a 12% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Quality risk sits front and center after the Boston Scientific recalls. The most optimistic analysts had been leaning on a cleaner execution story, with Boston Scientific revenue modeled at US$24.4b and earnings at US$4.4b by 2029. You can see how far opinions stretch and decide which version of the story still fits after this news.
Explore 6 other Boston Scientific fair value estimates, including one that suggests potential upside of up to 124% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Boston Scientific research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Boston Scientific. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Boston Scientific's overall financial health at a glance.
Looking for more Boston Scientific style investment ideas?
If Boston Scientific no longer feels like the only story worth your time, it may be a good moment to widen the lens. You can use the Simply Wall St Screener to look for other businesses that align with your risk tolerance, income needs, or preference for cleaner balance sheets.
- For investors who are interested in potential value supported by business quality, scan our 32 high quality undervalued stocks and see which companies combine fundamentals with a discounted price tag.
- If capital preservation and a smoother ride matter most to you, filter the market using the 29 resilient stocks with low risk scores to focus on businesses with more resilient profiles.
- When you are ready to go beyond the usual blue chips and explore fresher stories, check out the 20 high quality undiscovered gems that pair solid numbers with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com