


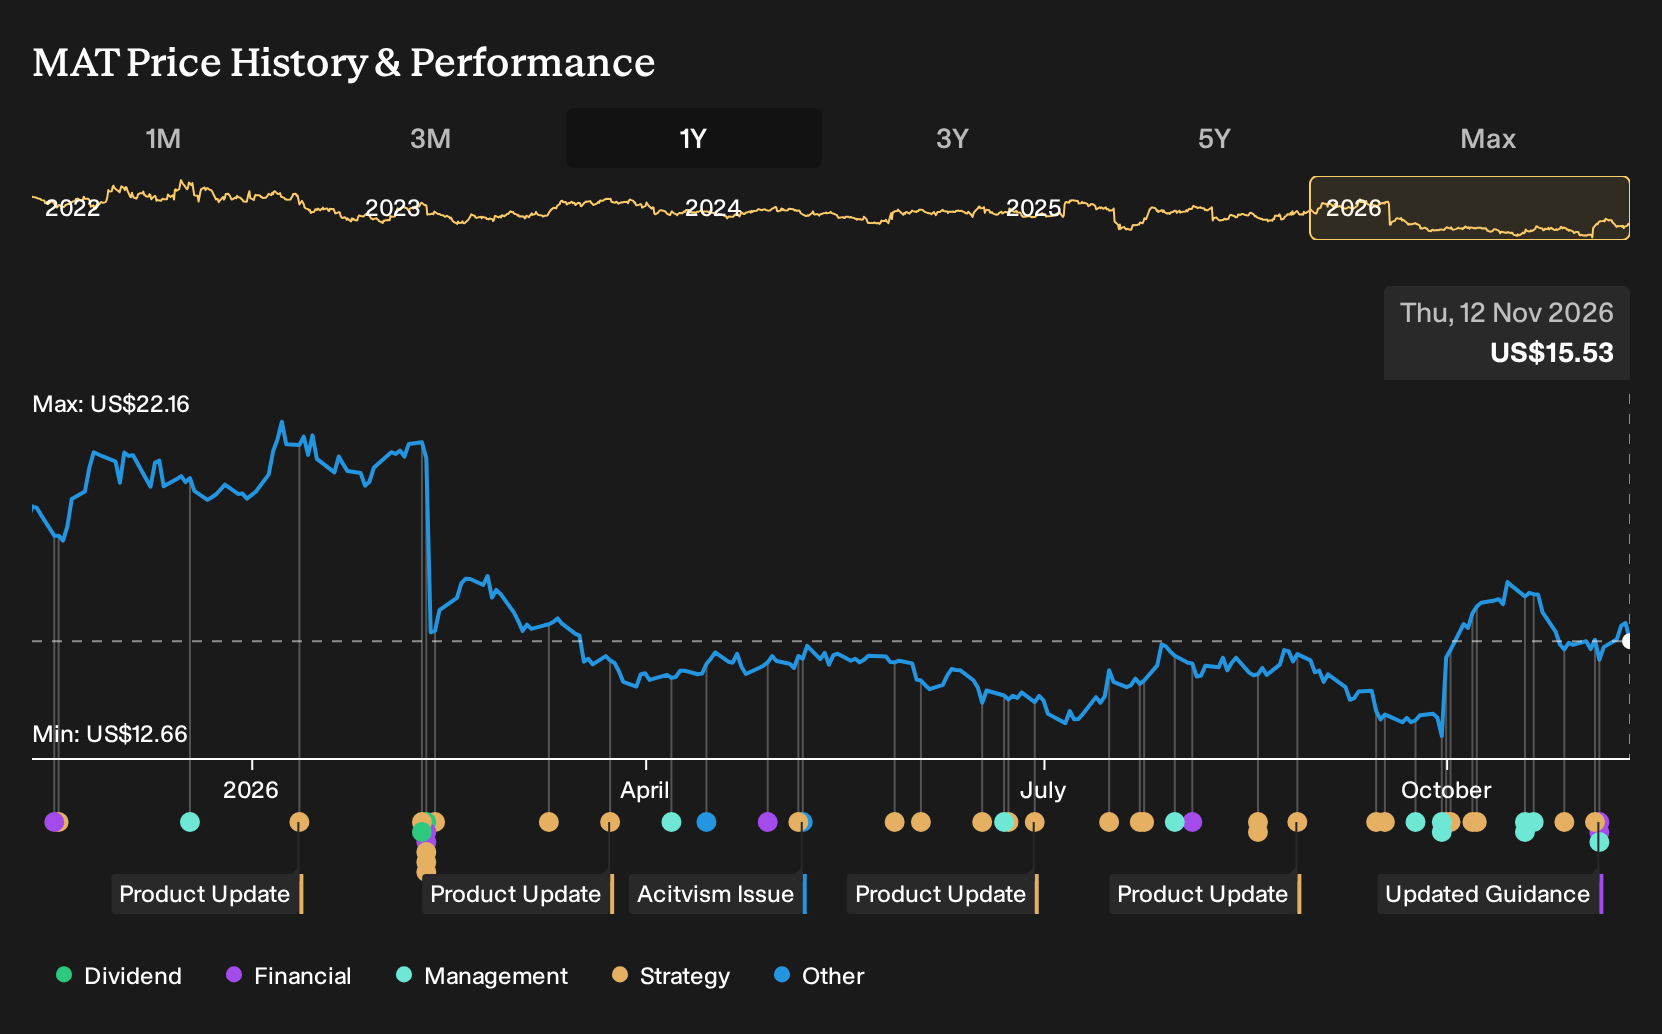
- Mattel reported third quarter 2026 sales of US$1,806.7 million and net income of US$353.6 million, updated full year guidance to 1% to 4% constant currency net sales growth, announced leadership changes including Steve Totzke as President and COO, and detailed ongoing share repurchases and new Hot Wheels brick products.
- The mix of higher earnings, tighter share count from buybacks, and expanded Hot Wheels offerings highlights how Mattel is leaning into brand driven, higher margin product ecosystems across both traditional toys and buildable collectibles.
- We will now look at how Mattel's stronger earnings guidance could influence the broader investment narrative around its IP led model.
Mattel Investment Narrative Recap
To own Mattel, you need to believe in its IP led toy and entertainment model and the ability to keep turning brands like Barbie and Hot Wheels into higher margin ecosystems across toys, digital and content. The analyst consensus Narrative on Simply Wall St assumes modest revenue growth and declining earnings over the next few years, so execution on profitability remains central.
The refreshed 1% to 4% constant currency net sales outlook and stronger recent earnings keep the near term focus on whether margin work and brand extensions can offset risks around film linked demand, collector fatigue and higher input costs. If those pressures intensify, the current IP centric thesis could look more fragile.
The appointment of Steve Totzke as President and COO looks most relevant here because it directly connects to how Mattel runs its brand portfolio and commercial engine. He now oversees global brands, sales and consumer products, which are exactly the areas that need tight coordination for an IP driven model to work efficiently.
Totzke’s long tenure in commercial roles and involvement in Mattel’s brand centric operating model should help with execution on the catalysts analysts are watching, from adult collectors to digital games and entertainment tie ins. The key risk is that any missteps in aligning product, marketing and licensing with uneven box office or changing gamer habits could make those same growth pillars more volatile.
Analysts currently model Mattel reaching US$6.2b in revenue and US$463.7 million in earnings by 2029. This sits against an assumed 4.0% yearly revenue growth rate and an earnings increase of about US$36 million from the US$427.4 million reported today.
Uncover why Mattel's fair value indicates a 17% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
One more bullish angle you may want to test is the idea that Mattel’s 2026 “investment year” pays off faster under Steve Totzke. The most optimistic analysts were already pencilling in US$6.5b of revenue and US$505.2 million of earnings by 2029. Those projections were set before this leadership shift and the updated guidance, so opinions may move again.
Explore 3 other Mattel fair value estimates, including one that suggests potential upside of up to 71% from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Mattel research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Mattel. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mattel's overall financial health at a glance.
Looking for more ideas beyond Mattel?
If Mattel's mix of brands, IP and cash generation has your attention, it can be useful to compare it with other businesses that match different risk and return profiles using the Simply Wall St Screener.
- For investors who want quality and value in the same place, consider reviewing a curated 32 high quality undervalued stocks that pair solid fundamentals with attractive pricing.
- If income stability is a priority, you might prefer companies in our selection of 6 dividend fortresses that focus on robust payouts supported by their underlying cash flows.
- For those hunting for less followed opportunities, you could scan a focused group of 20 high quality undiscovered gems that combine strong fundamentals with lighter market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com