


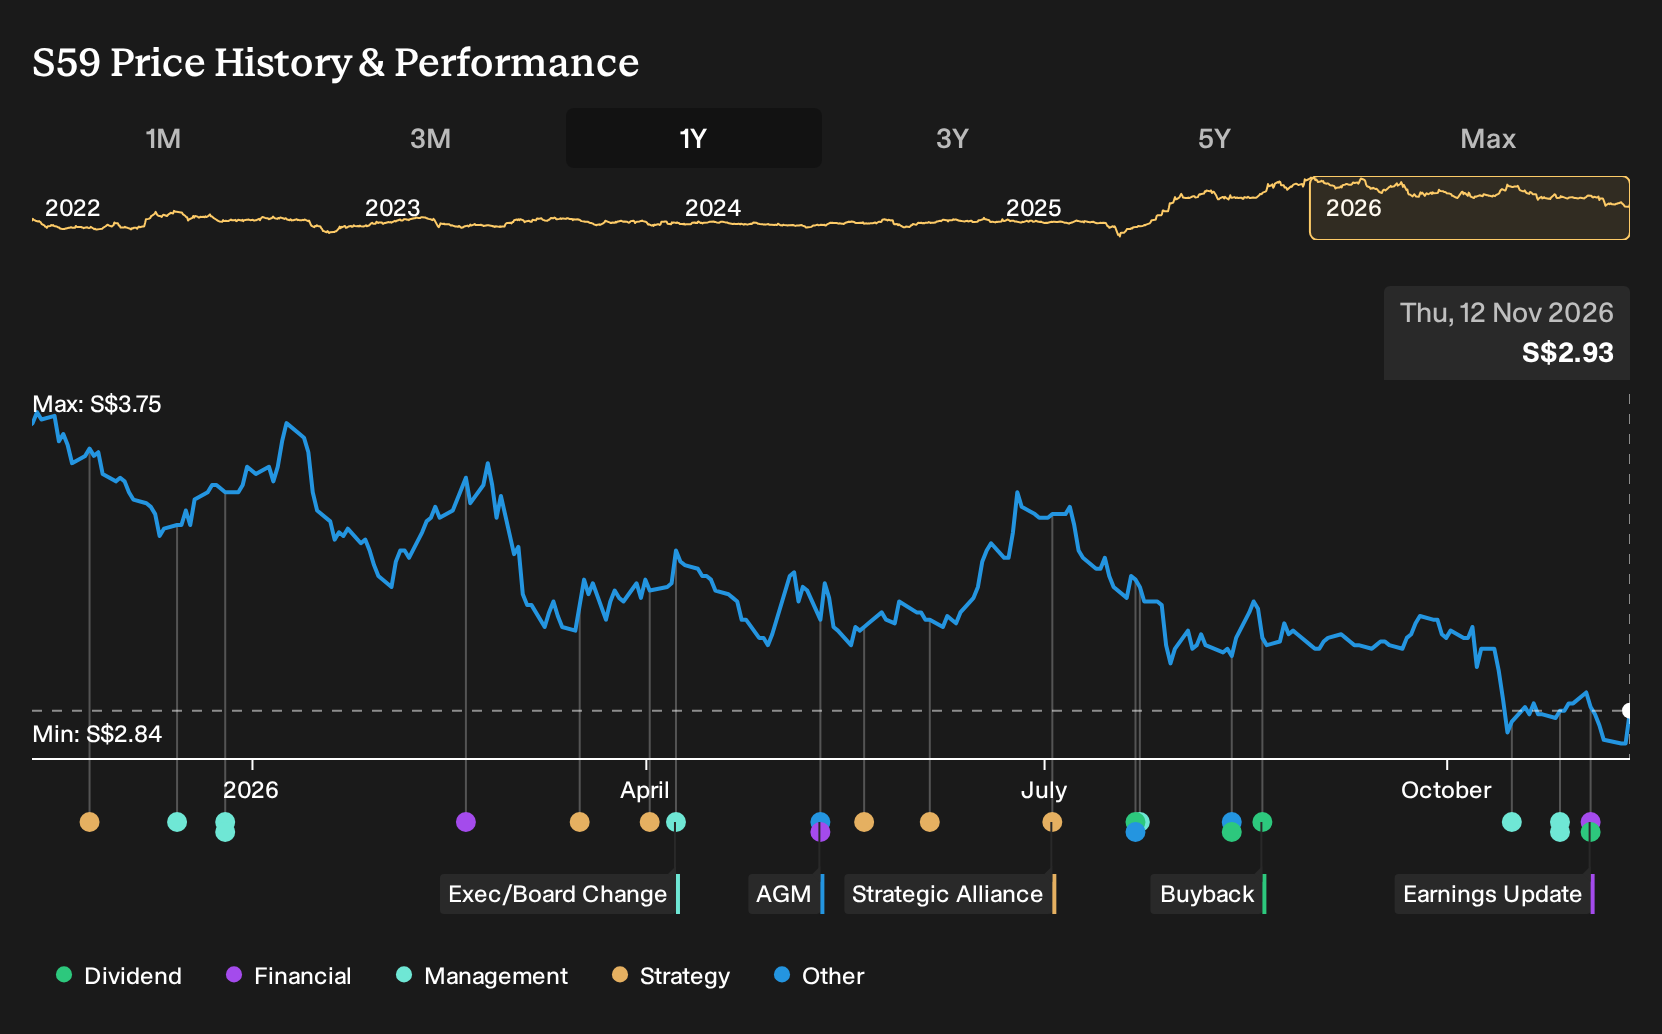
- SIA Engineering reported H1 2027 results for the half year ended 30 September 2026, with sales of SGD 658.58 million and net income of SGD 81.93 million, alongside an interim tax exempt dividend of 2.5 cents per share to be paid on 27 November 2026.
- The combination of softer first half sales and net profit, together with SIA Engineering maintaining its interim dividend, highlights management’s focus on balancing current operating pressures with a consistent capital return approach.
- The focus will now be on how SIA Engineering's softer half year revenue, alongside a maintained interim dividend, shapes the broader investment narrative.
What Is SIA Engineering's Investment Narrative?
SIA Engineering appeals most if you believe in a long, steady need for outsourced aircraft maintenance, supported by its network across Asia and the US and a customer base tied to global carriers. The latest half year figures show softer sales and earnings, yet management still kept the 2.5 cent interim dividend. That mix suggests the business is prioritising continuity in shareholder payouts while working through near term volume or pricing pressure rather than resetting its whole playbook.
In the short term, the key swing factors are execution on high quality, high margin work and how quickly demand for heavy checks and component overhaul stabilises after this softer first half. Earnings forecasts still point to growth, but returns on equity are described as low and the P/E is higher than both peer and sector averages, so you rely on solid operations and disciplined capital use more than on a bargain entry point.
That said, beneath the steady dividend story, there is a pressure point around ...
There's only one way to know the right time to buy, sell or hold SIA Engineering. Head to Simply Wall St's company report for the latest analysis of SIA Engineering's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between SGD 3.04 and SGD 3.72, which already shows how far apart private investors can be on SIA Engineering. These views were formed before the H1 2027 earnings call and dividend affirmation, so use them as a starting point and explore more recent viewpoints.
Explore another SIA Engineering fair value estimate, including one that indicates up to 27% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your SIA Engineering research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for SIA Engineering. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SIA Engineering's overall financial health at a glance.
Looking For More Ideas Beyond SIA Engineering?
If you want to test your thesis on SIA Engineering against other opportunities, the Simply Wall St Screener lets you line up different income and quality profiles side by side instead of viewing this stock in isolation.
- If capital protection comes first for you, start with a basket of resilient companies using the 205 resilient stocks with low risk scores and see how their risk profile compares with SIA Engineering.
- If you prefer to hunt for quality at a reasonable price, line up a group of potentially mispriced opportunities through the 194 high quality undervalued stocks and weigh their fundamentals against this stock.
- If balance sheet strength is non negotiable in your process, filter for financially robust businesses via the list of solid balance sheet and fundamentals (200 results) and test how SIA Engineering stacks up on debt and liquidity.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com