


Clorox (CLX) just posted first quarter results that put fresh numbers behind the recent move in the stock, with sales of US$1,905 million and net income of US$170 million catching investor attention.
That earnings release comes on top of a sharp swing in sentiment, with Clorox’s share price up 27.34% over the past month and 8.24% over the last week, while the 1-year total shareholder return of 9.66% contrasts with a declining 3-year total shareholder return of 12.39%, which suggests that recent momentum is building after a tougher multi-year stretch.
See how Clorox’s earnings-driven move compares with other consumer stocks showing fresh momentum in our curated list of 32 high quality undervalued stocks.
Bulls see a household staple regaining its footing after Clorox’s sharp rebound and stronger quarterly numbers. Skeptics see a short burst of optimism. Which side does the valuation lean toward next?
Most Popular Narrative: 11% Overvalued
Clorox closed at $108.20, while the analyst consensus Narrative on Simply Wall St points to a fair value of $97.47 using a 7.24% discount rate. That gap frames the current rally as richer than the Narrative’s implied entry point and sets up a clear clash between recent price action and modeled fundamentals.
The current valuation implies investors are pricing Clorox as if margin pressure, muted category growth, and legal or governance overhangs will weigh more heavily on the share price than the potential upside from health and hygiene growth, ERP driven productivity, and GOJO accretion.
See why 49 investors see Clorox as 11% overvalued.
Result: Fair Value of $97.47 (OVERVALUED)
Still, higher input and logistics costs guided at slightly over US$200 million in fiscal 2027, along with an elevated 85% to 90% dividend payout ratio, could strain Clorox’s flexibility and upset this recovery story.
Find out about the key risks to this Clorox narrative.
Another View: Cash Flows Point a Different Way
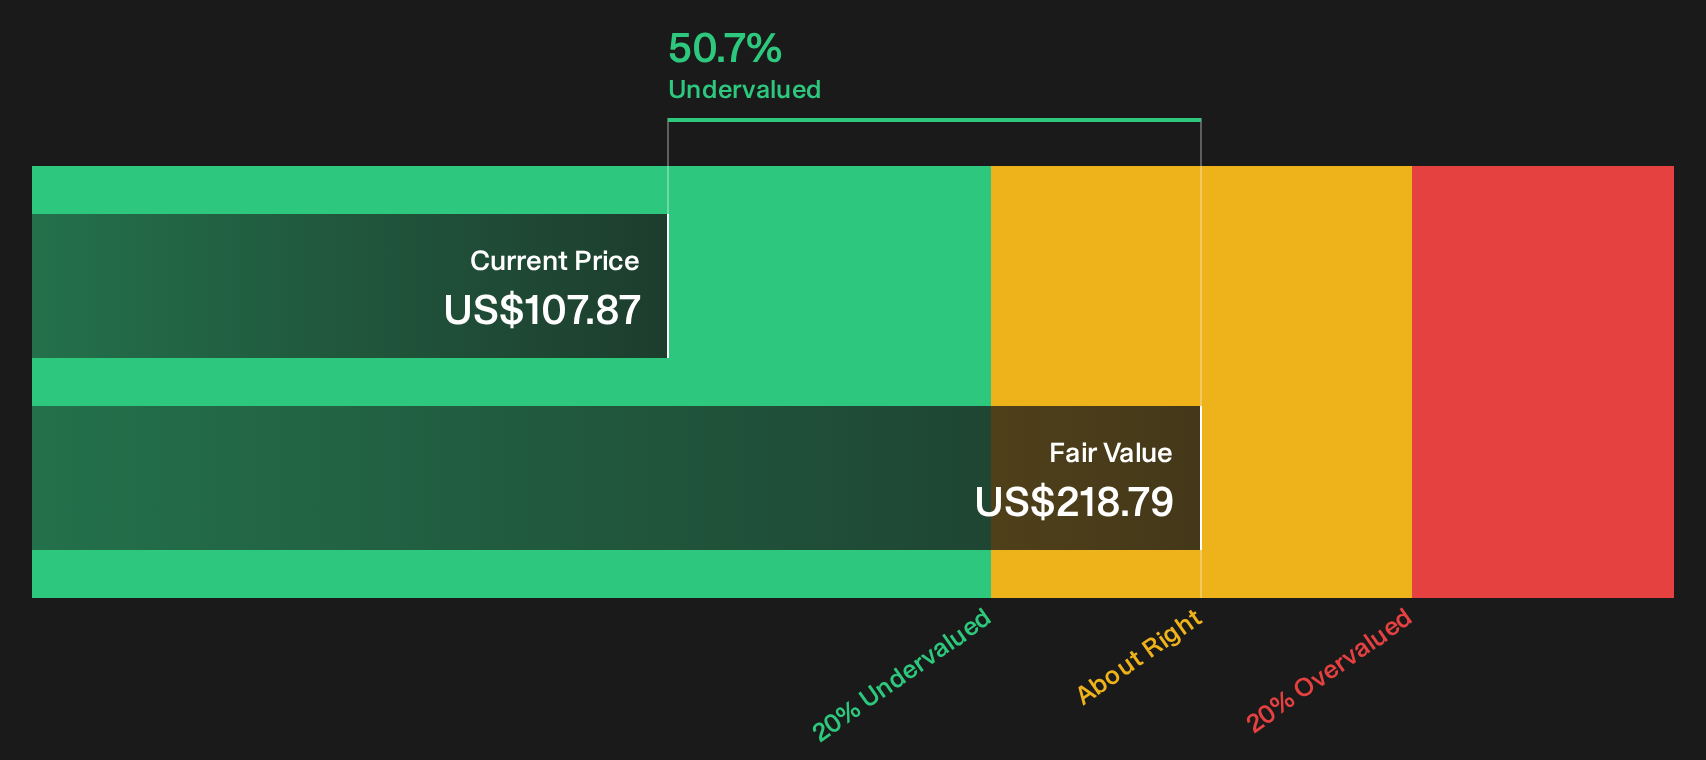
While the Simply Wall St Narrative tags Clorox as 11% overvalued at a fair value of $97.47, the SWS DCF model paints a very different picture. On that framework, the stock at $108.20 trades at roughly a 50% discount to an estimated future cash flow value of $218.79, which raises a simple question for investors: Which signal should carry more weight, earnings based targets or cash flow math?
Look into how the SWS DCF model arrives at its fair value.Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment on Clorox is clearly split, which is exactly why it makes sense to run the numbers yourself and see which narrative feels more convincing. If you want a fast way to weigh both concerns and potential upside in one place, start with the 2 key rewards and 2 important warning signs.
Looking for more ideas beyond Clorox?
Do not stop at Clorox. The fastest way to pressure test your thinking is to compare it with fresh opportunities built from the same hard numbers.
- Target resilient income by reviewing companies that show up as 6 dividend fortresses and see which ones align with your cash flow goals.
- Hunt for potential mispriced opportunities using 20 high quality undiscovered gems and compare their fundamentals with what you see in Clorox today.
- Anchor your portfolio around balance sheet strength by scanning list of solid balance sheet and fundamentals (23 results) and identifying businesses that may ride out tough conditions more comfortably.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com