


Ollie's Bargain Outlet Holdings (OLLI) is back in focus after both KeyBanc Capital Markets and Argus raised their expectations for the retailer, highlighting fresh views on valuation and cash generation.
Recent trading tells a mixed story. The share price is around $94.77 after a 30 day share price return of 7.29% and a 90 day gain of 23.90%. However, the year to date share price return is down 14.87% and the 1 year total shareholder return has declined 24.98%, even as Ollie’s Bargain Outlet Holdings reports a 22.09% total shareholder return over three years and 40.69% over five years, which indicates a contrast between shorter-term performance and longer-term results.
Compare Ollie's Bargain Outlet Holdings with other retailers that screen for resilient fundamentals and potential mispricing by scanning the hand picked 32 high quality undervalued stocks list before making your next move.
Bulls point to Ollie’s Bargain Outlet Holdings’ cash generation story and buyback firepower, while bears focus on the recent drawdown. Which case lines up better with what the current valuation actually implies?
Most Popular Narrative: 4.1% Undervalued
Ollie's Bargain Outlet Holdings last closed at $94.77 against a narrative fair value of $98.78, a small gap that still shapes how some investors read the recent pullback versus the longer record of returns.
The dominant narrative architecture of the September call is trifurcation: weather, consumer pressure, and a promotional environment presented simultaneously as three separable but overlapping headwinds, any one of which is described as "transitory" and none of which management claims to parse with precision. This structure is defensible, Rob Helm said plainly, "it''s hard for us to parse out how much of that was weather versus promotional environment versus state of the consumer", but it also immunizes the narrative against accountability for any single factor.
See why 2 investors see Ollie's Bargain Outlet Holdings as 4% undervalued.
Result: Fair Value of $98.78 (UNDERVALUED)
Still, this undervaluation story can break if tariff refunds remain a one off support for margins, or if heavier price investment compresses Ollie's Bargain Outlet Holdings profitability.
Find out about the key risks to this Ollie's Bargain Outlet Holdings narrative.
Another View: Multiples Push Back On The Ollie's Bargain Outlet Story
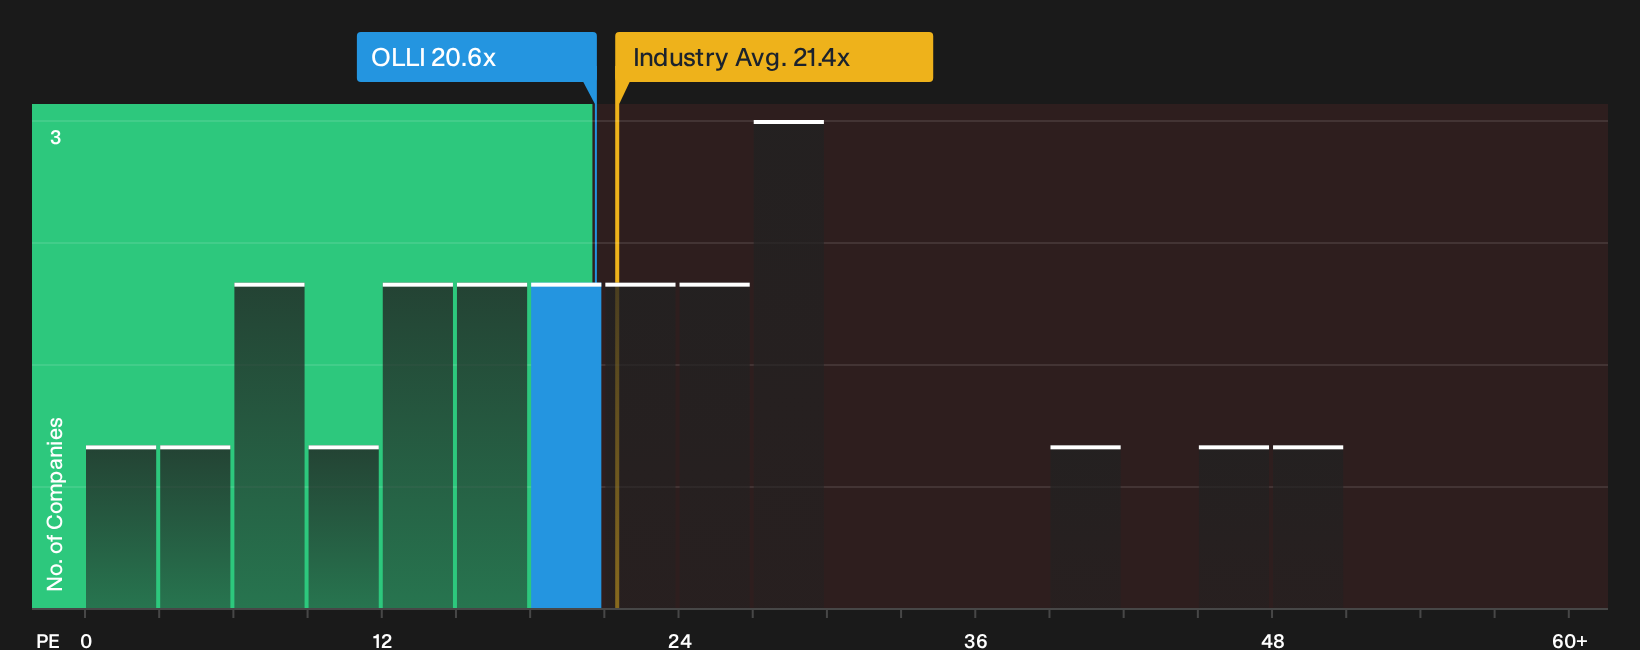
There is a catch. While that $98.78 fair value suggests Ollie's Bargain Outlet Holdings looks 4.1% undervalued, the market is paying a P/E of 20.6x against an estimated fair ratio of 14.6x and a peer average of 19.5x. That gap points to less room for error than the headline discount implies, so which signal should be treated as more important?
For a closer look at how this pricing stacks up on earnings alone, including the comparison to industry averages and the fair ratio the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Ollie's Bargain Outlet Holdings often spark debate, so treat this as a starting point and move fast to test the numbers against your own framework by checking the 3 key rewards.
Looking for more investment ideas beyond Ollie's Bargain Outlet Holdings?
If you stop with Ollie's Bargain Outlet Holdings, you risk missing other opportunities that might fit your goals even better, so keep widening your opportunity set.
- Target steadier compounding by reviewing companies screened for resilience and potential mispricing through the 32 high quality undervalued stocks.
- Prioritise strength under stress and see which businesses pass the balance sheet health checks inside the list of solid balance sheet and fundamentals (23 results).
- Hunt for underfollowed stories with solid fundamentals by checking the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com