


- agilon health reported third quarter 2026 revenue of US$1,519.49 million and net income of US$34.91 million, with basic earnings per share of US$2.08 after a loss in the prior year period.
- Across the first nine months of 2026, agilon health moved from a net loss to net income of US$101.78 million and raised full year revenue guidance to a range of US$5,870 million to US$5,890 million, which reflects management’s current view on demand and cost control.
- We will now look at how agilon health’s shift to profitability and higher revenue guidance could influence the broader investment narrative.
agilon health Investment Narrative Recap
To own agilon health, an investor needs to believe the firm can keep turning its value based primary care model into durable profits, not just one strong quarter. The recent swing to quarterly and year to date net income supports that story. The key short term catalyst remains execution on medical cost control while operating within tighter contracts and exited markets.
The biggest risk is still membership pressure in Medicare Advantage. If covered lives remain soft, higher revenue guidance alone may not offset the drag on operating leverage. These results help, but they do not remove concerns about slower customer growth or past cash burn raised in the analyst consensus Narrative on Simply Wall St.
The raised full year revenue outlook to US$5,870 million to US$5,890 million is the announcement that really matters here. It ties directly to whether agilon health can lean on its data pipeline, AI supported risk adjustment and clinical pathways to keep medical costs in line while staying disciplined on contracts.
This guidance range also tests the core catalysts that analysts focus on, such as expanding ACO programs and profitability focused growth. If the business hits its revenue range while keeping quality scores and medical margins within prior commentary, it strengthens the case that the platform can support a more stable earnings profile over time.
What The agilon health Forecasts Assume
agilon health's narrative projects revenues of US$7.4b and earnings of US$77.9 million by 2029. That profile is built on analysts assuming revenue grows at about 7.6% a year, and earnings move from a loss of US$251.2 million today to a gain of US$77.9 million, which is roughly a 2x swing in absolute profit compared with the size of the current loss.
Uncover why agilon health's fair value indicates a 5% potential upside to its current price, which could narrow quickly.
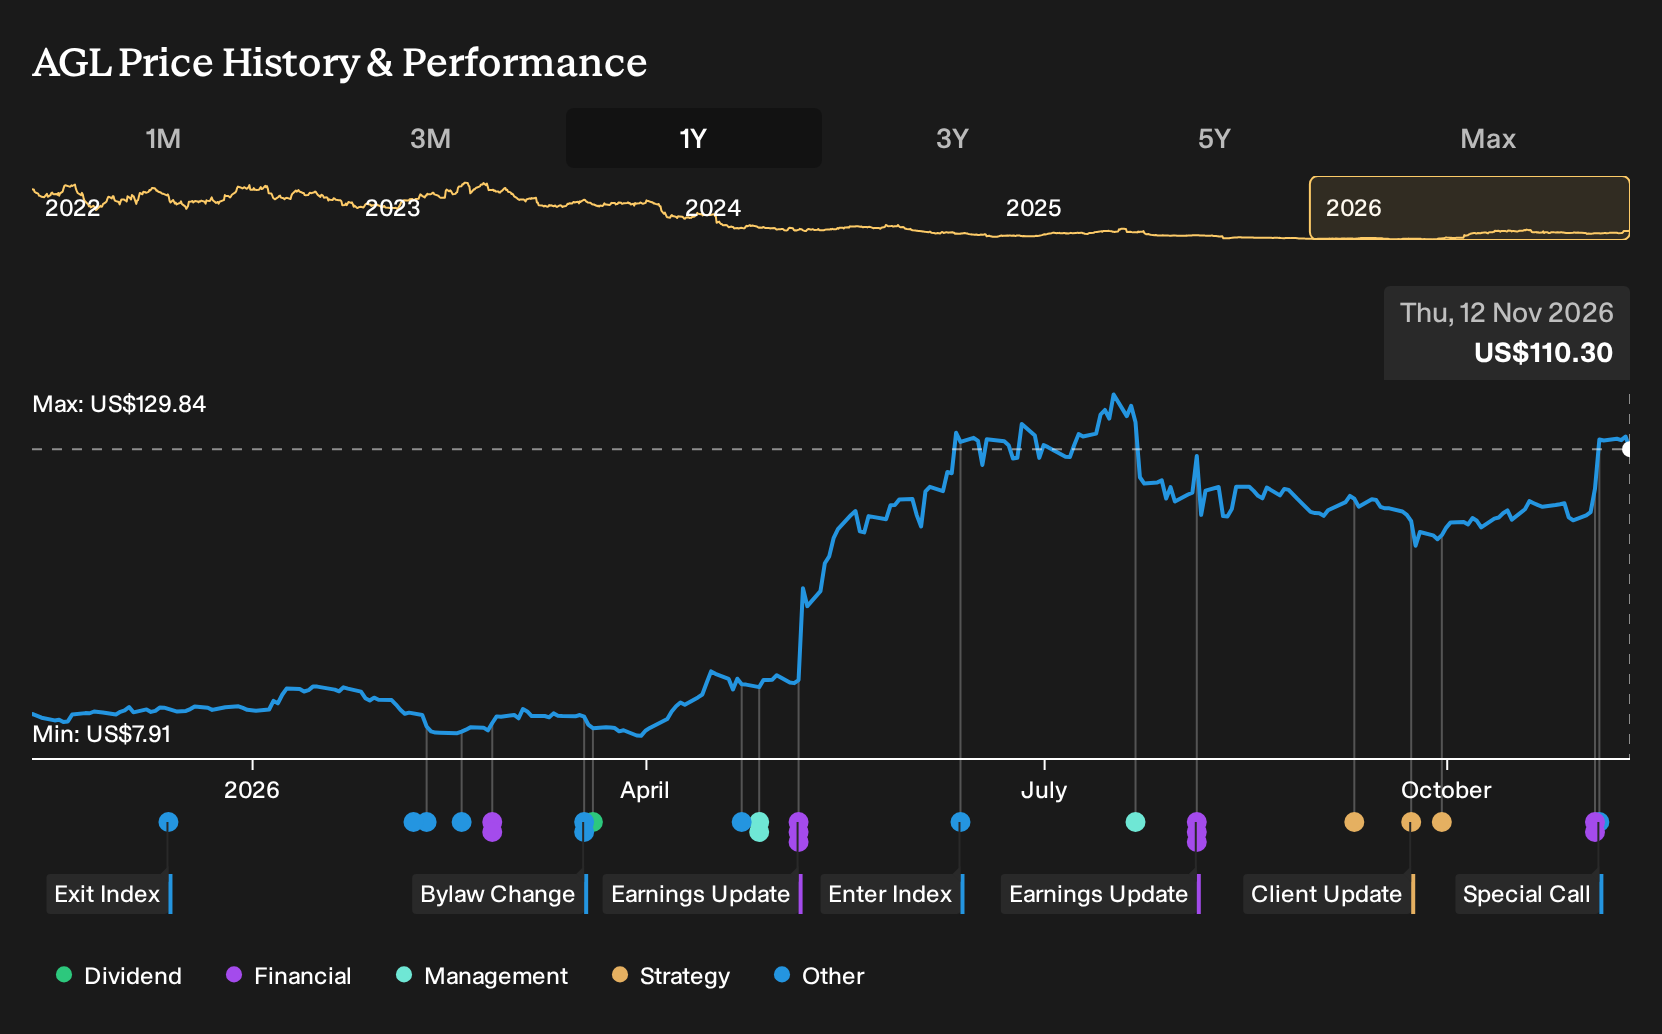
Exploring Other Perspectives
Some of the lowest agilon health forecasts leaned hard into the risk that Medicare Advantage membership keeps slipping, which they saw as a ceiling on future earnings. Those analysts were only penciling in about US$7.0b of revenue and US$14.0 million of profit by 2029. Today’s stronger results could challenge that view, so explore both narratives before deciding what you think.
Explore 2 other agilon health fair value estimates, including one that suggests it could be worth just $115.83.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your agilon health research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for agilon health. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate agilon health's overall financial health at a glance.
Looking for more investment ideas beyond agilon health?
Once you have a view on agilon health, it can help to compare that thesis with other opportunities that match your preferred mix of quality, risk and income. The Simply Wall St Screener lets you filter for exactly the traits you care about, so you can build a watchlist that suits how you like to invest.
- For investors who care most about financial resilience, start with a list of solid balance sheet and fundamentals (23 results) that can handle tougher operating conditions without stretching their finances.
- If you want long term compounding potential at reasonable prices, focus on 32 high quality undervalued stocks that pair quality fundamentals with what our models view as discounted market expectations.
- Income focused investors can zero in on companies with meaningful yields by screening for 6 dividend fortresses that combine regular payouts with underlying business strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com