


Texas Pacific Land has put up a mixed share price record, with a strong longer term gain sitting alongside more recent weakness, which naturally puts the focus on what investors are paying for its earnings today. With fresh headlines around record results and activity in the Permian Basin, the open question is how well the current valuation lines up with the profit stream the business is generating.
- Over the past 5 years, Texas Pacific Land has returned 109.8%. Anyone looking at the stock now is effectively asking how much of that performance was backed by earnings strength that can justify today's multiple.
- Recent record results driven by oil and gas royalties, pipeline easements and water operations can support higher expectations for profit quality and cash generation. That feeds directly into how much investors may be willing to pay per dollar of earnings.
- Your read on Texas Pacific Land is one view; the desks covering it have another. See what analysts think Texas Pacific Land's shares could be worth.
The issue now is whether the current Texas Pacific Land share price is reasonable when judged against the earnings power the business is producing.
Record earnings stories like Texas Pacific Land's can raise the bar for expectations, so it often helps to compare it with a focused list of 32 high quality undervalued stocks.
Has Texas Pacific Land Run Too Far on Earnings?
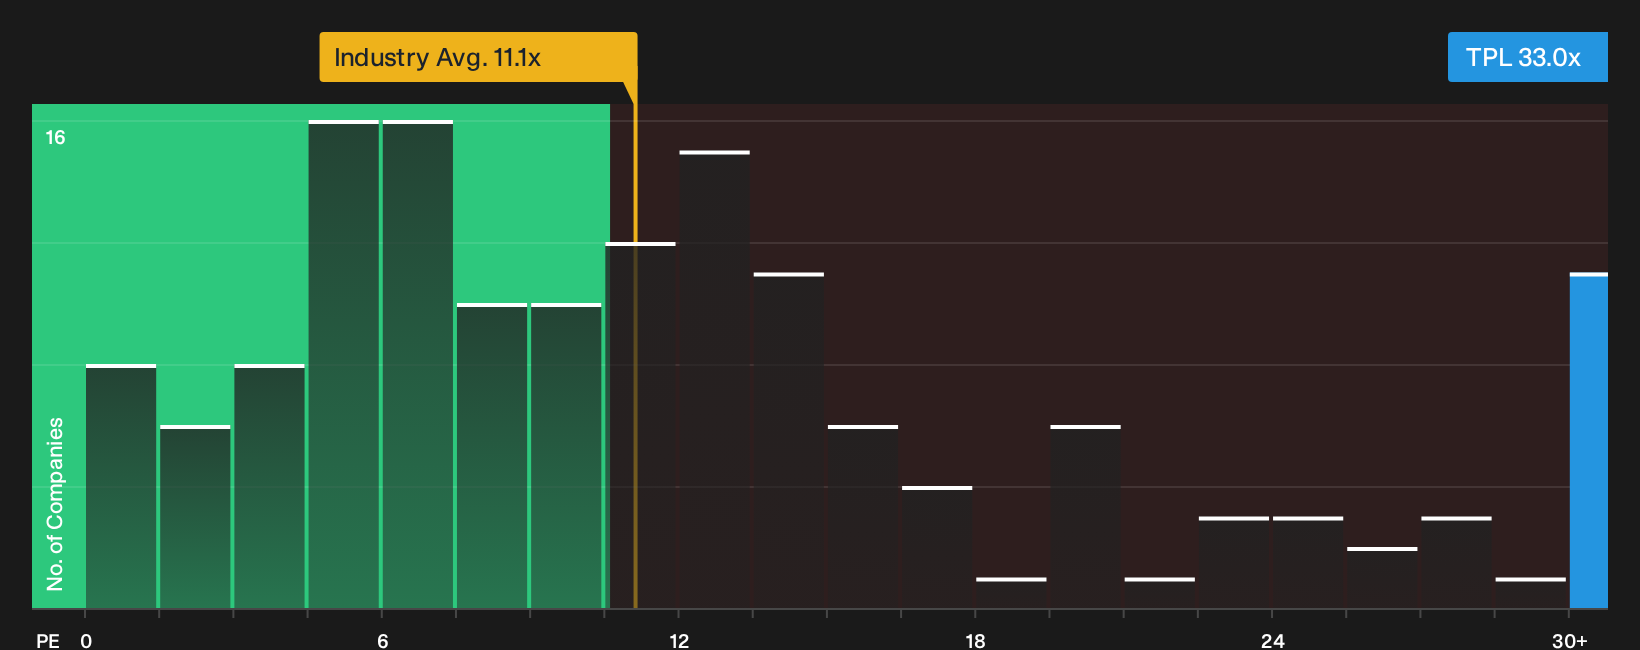
For a royalty heavy operation like Texas Pacific Land, earnings often give a cleaner read on value than revenue or book value. The stock currently trades on a P/E of 33.0x, compared with an Oil and Gas industry average of about 11.1x and a peer group closer to 10.1x. That is a substantial premium to both the sector and similar businesses that investors would need to justify through the perceived quality and durability of Texas Pacific Land’s income stream.
The in house fair multiple, which blends the firm’s growth profile, margins, sector and risk characteristics, sits below the present 33.0x level, so the shares screen as overvalued on this framework. Despite record Q3 2026 earnings helped by strong Permian Basin activity and elevated oil prices, the current valuation already prices in a lot of that strength. Anyone considering Texas Pacific Land needs to weigh how comfortable they are paying this kind of earnings multiple for a business tied to commodity driven cash flows. Explore the numbers behind Texas Pacific Land's P/E valuation.
The Texas Pacific Land Narrative: What Would Justify Today's Price?
Texas Pacific Land’s rich P/E raises a simple question that Narratives try to answer in a structured way. Narratives on Simply Wall St’s Community page spell out which earnings, margin and growth paths would need to hold for the valuation to look much higher or lower than today’s level. Each one lays out the key drivers behind its view of fair value so you can compare those assumptions with Texas Pacific Land’s actual results as they arrive.
Bull and bear views on Texas Pacific Land are far apart, with one Narrative seeing upside and the other arguing expectations already look rich.
Bull case: 37% undervalued
This view comes from the analyst consensus Narrative on Simply Wall St, which aggregates mainstream forecasts and expectations.
"The main thing that has to go right is that Texas Pacific Land turns its strong surface, water and produced water position into durable earnings from infrastructure, desalination and power or data center uses..."
Discover why this Narrative puts Texas Pacific Land at 37% undervalued.
Bear case: 14% overvalued
This angle is drawn from the bearish analyst Narrative on Simply Wall St, which leans on the most cautious published assumptions.
"The numbers and recent research cuts to price targets into the US$360s, along with commentary that the stock appears expensive, imply a share price that already incorporates very optimistic assumptions for Texas Pacific Land and leaves limited room for disappointment..."
Explore why this Narrative puts Texas Pacific Land at 14% overvalued.
One more Texas Pacific Land check that sits beyond the current P/E debate
Before moving on, it helps to ask who is steering Texas Pacific Land, how they are rewarded for key decisions, and whether those incentives line up with your own goals. See who runs Texas Pacific Land and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com