


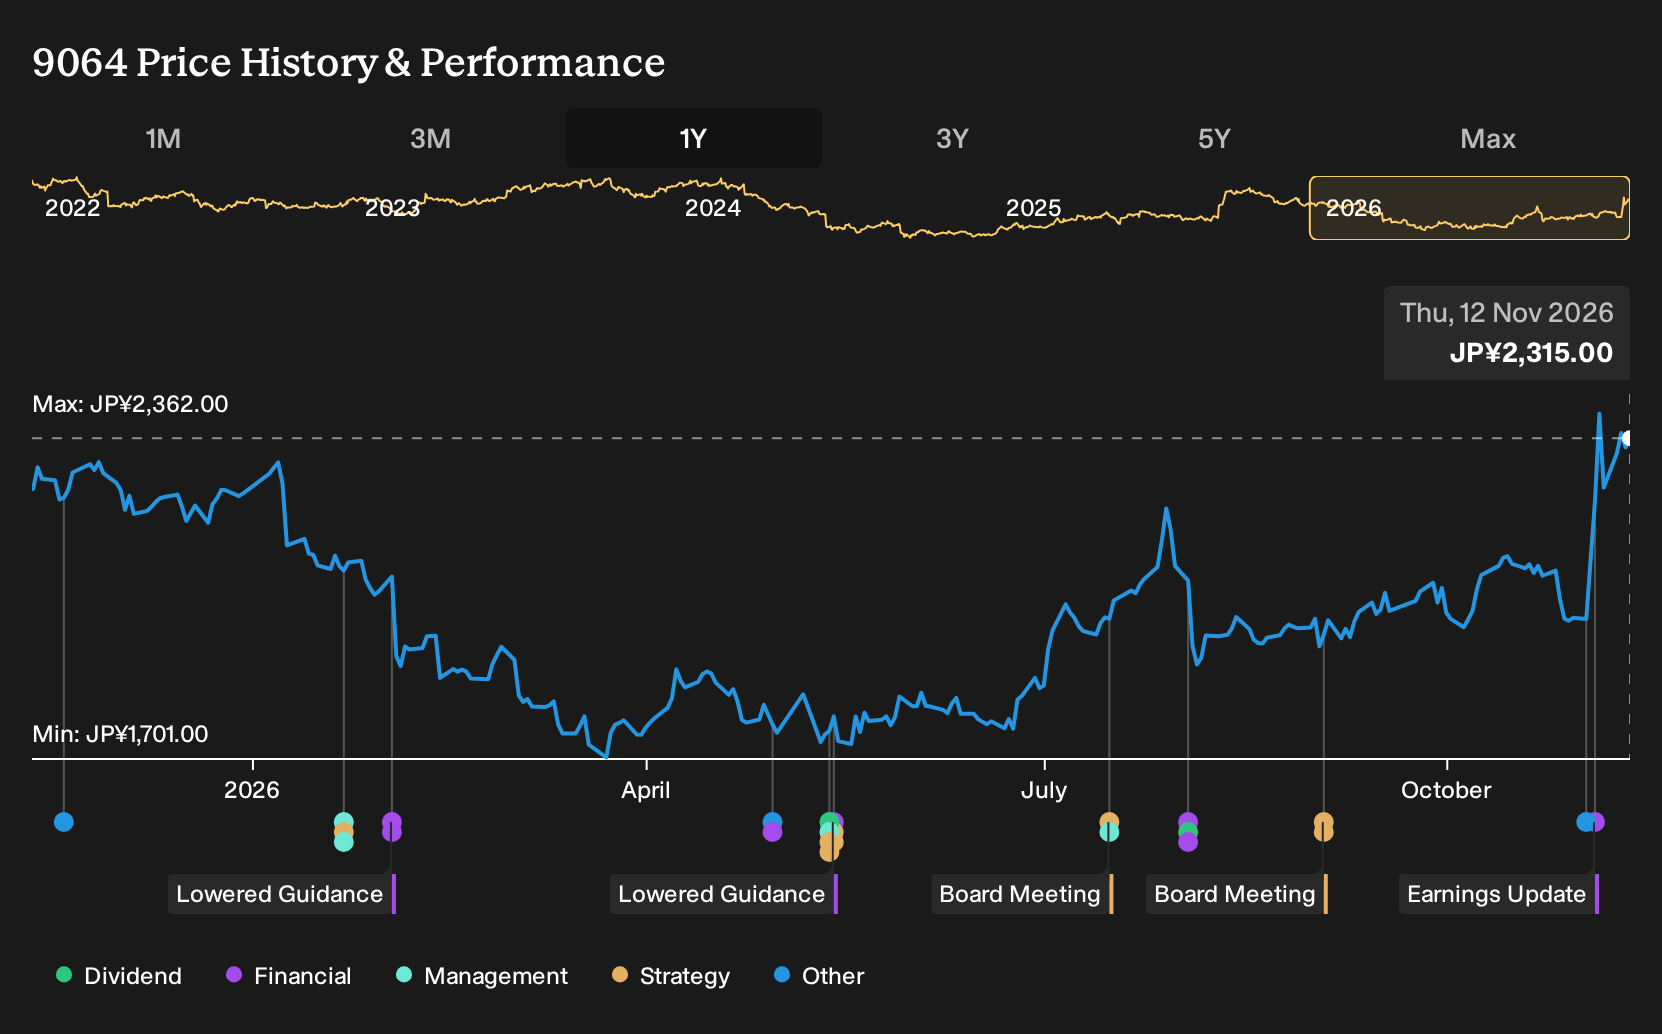
- Yamato Holdings reported half year results for the period ended September 30, 2026, with sales of ¥906,854 million and a deeper net loss of ¥10,562 million, while activist investor Farallon Capital disclosed a 5.02% stake and publicly called for leadership and board structure changes.
- The combination of persistent losses and Farallon Capital’s push for a monitoring-style board indicates pressure on Yamato Holdings to tighten governance around profitability, capital allocation, and day to day execution in its core delivery operations.
- The focus will now be on how Yamato Holdings' investment narrative is reshaped by Farallon’s governance push following the wider half year loss.
What Is Yamato Holdings' Investment Narrative?
To own Yamato Holdings, you really need to believe this logistics group can turn a large, complex delivery network into consistently profitable cash generation again. The core story is about execution. Parcels still move, trucks still roll, but the half year numbers show sales broadly flat at ¥906,854 million while the net loss widened to ¥10,562 million and basic loss per share deepened to ¥33.35. That points to pressure in costs, pricing, or both, in a business that already runs on tight margins and heavy asset needs.
The Farallon stake and its call for a monitoring-style board pull governance into the near term catalyst list. In the short term, the debate over leadership and board structure could shape how quickly management tackles weak 0.4% net margins, one off items and a dividend that is not well covered by earnings. Forecasts still point to strong earnings growth and the stock trades well below one estimate of future cash flow value. However, the current P/E of 91.8x against lower fair and peer multiples shows how much faith is already implied in that repair story.
That said, there is one uncomfortable angle to the Yamato Holdings turnaround story that rarely shows up in headline numbers...
There's only one way to know the right time to buy, sell or hold Yamato Holdings. Head to Simply Wall St's company report for the latest analysis of Yamato Holdings's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly ¥1,834 to ¥3,799 per share, which already shows how far opinions on Yamato Holdings can stretch. These views were formed before the latest widening loss and Farallon’s demands. Treat them as starting points and compare several viewpoints before deciding how this story fits your portfolio.
Explore another Yamato Holdings fair value estimate, including one that suggests up to 64% upside from the current price!
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Yamato Holdings research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Yamato Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Yamato Holdings' overall financial health at a glance.
Looking For More Ideas Beyond Yamato Holdings?
If the Yamato Holdings story has you rethinking concentration risk, it can help to scan a broader watchlist built around the qualities you care about most. The Simply Wall St screener gives you a fast way to filter for businesses that better match your tolerance for volatility, income needs, and balance sheet comfort.
- Prefer sturdier balance sheets and fewer financial surprises? Start with a list of solid balance sheet and fundamentals (25 results) that already clears a basic resilience bar.
- Interested in quality at a discount? Use a 18 high quality undervalued stocks that pairs healthier fundamentals with more modest expectations baked into the price.
- Looking for companies that attract less dramatic risk flags? Scan a 20 resilient stocks with low risk scores that may offer a calmer ride than turnaround situations like Yamato Holdings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com