


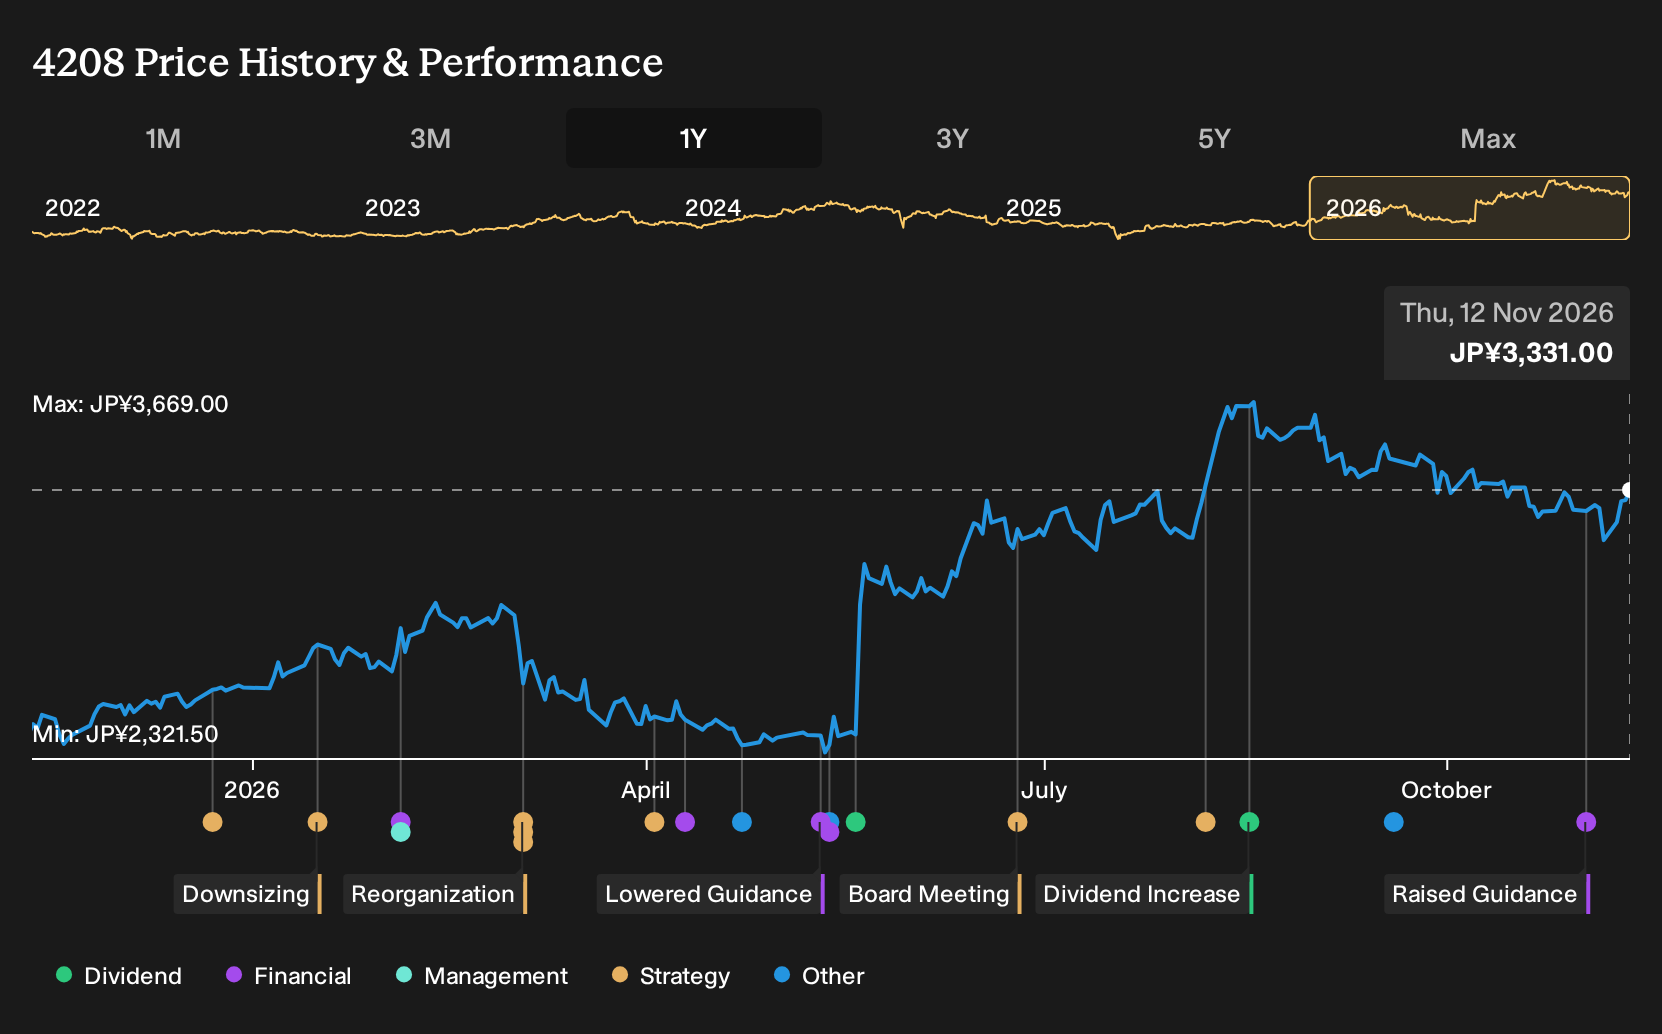
- UBE Corporation raised its earnings guidance for the six months to September 30, 2026 and the full year to March 31, 2027, pointing to higher selling prices and stronger profits across key segments, with updated net sales targets of ¥244.7b for the half and ¥518.0b for the year.
- The revised outlook highlights how pricing power and inventory valuation gains in the Polymers & Chemicals business, combined with steady Specialty Products and Machinery performance, are offsetting weaker Pharmaceutical demand and higher integration costs in High Performance Urethane.
- The focus now is on how UBE's upgraded guidance, supported by pricing strength within Polymers & Chemicals, may influence its broader investment narrative.
Compare UBE's upgraded guidance with a curated group of peers by scanning the list of solid balance sheet and fundamentals (25 results).
What Is UBE's Investment Narrative?
To own UBE, you need to be comfortable with an old line industrial group. Its story is really about execution in chemicals, specialty materials, and machinery rather than a single blockbuster growth engine. The upgraded guidance leans heavily on pricing and inventory gains in Polymers & Chemicals, plus steady demand in Specialty Products and Machinery. That helps near term, especially with earnings already recovering and profit margins higher than last year, but it does not suddenly turn this into a high growth profile.
In the short term, the raised outlook supports the idea that UBE can use pricing power to blunt weaker Pharmaceutical sales and higher urethane integration costs. Investors still have to weigh that against the capital intensive nature of chemicals and machinery, debt that is not well covered by operating cash flow, and a dividend that free cash flow does not fully support. The case for the stock is really about disciplined operations and pricing, not aggressive expansion.
Even so, there is a structural issue lurking in the background that could matter far more if...
There's only one way to know the right time to buy, sell or hold UBE. Head to Simply Wall St's company report for the latest analysis of UBE's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly ¥1,031 to ¥3,450 per share, so private investors are clearly not aligned on where UBE should trade. Those views also predate the upgraded earnings guidance, so pricing power in Polymers & Chemicals could shift how you think about future performance.
Explore another UBE fair value estimate, including one that suggests as much as 69% downside from the current price!
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your UBE research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for UBE. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate UBE's overall financial health at a glance.
Looking For More Investment Ideas Beyond UBE?
If UBE's upgraded guidance has sharpened your interest in cyclicals and balance sheet quality, it can help to compare it with a broader set of opportunities that match your own risk and income preferences.
- If income is front of mind, scan for potential cash flow payers among 27 dividend fortresses that may offer yield with more resilience.
- If valuation discipline matters most to you, review the 18 high quality undervalued stocks that pair solid fundamentals with more modest pricing.
- If capital preservation sits higher on your priority list, focus on the 20 resilient stocks with low risk scores that score well on financial strength and risk controls.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com