


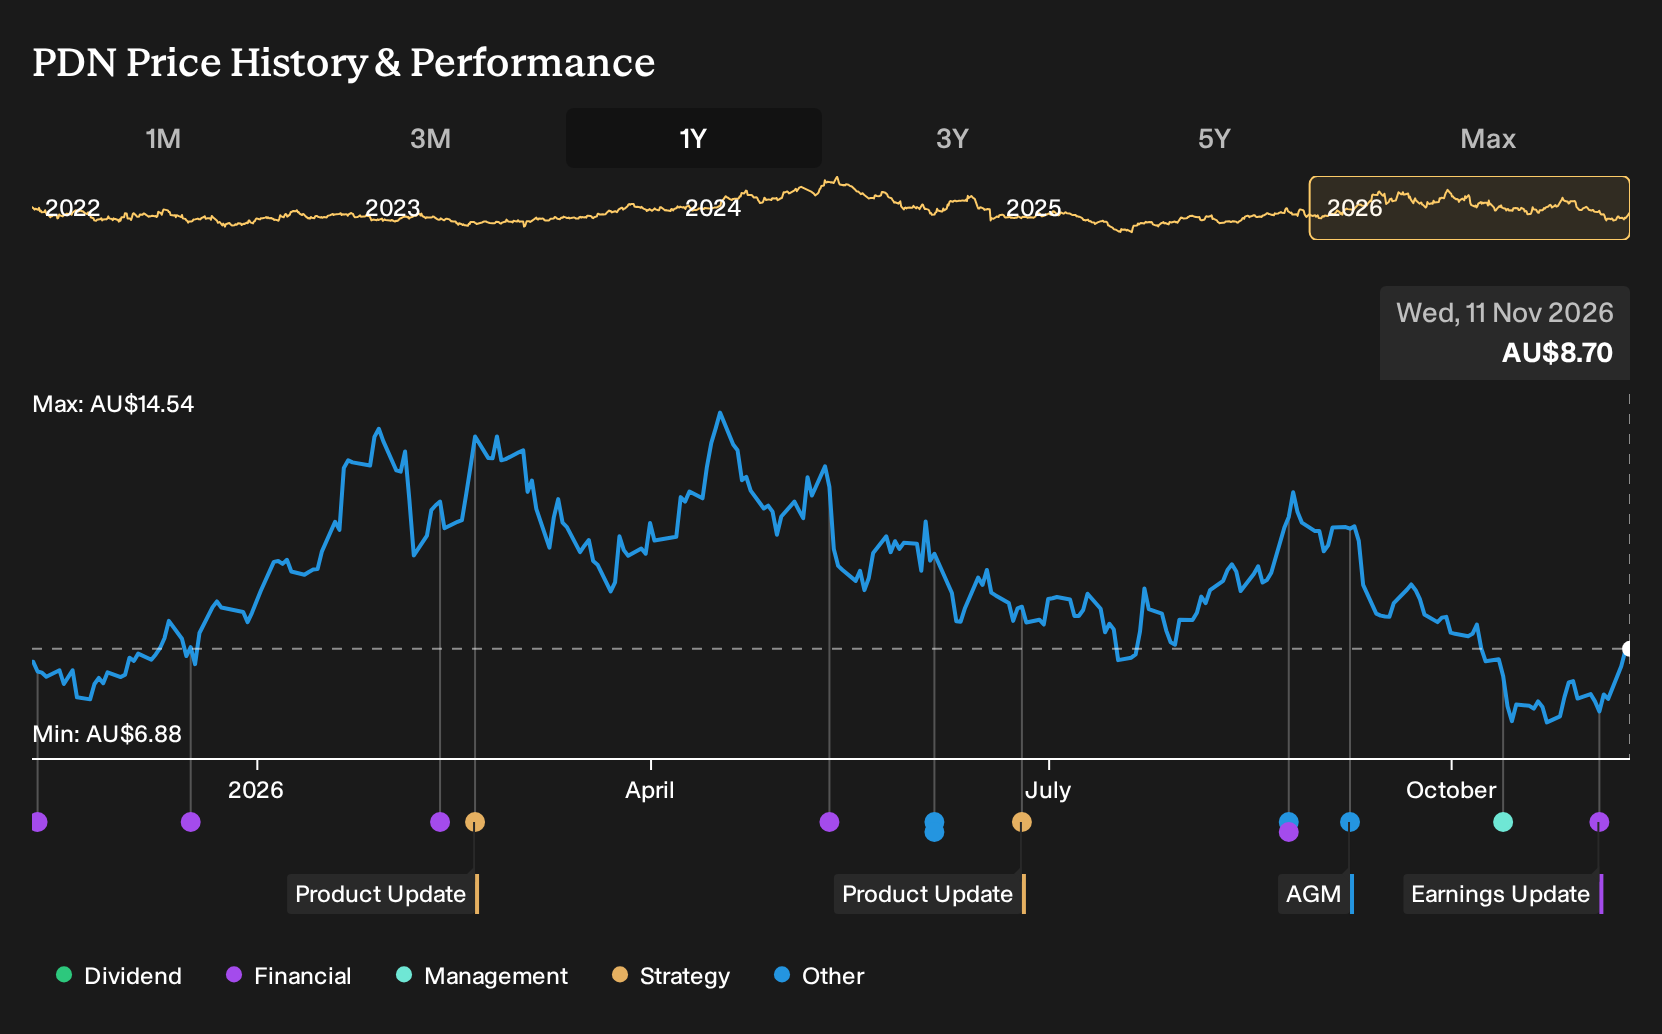
- Paladin Energy has completed a fully underwritten equity raise of about A$525 million through follow-on offerings on the ASX and TSX, issuing roughly 67.2 million ordinary shares at A$7.80 each to fund project development, exploration and debt repayment.
- The scale and structure of this capital injection indicate a shift toward funding the Patterson Lake South project and related growth work, while also maintaining balance sheet flexibility.
- We will now look at how this large equity raise could reshape Paladin Energy's investment narrative around Langer Heinrich and PLS.
Scan how Paladin Energy's latest equity raise compares to peers by reviewing curated 17 nuclear energy infrastructure stocks positioned for the next leg of nuclear infrastructure build out.
Paladin Energy Investment Narrative Recap
To own Paladin Energy, you need to believe Langer Heinrich can deliver on its production and cost guidance while Patterson Lake South gradually turns from concept into a funded project. According to Miner2025, an investor in the Simply Wall St Community, the story has been tilting toward PLS, which puts even more pressure on Namibian operations to stay on track.
The equity raise gives Paladin Energy more room to fund PLS and repay debt, so near term liquidity risk looks less acute. The key near term catalyst still sits with Langer Heinrich hitting its second half weighted guidance. The main risk remains another soft quarter that tightens that guidance corridor and raises questions about execution.
The recent first quarter update for the period to 30 September 2026 matters here. Paladin Energy reported sales of US$92.38 million and net income of US$4.29 million compared with a loss a year earlier. Profitability helps support the case for raising equity to fund long lead projects rather than relying solely on higher cost borrowing.
Miner2025 argues that guidance already leaned heavily on a stronger back half, so the new capital now meets an execution test. Langer Heinrich still needs higher output and lower unit costs to align with the stated production and cost ranges. If that operational ramp stutters, the enlarged share base could magnify any disappointment around future volumes or margins.
Miner2025 estimates a fair value of A$9.25 for Paladin Energy, based on an assumed 16.1% yearly revenue growth rate and a future profit margin of 1.8%. Together, these assumptions present the company as a steady, low-margin uranium producer with potential long-dated upside from Patterson Lake South.
Uncover why Paladin Energy's fair value indicates a 6% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
The lowest analysts focus on Patterson Lake South as the real swing factor for Paladin Energy. They see a risk that rising capital needs squeeze returns and keep earnings closer to about US$67.6 million on roughly US$494.6 million of revenue by 2029. Those forecasts were set before this equity raise, so opinions may evolve.
Explore 8 other Paladin Energy fair value estimates, including one that suggests as much as 93% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Paladin Energy research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Paladin Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Paladin Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond Paladin Energy?
If Paladin Energy sits in the middle of your thesis on uranium and infrastructure, it can help to compare it with other companies that meet clear, data driven criteria. Use the Simply Wall St Screener to widen your opportunity set while still keeping the focus on quality and risk.
- If you want potential upside but do not want to ignore balance sheet strength, scan a curated list of solid balance sheet and fundamentals (12 results) that keeps financial resilience front and center.
- For investors who care about buying quality at a reasonable price, review a focused 3 high quality undervalued stocks that combines stronger fundamentals with attractive valuations.
- If you are hunting for fresh ideas off the beaten path, sift through a targeted 14 high quality undiscovered gems that rarely feature in headline indexes but still show robust underlying numbers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com