


Parker-Hannifin (PH) drew fresh attention after releasing first quarter results on November 5, reporting higher sales, net income and earnings per share, and then reinforcing the storyline with updated full year guidance.
Parker-Hannifin has seen mixed momentum in 2026, with the share price up 7.16% year to date but down 9.27% over the past three months. However, a 14.72% one year total shareholder return and very strong five year gains suggest long term holders have still been well rewarded.
Scan Parker-Hannifin’s peers for similar earnings momentum and guidance upgrades by checking our curated list of 32 high quality undervalued stocks, which may be pricing in less optimism than the headlines suggest.
Parker-Hannifin has already delivered strong multi year gains, yet the recent pullback after a powerful run raises a simple question: Is most of the upside already behind the stock, or does the current valuation still leave room ahead?
Most Popular Narrative: 16% Undervalued
On the analyst numbers that underpin Simply Wall St’s fair value work, Parker-Hannifin’s narrative value of $1,138.29 sits above the last close at $957.98. The analyst consensus Narrative on Simply Wall St frames that gap through the lens of margins, mix and cash generation under an 8.58% discount rate.
The enlarged portfolio of longer-cycle, higher-margin businesses, including Aerospace, Engineered Materials and Filtration, now represents about 65% of pro forma sales and includes recently added filtration assets. This can increase the share of recurring and aftermarket revenue and support more stable earnings and cash generation across economic cycles.
See why 51 investors see Parker-Hannifin as 16% undervalued.
Result: Fair Value of $1,138.29 (UNDERVALUED)
Still, the Parker-Hannifin narrative can crack if organic revenue growth stays subdued or if premium valuation multiples compress following any stumble in margins or cash generation.
Find out about the key risks to this Parker-Hannifin narrative.
Another Take On Parker-Hannifin’s Valuation
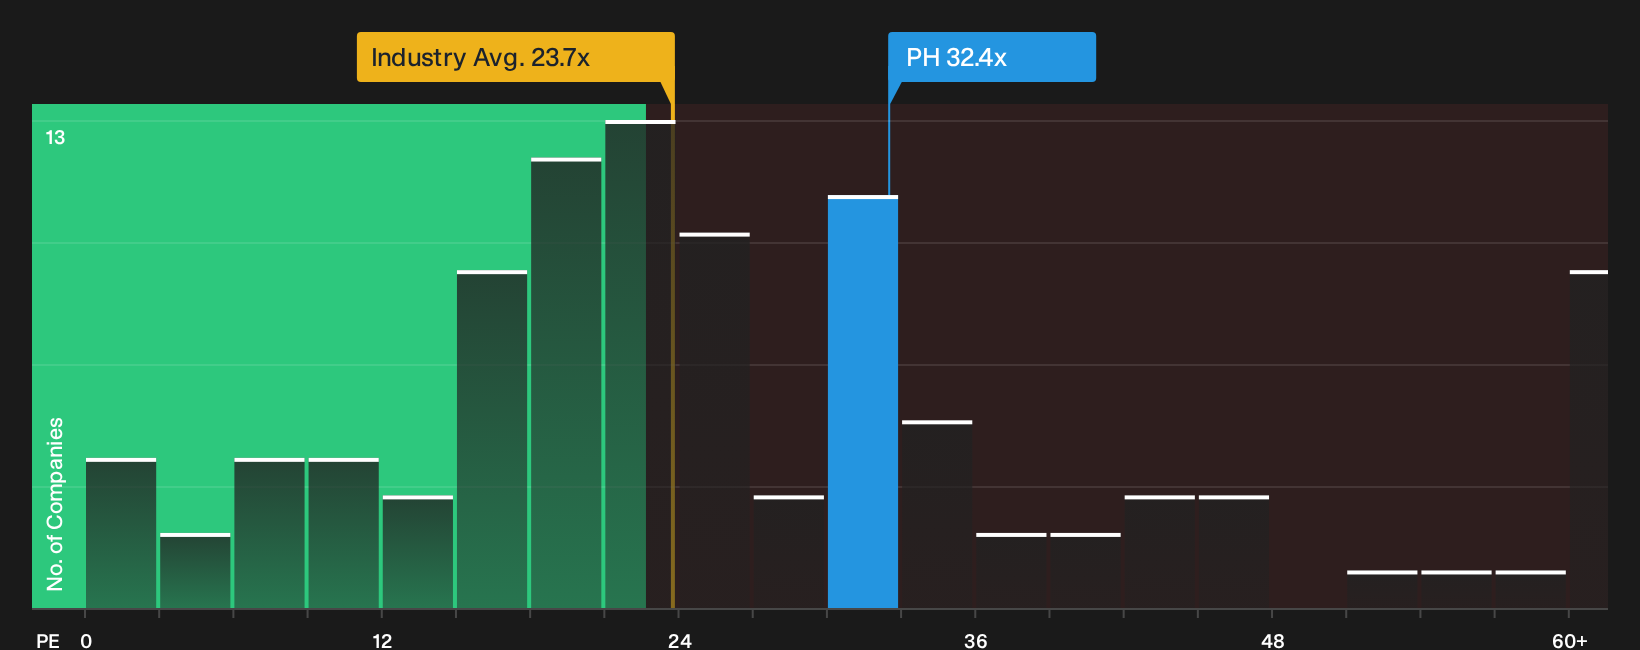
The fair value story built on analyst targets paints Parker-Hannifin as 16% undervalued. The P/E picture is very different. The stock trades on 32.4x earnings, compared with a fair ratio of 29.6x and a US Machinery average of 23.7x, which points to rich expectations already in the price.
That kind of premium can work in an investor’s favor if profit trends stay strong, but it also gives less room for disappointment if margins or growth soften. The question is whether you view that valuation gap as justified quality or as extra risk that needs a bigger margin of safety, and the detailed breakdown in our valuation work can help you weigh that trade off, starting with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Parker-Hannifin so far. If you want to move past the headlines and form your own stance quickly, weigh both sides of the story by reviewing 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Parker-Hannifin?
If Parker-Hannifin has you thinking harder about price, quality and risk, do not stop with a single ticker. Use the tools available and give yourself a stronger watchlist.
- Target robust balance sheets and steadier fundamentals by filtering companies through our list of solid balance sheet and fundamentals (23 results).
- Hunt for quality at a reasonable price by scanning the 32 high quality undervalued stocks that may not reflect all of their strengths yet.
- Focus on resilience first by checking out 29 resilient stocks with low risk scores that can help anchor the more volatile parts of your portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com