


Spire (SR) just approved a higher annual common dividend, lifting the payout to US$3.46 per share from US$3.30. The decision highlights the board’s focus on consistent cash returns to shareholders.
Recent trading has been mixed for Spire, with the share price up 10.11% over the past month and 6.40% over 90 days, while 1-year total shareholder return sits at 2.86% compared with a much stronger 3-year total shareholder return of 68.13%, suggesting longer term holders have seen firmer momentum than those focused on the past year.
Scan beyond Spire and compare its dividend story with utilities and income-focused peers hand picked in our 6 dividend fortresses.
Bulls point to Spire’s long dividend streak and recent increase, while bears flag the weaker near term share gains and earnings uncertainty. Which story does the current valuation support going forward?
Most Popular Narrative: 4% Undervalued
Spire closed at $88.14, while the analyst consensus Narrative on Simply Wall St marks fair value at $91.40, implying the shares trade at a small discount and tying the investment case closely to a long regulated capital plan.
The acquisition of Piedmont Natural Gas Tennessee, which added about 200,000 customers and US$1.6b of rate base funded without common equity, can give Spire more regulated revenue and wider earnings contribution once new customer and infrastructure investments are fully reflected in rates and margins.
Execution of the US$11.2b long term capital plan, including about US$800m of fiscal 2026 capex, is described as expanding the regulated asset base in Missouri, Tennessee, Alabama and the Gulf, which can support higher allowed returns and a larger earnings base over time.
See why 1 investors see Spire as 4% undervalued.
Result: Fair Value of $91.40 (UNDERVALUED)
Still, the Spire story can unravel if regulators take a tougher stance on rate recovery or if decarbonization policies erode long run gas demand.
Find out about the key risks to this Spire narrative.
Another View: Spire Looks Pricey On Earnings
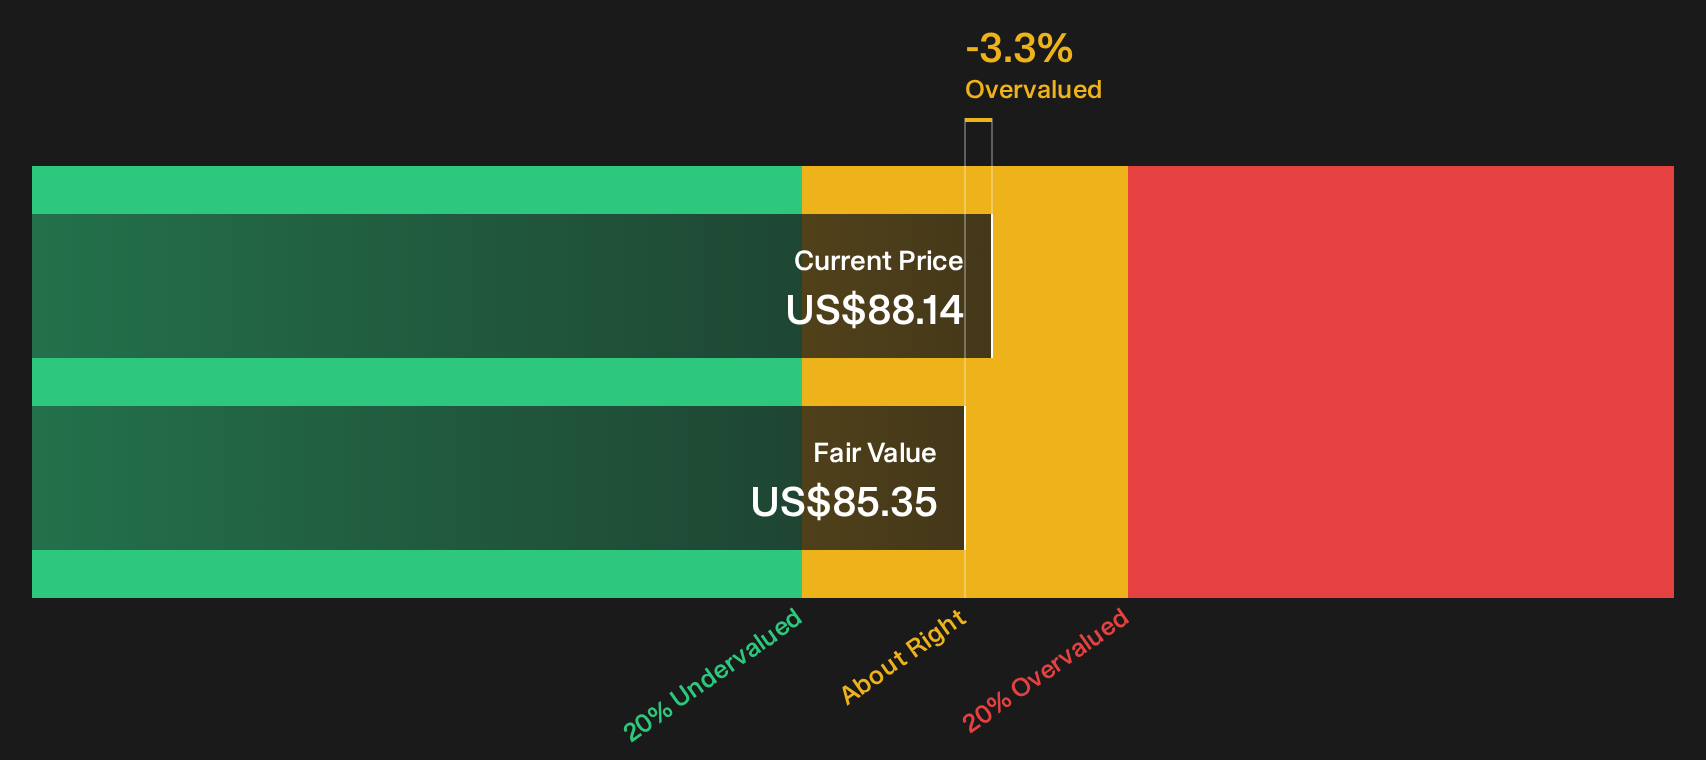
The SWS DCF model points to a fair value of $85.35, which sits slightly below Spire’s current $88.14 share price and labels the stock as overvalued on that basis. That clashes with the $91.40 fair value from the analyst narrative. Which yardstick do you trust more for a long term holding?
For a closer look at how this cash flow view is built, and what would need to change for the DCF outcome to move closer to the analyst target, Look into how the SWS DCF model arrives at its fair value..
Next Steps
Mixed views on Spire’s value and outlook can make the story feel murky. Move fast, look through the data, and weigh the 2 key rewards and 2 important warning signs.
Looking for more Spire-sized investment ideas?
If Spire has your attention today, do not stop there. Use the screener to pull together fresh candidates so you are not relying on one story.
- Target resilient compounding by scanning a 29 resilient stocks with low risk scores that focuses on businesses with stronger defenses when conditions get bumpy.
- Hunt for better value by checking the 20 high quality undiscovered gems that surfaces quality companies the crowd may have overlooked.
- Strengthen your income toolkit by reviewing a list of solid balance sheet and fundamentals (23 results) so potential dividend payers rest on sturdier financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com