


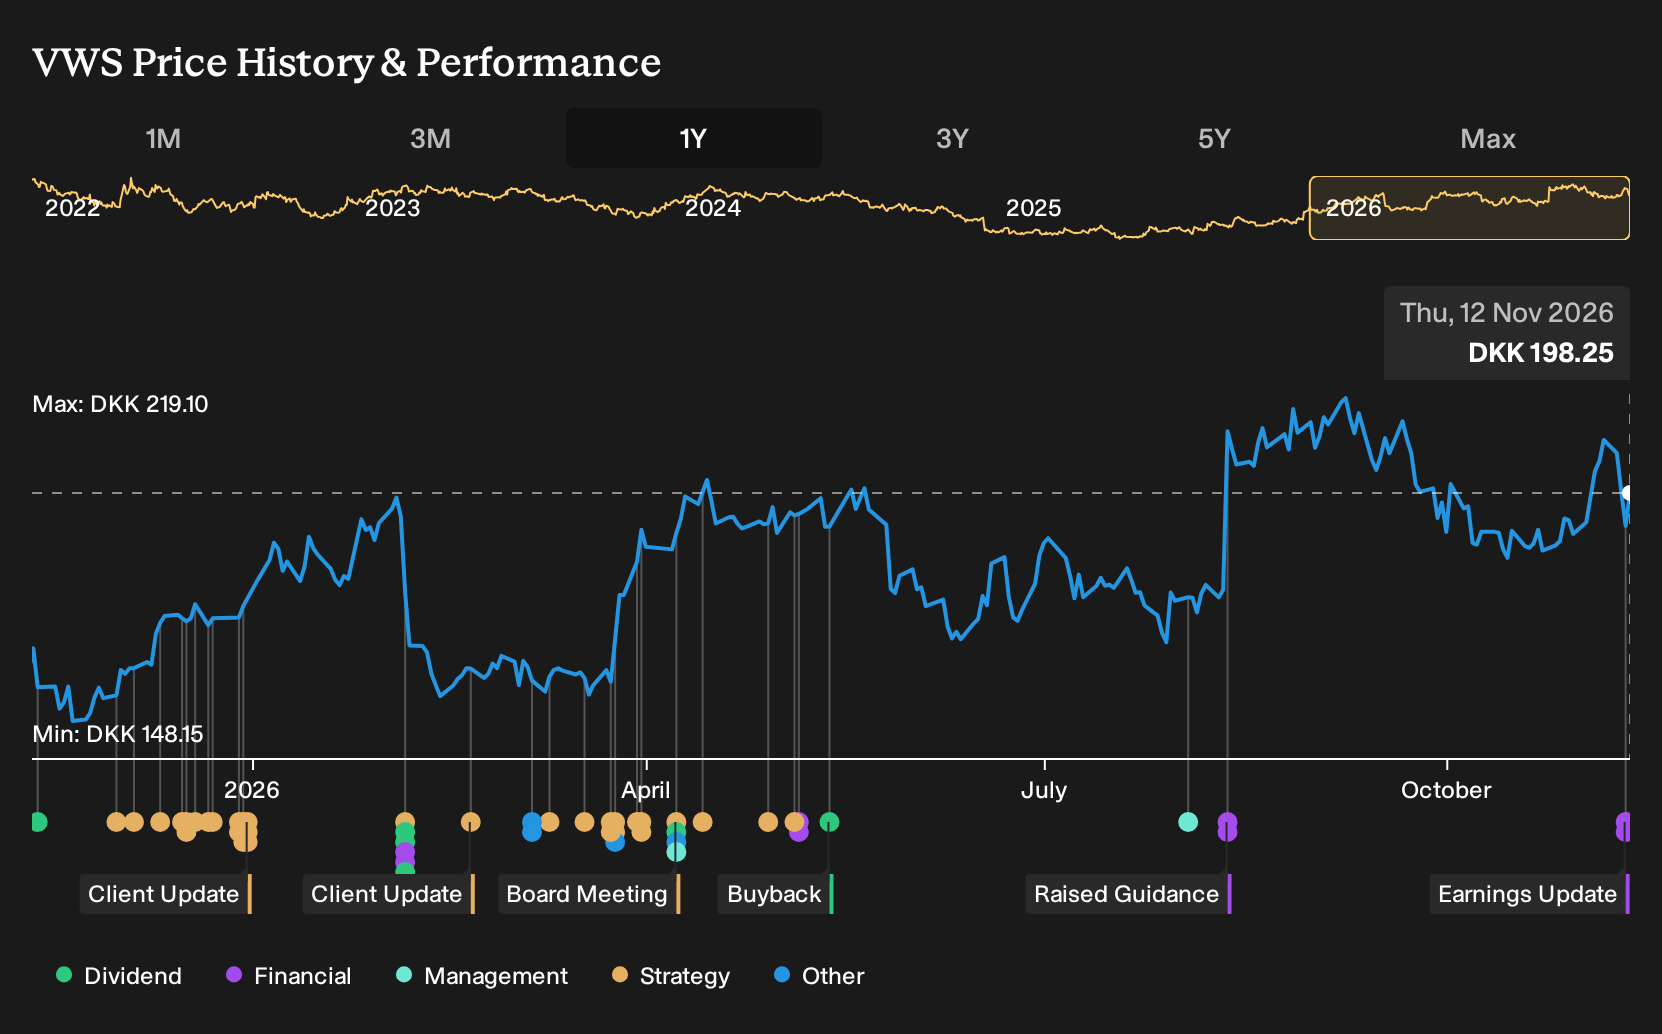
If you had been weighing Vestas Wind Systems on 12 November 2025, you were staring at clashing analyst stories about order volatility, offshore losses and long term demand for wind. Investors who held Vestas Wind Systems over the past year are up 27.9%, including dividends. That result now invites a harder question. What exactly were early buyers focusing on in those reports, and which uncertainties looked like acceptable risk rather than deal breakers?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
The easy part of this move is behind Vestas Wind Systems. Zero in on 193 high quality undervalued stocks for companies trading below our estimates.
The Two Stories Investors Had To Choose Between On Vestas Wind Systems
The shares cost DKK164 at the start of the period, so anyone looking at Vestas Wind Systems first had to ask whether that price matched their own story about future wind demand and profitability.
The bullish Narrative saw Fair Value at DKK195, based on assumptions that Vestas Wind Systems could convert a strong onshore and offshore project pipeline into faster revenue growth and higher margins, supported by decarbonization and electrification trends.
The more cautious Narrative put Fair Value at DKK141 and focused on pressure from policy uncertainty, price competition and offshore ramp up losses that could weigh on profit margins even if orders improved.
What The Evidence Around Vestas Wind Systems Actually Tested
The clearest new fact was order and project momentum for Vestas Wind Systems. Fresh turbine deals in Canada, Peru, Bulgaria and Japan, plus offshore projects using V236-15MW units, supported the bullish focus on backlog conversion. Q3 2026 also showed revenue and net income higher than Q3 2025, although net margin slipped slightly from 5.7% to 5.6%. Overall, the evidence cut both ways.
The hinge assumption here was not just volume but also the quality of earnings. When assessing another manufacturer, track whether rising order headlines are matched by stable or improving net margin, rather than only watching revenue or share price moves.
What Vestas Wind Systems' Latest Jump Already Prices In
Today Vestas Wind Systems trades at DKK198 after a 27.9% gain over the past year. The bearish analyst Narrative on Simply Wall St places its Fair Value below that level, arguing the market is charging a premium for a smooth repair job on offshore and service profitability.
For the current price to hold up, a buyer has to judge that offshore technology issues stay contained and that service contracts steadily earn more, without forcing management to divert cash away from shareholder payouts into fixing new problems.
"Although Vestas Wind Systems is increasing offshore deliveries and reporting better manufacturing and installation efficiency, the recent blade failure at the He Dreiht project highlights that unresolved technology and execution risk could trigger additional remediation work, higher warranty usage and potential project penalties that weigh on EBIT margins and earnings."
The price and this Narrative do not agree. → Uncover what this Narrative says Vestas Wind Systems is actually worth
Before The Next Story Makes Headlines
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 34% below our estimate - turns AI data center expansion and hybrid pricing into growing recurring software revenue.
- Company 2 - 44% below our estimate - applies AI to hiring and service matching to increase monetization of digital traffic.
- Company 3 - 22% below our estimate - adds maintenance-focused sales capacity to secure more long term service contracts.
Those are three of them. See the full list of 200 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com