


- Charter Communications (NasdaqGS:CHTR) launched a US$1.5b cash tender offer for multiple outstanding series of senior notes.
- The repurchase targets a range of maturities, giving management flexibility in how it adjusts Charter's existing debt stack.
- Charter also introduced a managed Cisco Secure Networking service for enterprise clients that includes post quantum cryptography capabilities.
- The US$1.5b note tender and new Cisco Secure Networking product are only part of the wider Charter story. Take a look at 3 warning signs (1 major) we have identified for Charter Communications.
This move into managed secure networking is not unique to Charter, and several other providers are also exposed to the same enterprise security and connectivity trend, which makes it worth comparing them through our screener containing 20 high quality undiscovered gems.
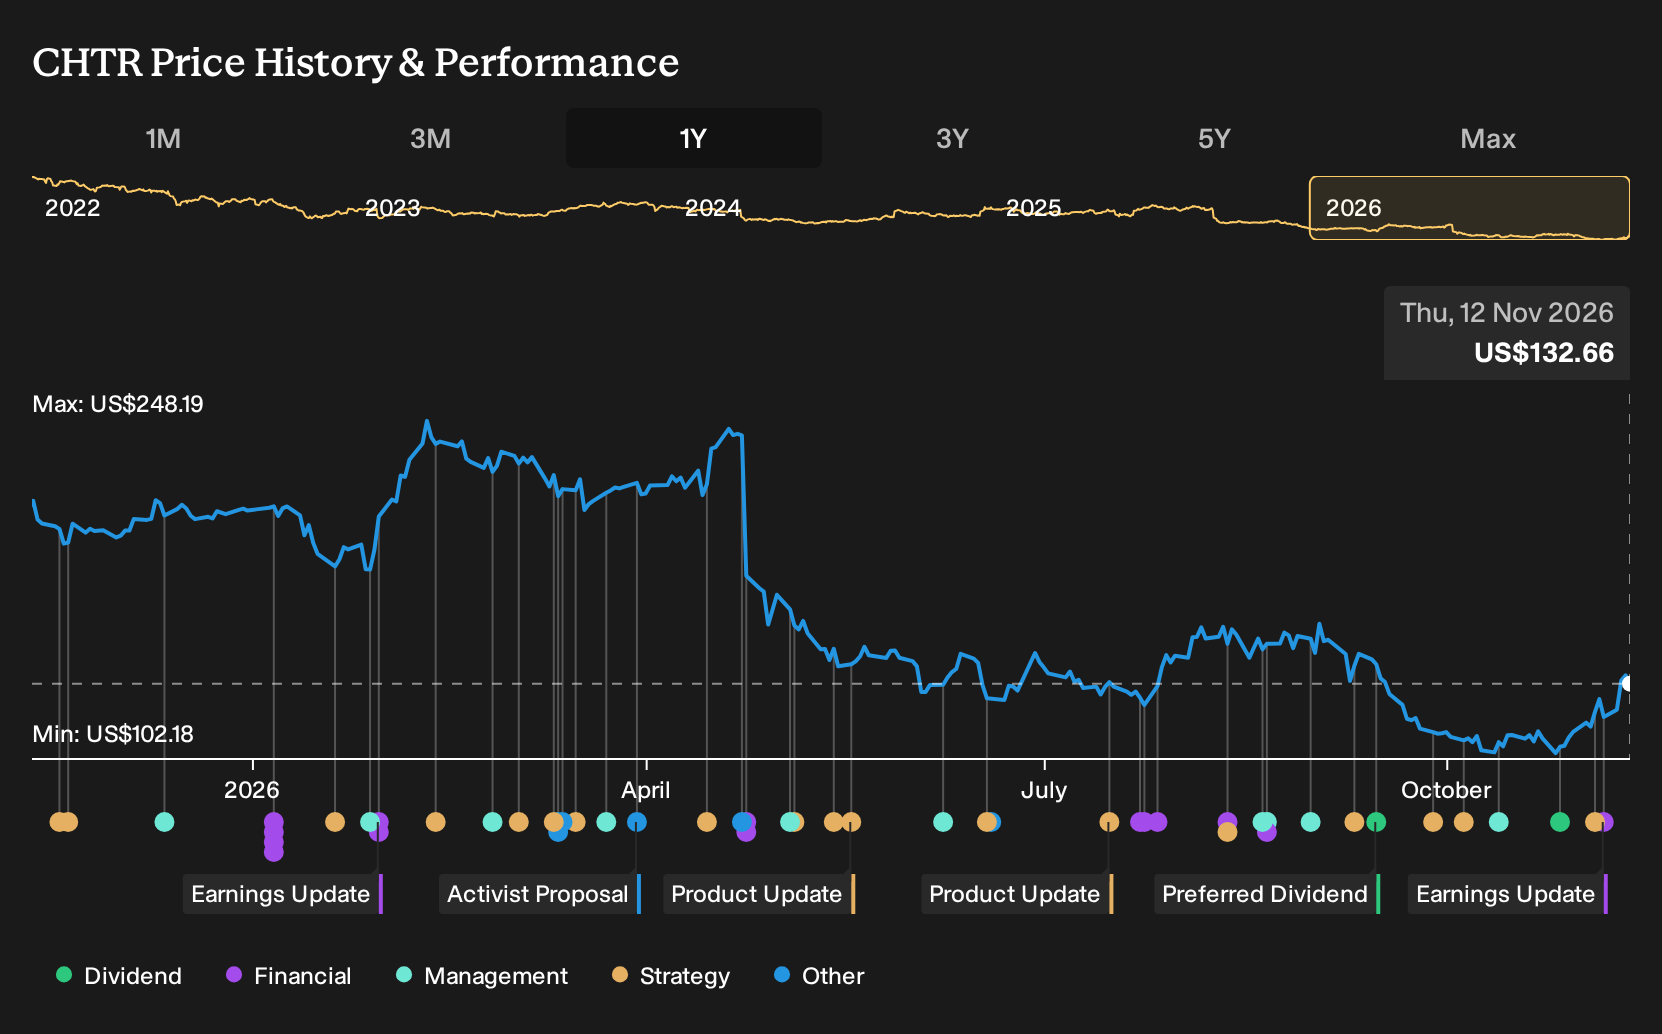
Charter Communications runs a large US broadband connectivity operation, so a move into managed Cisco Secure Networking and active balance sheet work both speak to how management is positioning a US$22.3b media player that earns its keep by keeping data flowing securely for customers.
See how Charter Communications's balance sheet measures up.
Charter’s debt tender leans into the deleveraging story while security push tests the Cox synergy case
For Charter Communications, a US$1.5b note tender lines up squarely with the Narrative focus on deleveraging in a business where interest costs are not comfortably covered by earnings. Retiring multiple series of notes can simplify the capital structure and may trim future interest expense, which matters after a Q3 2026 net loss of US$2.4b and a sharp drop in profit margins from 9.3% to 2.5%. The new managed Cisco Secure Networking offer leans into the Cox scale thesis by adding another enterprise service that could benefit from the enlarged footprint and planned US$1b plus of synergies.
See how these catalysts shape Charter Communications' path to a $169 fair value.
The next proof point sits in upcoming debt and earnings updates around the November 17, 2026 tender expiry. Investors can see how much of the US$1.5b capacity Charter actually takes out, what the effective interest cost looks like afterward, and whether management ties that directly to its US$2b expense reduction and Cox integration plan.
One Charter Communications question this article has not answered yet
Everything here has focused on what Charter Communications is doing today, but the analyst models sketch a very different picture of where this business could land a few years from now. See where analysts expect Charter Communications to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com