


Regulatory milestone puts uniQure’s Huntington’s program in focus
uniQure (NasdaqGS:QURE) has drawn fresh attention after the FDA accepted its Biologics License Application for ifezuntirgene inilparvovec in Huntington’s disease under the Accelerated Approval pathway, granting Priority Review with a May 2027 target decision date.
Recent trading shows how quickly sentiment around uniQure can swing. The stock has a 7-day share price return of 17.23% and a 30-day share price return of 15.74%. However, the 90-day share price return shows a fall of 49.34%, and the 1-year total shareholder return is down 18.82%. That mix points to momentum rebuilding in the short term as investors react to the Huntington’s regulatory milestone and the November earnings update, while still reflecting years of volatility, including a very large 3-year total shareholder return of about 3x and a small decline over five years.
Spot emerging momentum around gene therapy by scanning 20 high quality undiscovered gems, which, like uniQure, are working on high-impact treatments in areas with limited existing options.uniQure now has a high-profile Huntington’s asset, fresh regulatory momentum and a history of sharp share price swings. The real tension shifts to the basics: Does the current price fairly reflect that mix of promise and risk?
Most Popular Narrative: 58.9% Undervalued
On the analyst consensus Narrative on Simply Wall St, uniQure’s fair value of $59.99 sits far above the last close at $24.63, which puts a spotlight on how much of the Huntington’s story is already reflected in the price.
The main thing that has to go right is that AMT-130’s risk benefit profile and confirmatory trial outcomes support regulatory confidence and physician willingness to use a one-time neurosurgical gene therapy in Huntington’s disease, while the broader pipeline, including AMT-260 and AMT-191, addresses efficacy and safety questions.
The numbers imply that the current share price assigns limited value to AMT-130’s potential Huntington’s disease franchise and to uniQure’s broader gene therapy pipeline, which some analysts view as consistent with the perspective that the stock may be undervalued.
See why 12 investors see uniQure as 59% undervalued.
Result: Fair Value of $59.99 (UNDERVALUED)
Still, the narrative around uniQure can change quickly if AMT-130’s mixed efficacy signals lead to regulatory pushback or if rising SG&A keeps quarterly losses elevated.
Find out about the key risks to this uniQure narrative.
Another View: When uniQure Looks Expensive
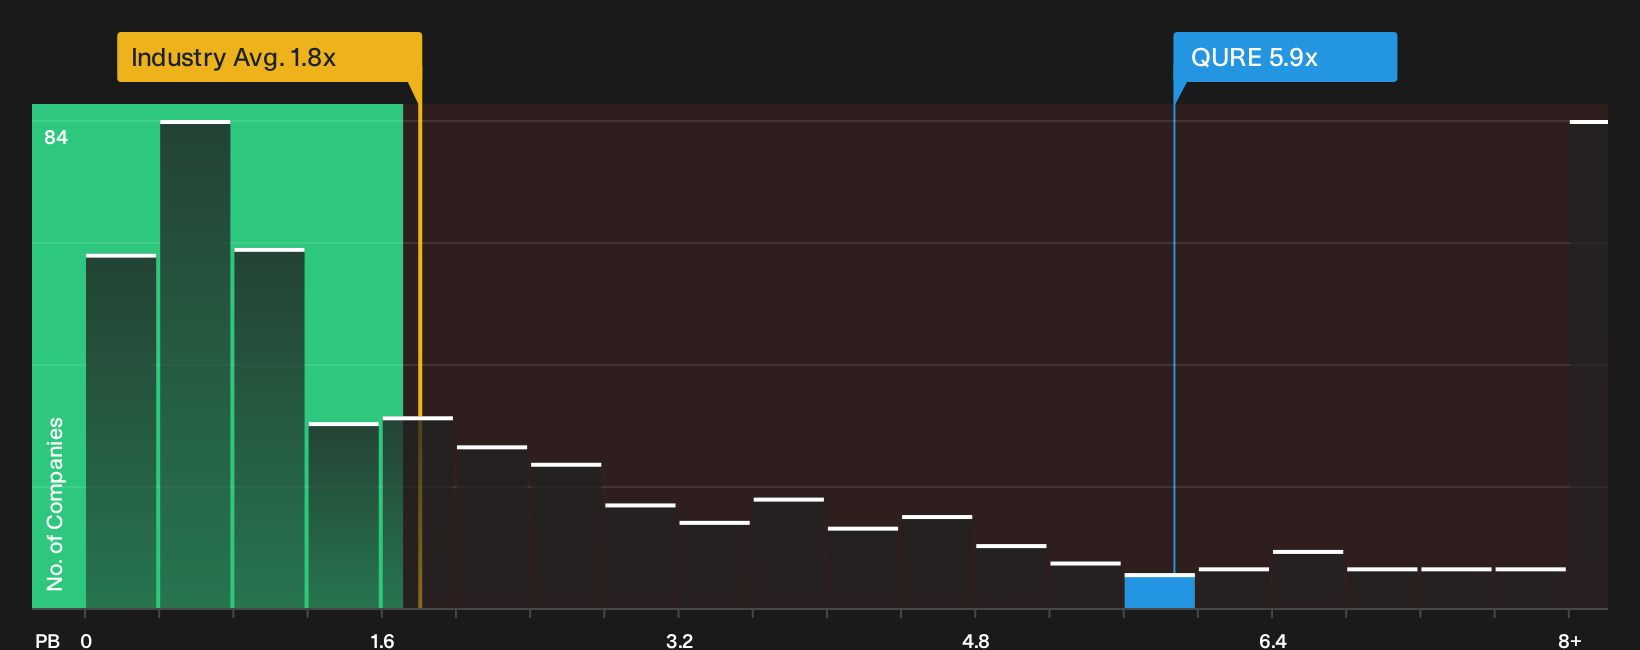
The first story around uniQure leans on long term cash flows and points to a big gap between price and potential. On a simple P/B lens the picture is less generous. QURE trades at 5.9x book value versus 1.9x for the US Biotechs sector and 11.7x for its closest peer group. That puts it well above the broader industry but below direct comparables, which raises the question of whether the stock is priced for future wins that are still unproven, or whether the premium is simply the cost of optionality around Huntington’s.
To see how that valuation gap is framed by fundamentals rather than hope, have a look at See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on uniQure can be confusing, so do not wait for the crowd to decide the story for you. Weigh both sides of the debate by looking through the 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond uniQure?
If you stop with uniQure, you risk missing other opportunities that fit your style, your risk level and the themes you care about most.
- Target resilient cash generators by scanning a list of solid balance sheet and fundamentals (23 results) that pairs sturdy finances with room for future upside.
- Hunt for mispriced quality by reviewing a 32 high quality undervalued stocks tailored to investors who want strong fundamentals without stretching on price.
- Dial back portfolio stress by focusing on a 29 resilient stocks with low risk scores that highlights businesses with steadier risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com