


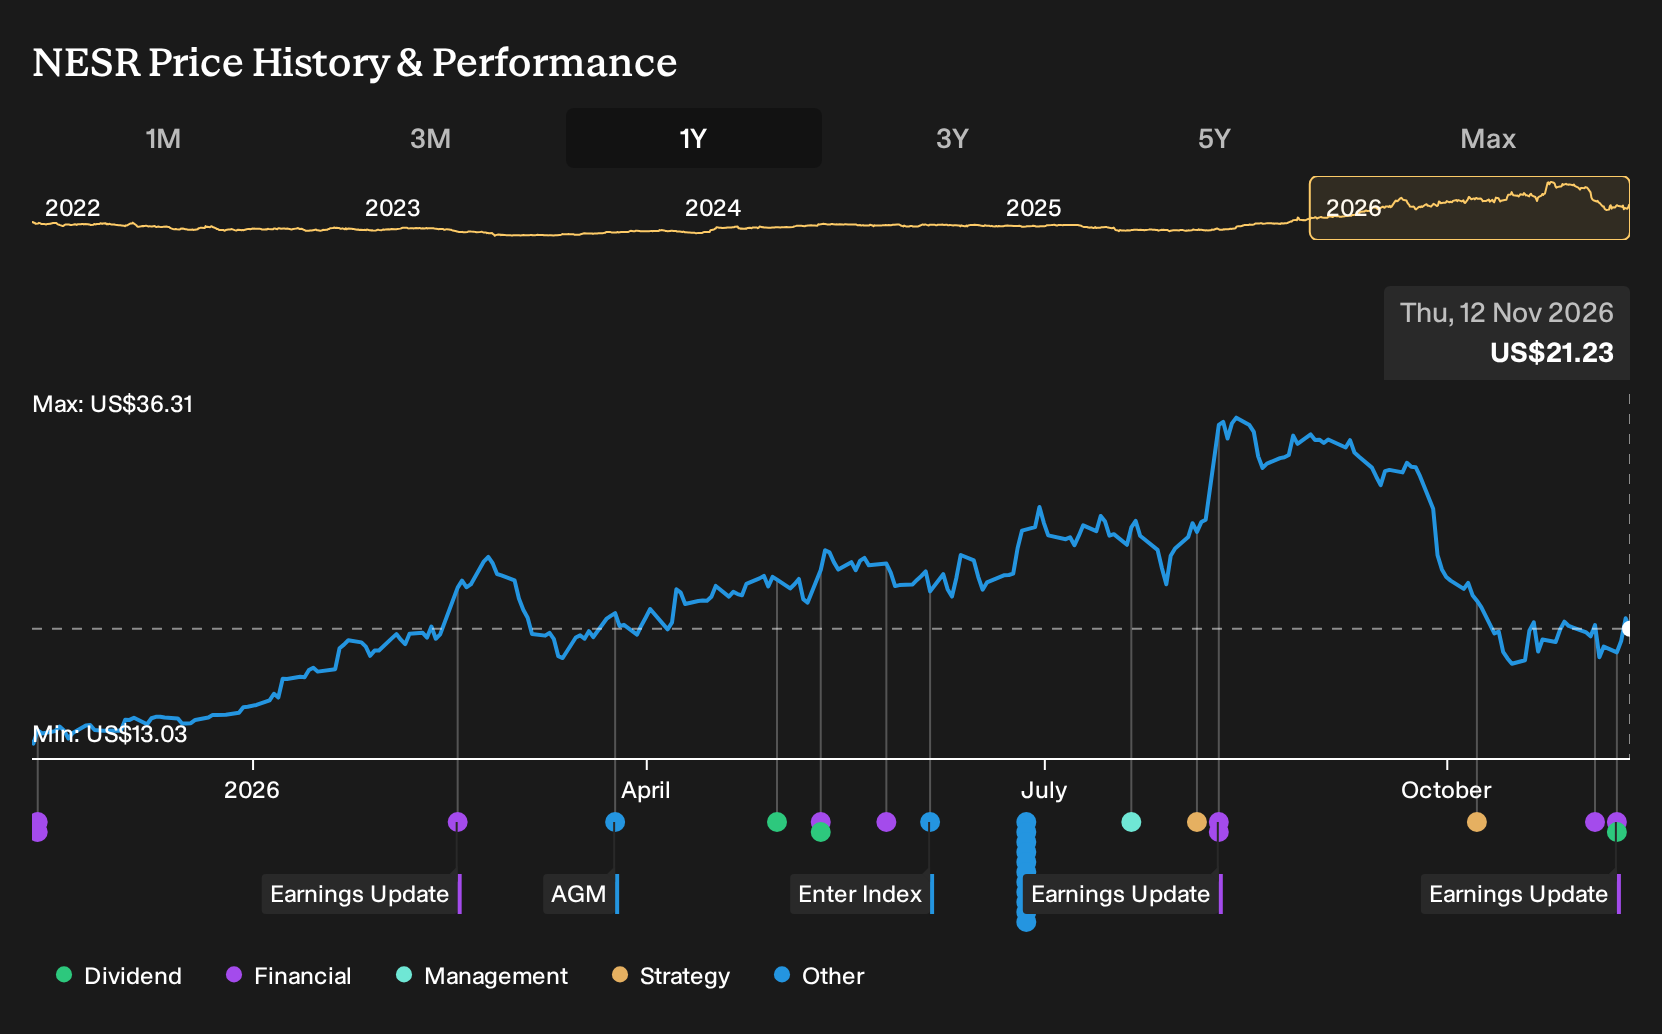
- National Energy Services Reunited reported Q3 2026 sales of US$504.73 million and net income of US$34.33 million, alongside a US$0.10 per share quarterly dividend declared for payment on December 10, 2026.
- The combination of higher earnings per share from continuing operations and a maintained cash payout reflects confidence in ongoing cash generation and balance sheet flexibility.
- This article examines how National Energy Services Reunited's investment narrative is influenced by its Q3 profitability and sustained quarterly dividend.
Scan handpicked income ideas that pair earnings power with regular cash returns using our 6 dividend fortresses as a starting universe alongside National Energy Services Reunited.
National Energy Services Reunited Investment Narrative Recap
To stay invested in National Energy Services Reunited, you need to be comfortable with an execution story tied closely to MENA upstream spending, particularly Saudi Arabia and Kuwait, while the firm keeps lifting capital expenditure. The analyst consensus narrative on Simply Wall St leans on programs like Jafurah and technology contracts to support that effort. Q3 results with US$504.73 million in sales and higher earnings per share help reinforce that the operating engine is currently delivering against that thesis.
The main near term swing factor is activity levels and project timing in the Middle East, which previous commentary flagged as a pressure point for second half 2026 expectations. The biggest risk is that higher 2026 capex of about US$210 million to US$215 million does not translate into matching revenue and cash flow. That outcome would leave less room for future shareholder distributions despite the current US$0.10 quarterly dividend.
The most relevant recent announcement for that thesis is the new 2026 Secured Facilities Agreement totaling about US$747.1 million across term loans, a revolving credit line and uncommitted working capital facilities. This refinancing was set up to support operations and working capital, with interest costs tied to benchmarks like SOFR and SAIBOR plus leverage and sustainability linked margins.
For you as a shareholder, this financing structure matters because it underpins National Energy Services Reunited’s ability to fund higher capex, execute the 3B3 revenue plan and keep large projects running smoothly, while being constrained by covenants around leverage, coverage ratios and distributions. These restrictions mean that any slip in cash generation or earnings from key MENA contracts could tighten financial flexibility just as growth investments and dividend commitments remain in place.
What Current Analyst Assumptions Mean For National Energy Services Reunited
Analyst models around National Energy Services Reunited lean heavily on stronger profitability and a much larger earnings base over the next few years. The core assumptions are clear. Revenue is projected to rise at 22.7% a year and profit margins are expected to move from 6.0% today to 13.0% within three years. Consensus earnings are pegged at US$438.8 million, or US$4.3 per share, by 2029 compared with US$110.0 million in earnings today, although the range is wide with forecasts between US$370.2 million and US$485.9 million. These expectations also build in modest share count growth of 1.34% a year, which matters for you because per share outcomes depend on both profit and dilution.
On those estimates, the stock analysis framework assumes National Energy Services Reunited could trade on a P/E of 11.4x its 2029 earnings, down from 20.4x today and below the cited 19.7x for the broader US energy services group. That P/E compression is doing some of the heavy lifting in the narrative. It implies investors would be paying a lower multiple for a business that analysts expect to be larger and more profitable in absolute terms. A discount rate of 7.66% is then used to bring those future cash flows back to today, which affects any fair value calculation but does not change the underlying execution risk in the Middle East project slate.
Valuation work in the Simply Wall St style report ties those building blocks together. To line up with the analyst consensus, you would need to assume that by 2029 National Energy Services Reunited delivers about US$3.4b of revenue with earnings of roughly US$438.8 million and trades on that 11.4x P/E, using a rounded 7.7% discount rate. Forecast revenue growth and earnings power both hinge on the same factors that shaped the Q3 2026 print: Saudi and Kuwait activity, the 3B3 plan, technology contracts and disciplined use of the new US$747.1 million facilities agreement. Any gap between those operational outcomes and the assumptions embedded in the models would change how compelling the current share price looks relative to the consensus targets.
National Energy Services Reunited's narrative projects about US$3.4b in revenue and roughly US$438.8 million in earnings by 2029, which rests on forecast yearly revenue growth of 22.7% and an earnings increase of about US$328.8 million from US$110.0 million today.
Uncover why National Energy Services Reunited's fair value indicates a 77% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One optimistic twist in the alternate view is how bullish analysts lean on National Energy Services Reunited turning higher recent Q3 and nine month earnings into faster long run expansion. Before this latest report, some were already penciling in about US$3.6b of revenue and roughly US$514.4 million of earnings by 2029. That is a much more assertive trajectory than the baseline, and it shows how far opinions can spread. Use this Q3 dividend backed update as a prompt to compare those upbeat assumptions with your own expectations and to explore several competing narratives rather than relying on a single storyline.
Explore 4 other National Energy Services Reunited fair value estimates, including one that suggests up to 278% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your National Energy Services Reunited research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for National Energy Services Reunited. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate National Energy Services Reunited's overall financial health at a glance.
Looking For More Investment Ideas Beyond National Energy Services Reunited?
If you want to put National Energy Services Reunited in context, it can help to scan a broader watchlist where balance sheets, valuations and income profiles are all laid out side by side. The Simply Wall St Screener lets you filter for traits that match your own risk and return preferences rather than relying on a single story.
- If capital preservation ranks high for you, start with a basket of resilient businesses by reviewing the 29 resilient stocks with low risk scores that can help anchor a more cautious portfolio.
- If dependable financial footing is your priority, focus on companies with cleaner leverage and liquidity profiles by using the list of solid balance sheet and fundamentals (23 results) as a quality filter before you commit fresh capital.
- If you prefer under-the-radar opportunities, widen your search to lesser followed ideas by scanning the 20 high quality undiscovered gems that might deserve a place on your personal watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com