


AI data centers are soaking up chips, pushing consumer electronics prices higher in Asia just as households thought gadgets only ever got cheaper. That twist in the inflation story is creating fresh winners among manufacturers and utilities linked to power hungry computing. This article examines the chipflation theme and highlights 3 stocks from our screener that appear positioned on the favorable side of this shift.
The three companies profiled below are only a sample of the idea. The full screen surfaces 19 more Asian electronics and utility plays linked to chip and data center demand that carry equally compelling narratives. To identify and analyze the highest conviction setups, head straight into the Asia Consumer-Electronics Manufacturers and Utilities Leveraging AI-Driven Chipflation screener.
Dixon Technologies (India) (NSEI:DIXON)
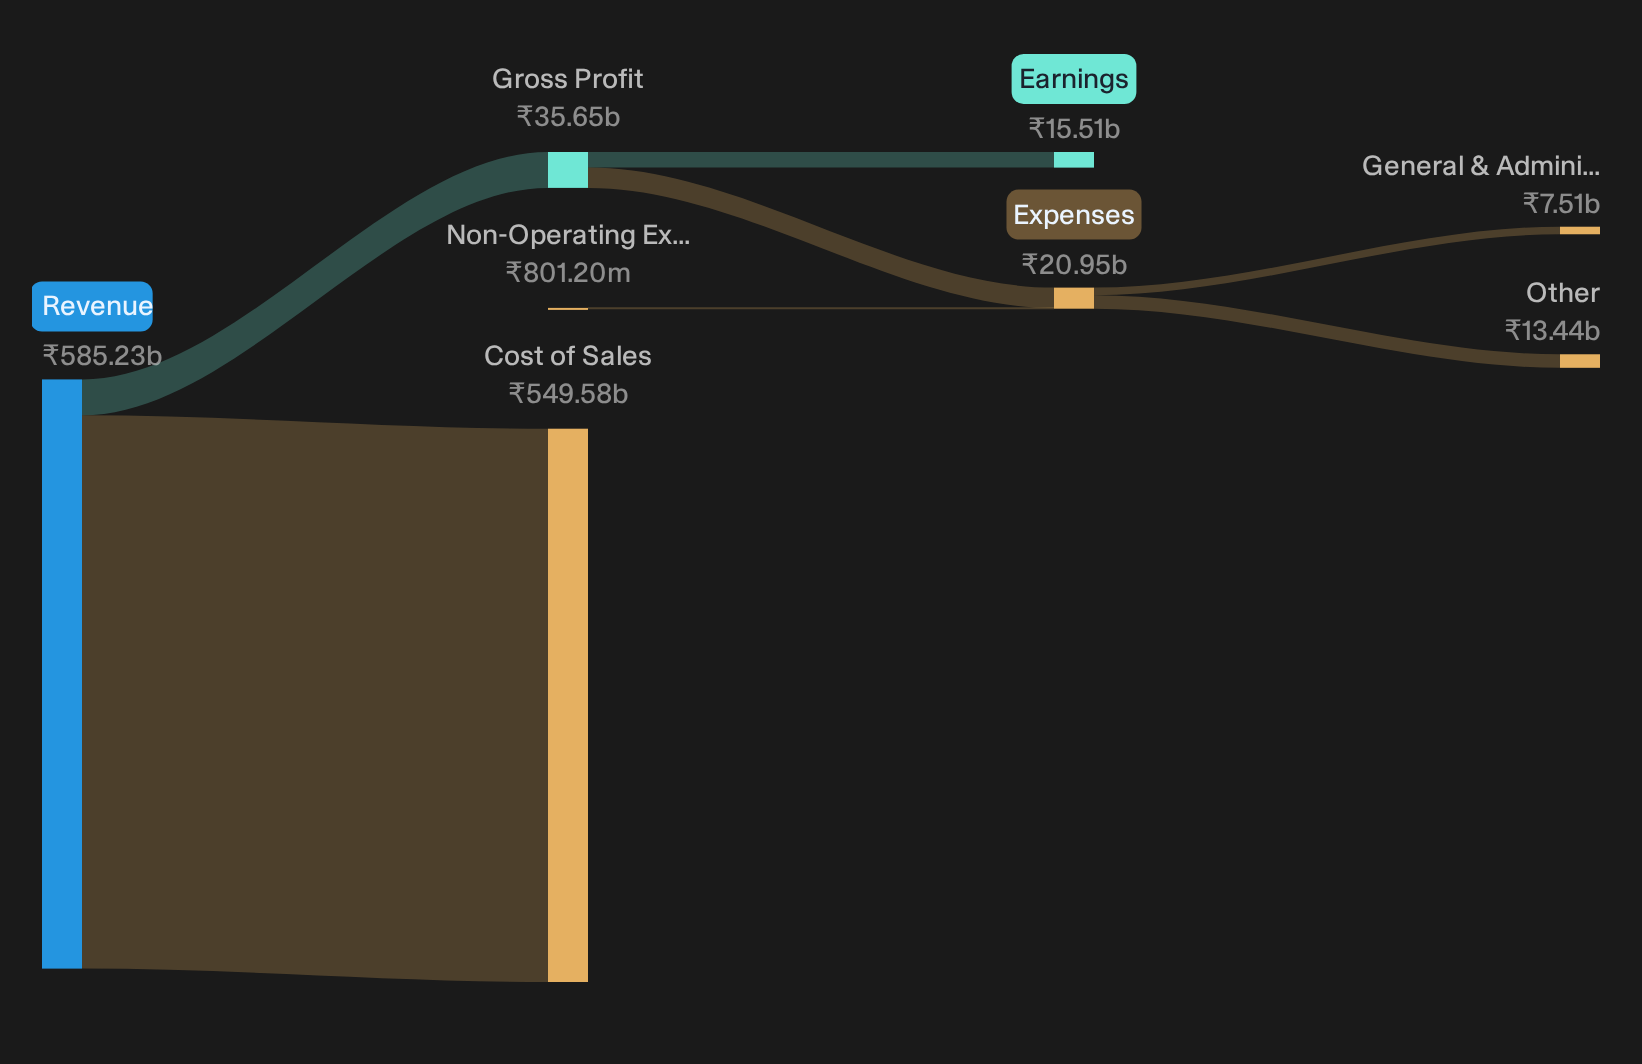
Overview: Dixon Technologies (India) manufactures and assembles TVs, smartphones, appliances and networking gear for big global and Indian consumer electronics brands.
Market Cap: ₹794.7b
Dixon Technologies (India) gives this screener direct exposure to higher-priced TVs, mobiles and connected devices. The analyst consensus Narrative on Simply Wall St highlights how its push into higher value components could change the earnings mix if execution keeps pace with AI-driven chip inflation.
"Ongoing expansions in high value components such as camera modules through the Q Tech JV, where capacity is planned to move from 70 million units annually to around 180 to 190 million units over 15 to 18 months, point to higher value addition within Dixon Technologies (India) and potential support for EBITDA margins once these lines reach scale."
What happens to Dixon Technologies (India)'s margin profile if one unseen pressure on device affordability tightens just as these new lines mature?
If that squeeze on affordability is just the opening act, you will want the full narrative for Dixon Technologies (India) to see how that pressure could accelerate or stall margins.
LG Electronics (KOSE:A066570)
Overview: LG Electronics is a South Korean consumer and commercial electronics giant, supplying TVs, PCs, appliances and auto components worldwide.
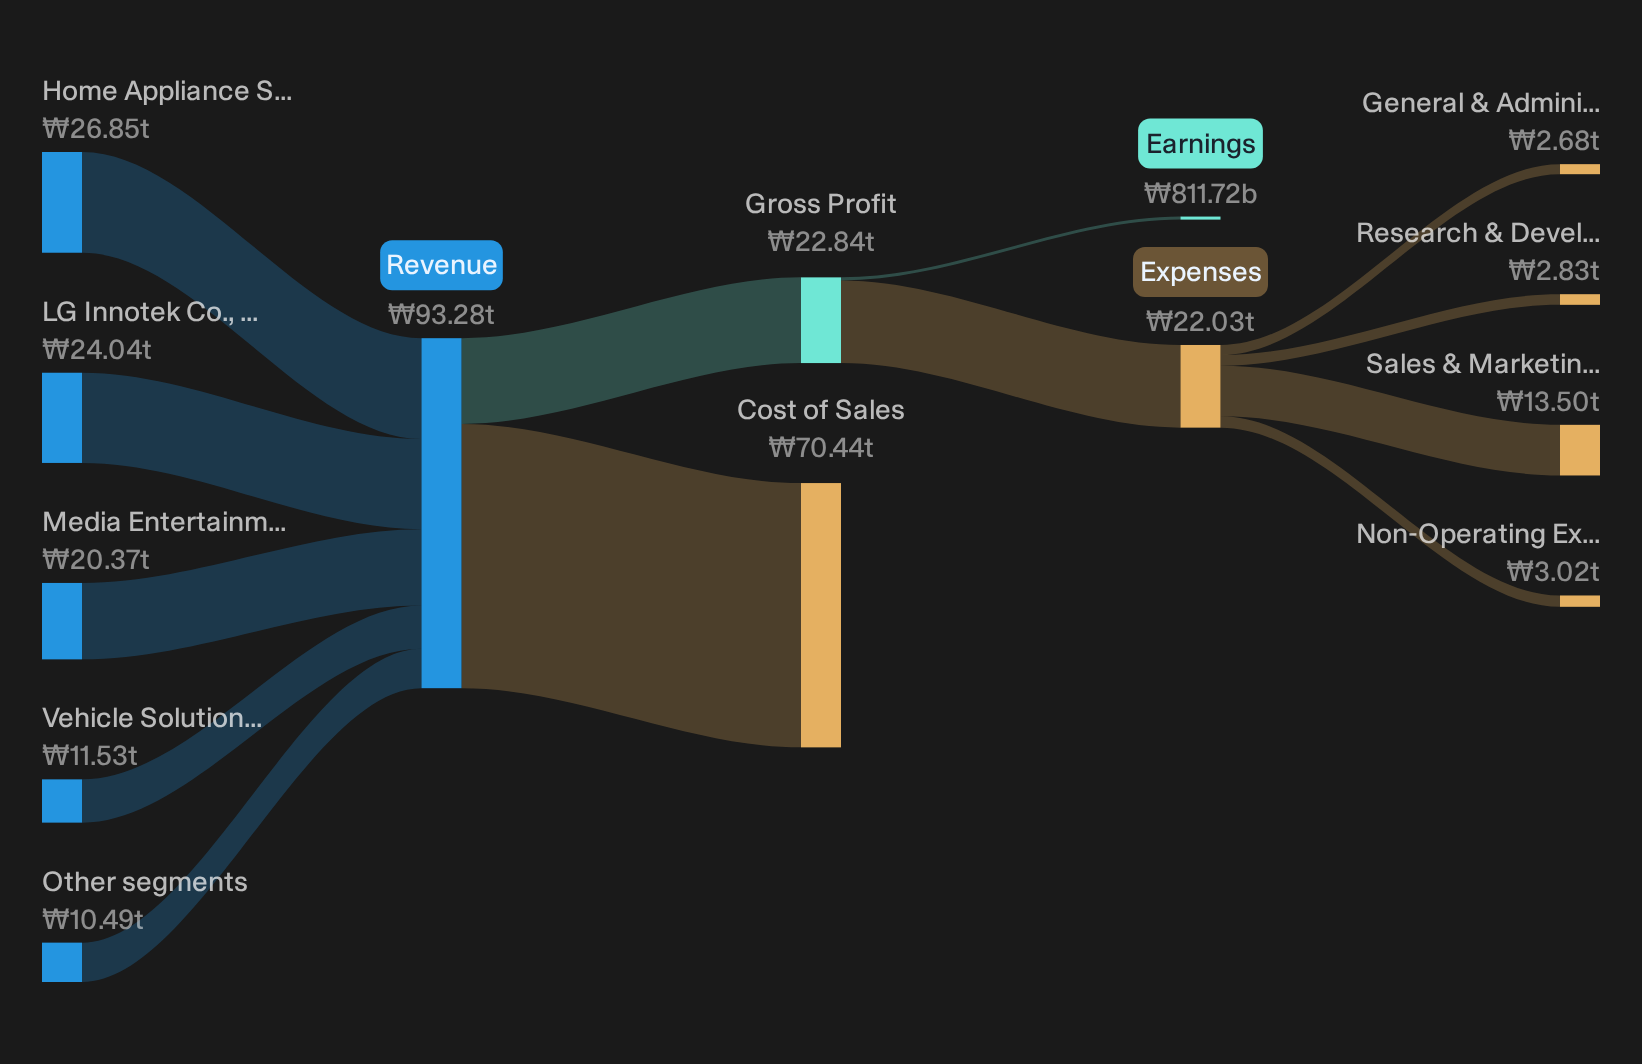
Operations: LG Electronics earns most of its ₩92.5t revenue from Home Appliance Solution ₩26.8t, LG Innotek ₩24.0t and Media Entertainment ₩20.4t segments.
Market Cap: ₩23.2t
LG Electronics sits right on the fault line where AI driven chip shortages meet everyday gadgets, which is why the bearish analyst Narrative on Simply Wall St focuses so heavily on how its consumer hardware and newer service lines absorb that pressure.
"Although LG Electronics is leaning into B2B and subscription services for "qualitative growth," persistent reports of flat to only modestly recovering global demand for core appliances and TVs mean these newer lines may need to carry more of the load than initially assumed."
The real swing factor is whether one emerging AI linked profit stream ramps quickly enough to reshape pricing power and ease cost strain.
If that profit pool proves to be the real growth engine, the full narrative for LG Electronics explains how LG Electronics could decouple earnings from appliance cycles.
PG Electroplast (BSE:533581)
Overview: PG Electroplast is an Indian electronics manufacturing services provider assembling consumer appliances and electronic products for brands that feel chip-driven pricing most.
Operations: PG Electroplast generates around ₹60.98b in revenue from consumer electronic goods and components manufacturing and assembly for third-party brands.
Market Cap: ₹164.6b
PG Electroplast plugs directly into the screener theme because it earns on every outsourced appliance and TV that becomes more expensive when chips and controllers rise in price. This is why the analyst consensus Narrative on Simply Wall St focuses on how volume commitments and outsourcing trends interact with higher electronics pricing.
"Rising outsourcing of room air conditioners to electronic manufacturing services providers, combined with PG Electroplast gaining wallet share with anchor customers and guiding to about 20% unit growth in FY '27 to roughly 2.1 to 2.2 million units with higher average selling prices, could support stronger revenue and operating earnings as fixed costs are spread over a larger volume base."
The real test comes if one cost pressure on those outsourced AC and electronics lines tightens just as that volume and pricing mix peaks.
If that pressure hits just as pricing peaks, the full narrative for PG Electroplast maps how PG Electroplast could convert chipflation into accelerating earnings power with overlooked optionality.

Seeking Fresh Alternatives Before They Fly
Fresh ideas move first. Breakout momentum often appears quiet, then prices are suddenly flying and the clean entry has dropped away. Scan under the radar for now and act now.
- Spot early momentum in smaller names before they get widely talked about by running through the curated 126 elite penny stocks with strong financials while prices and attention are still catching up.
- Target durable cash generators that aim to balance strength and value by using the hand picked list of solid balance sheet and fundamentals (200 results) before the crowd starts bidding them up.
- Position ahead of potential infrastructure tailwinds by reviewing the focused 43 power grid technology and infrastructure stocks while these grid and transmission plays remain largely overlooked.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com