


AI related trade now drives a large share of global goods flows, with AI enabling products responsible for 76% of trade growth in early 2026. Faster globalization and heavy investment in AI infrastructure keep rewarding businesses that can scale quickly and whose leadership is deeply invested in the outcome. This article highlights three fast growing, high insider ownership stocks from our screener that fit this moment.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where insiders and analysts are aligned on the outlook. However, if you want the standouts, these 375 high growth high conviction stocks are the most outstanding.
CoreWeave (CRWV)
Overview: CoreWeave runs a GPU centric cloud platform that powers large scale generative AI workloads, while also offering broader compute and rendering services.
Operations: CoreWeave generates about US$9.9b in revenue from Data Processing, reflecting its focus on AI centric cloud infrastructure services.
Market Cap: US$31.5b
CoreWeave matters for this screener because its AI focused cloud infrastructure is built specifically for high intensity model training and inference. WIn2026, an investor in the Simply Wall St Community, argues that the way this growth is funded could be just as important as the customer demand story.
"The financial structure is heavily weighted toward fixed debt and non-negotiable depreciation cycles. Unlike ORCL or other hyperscalers that have diversified revenue streams and owned infrastructure, CRWV’s viability is tied to a specific hardware cycle."
What happens to CoreWeave’s AI driven growth story depends heavily on how one unseen pressure on future cash generation ultimately resolves.
If that funding squeeze is the real swing factor, the full narrative for CoreWeave outlines how CoreWeave’s leverage, hardware cycles, and AI demand could still align with investors’ interests.
Sansan (TSE:4443)
Overview: Sansan provides cloud tools that turn business cards, contracts, and invoices into shared, searchable data to help companies grow sales efficiently.
Operations: Sansan generates about ¥48.9b from its Sansan and Bill One segment, with total revenue of roughly ¥56.2b earned entirely in Japan.
Market Cap: ¥273.9b
Sansan aligns with this fast growing, high insider ownership theme because its cloud platforms convert everyday customer interactions into recurring, data rich subscription income. The company’s performance depends on how effectively a key shift in customer adoption influences its margins and the durability of its growth.
That shift in adoption is exactly what the 3 key rewards and 1 important warning sign reveals, so you see where Sansan’s momentum could accelerate and where it might quietly stall.

Micronics Japan (TSE:6871)
Overview: Micronics Japan develops semiconductor test equipment and probe cards that support wafer level testing for AI, 5G, and advanced chip production.
Operations: Micronics Japan generates about ¥84.9b from its Probe Card Business and ¥1.4b from TE Business, primarily across Asian semiconductor hubs.
Market Cap: ¥391.6b
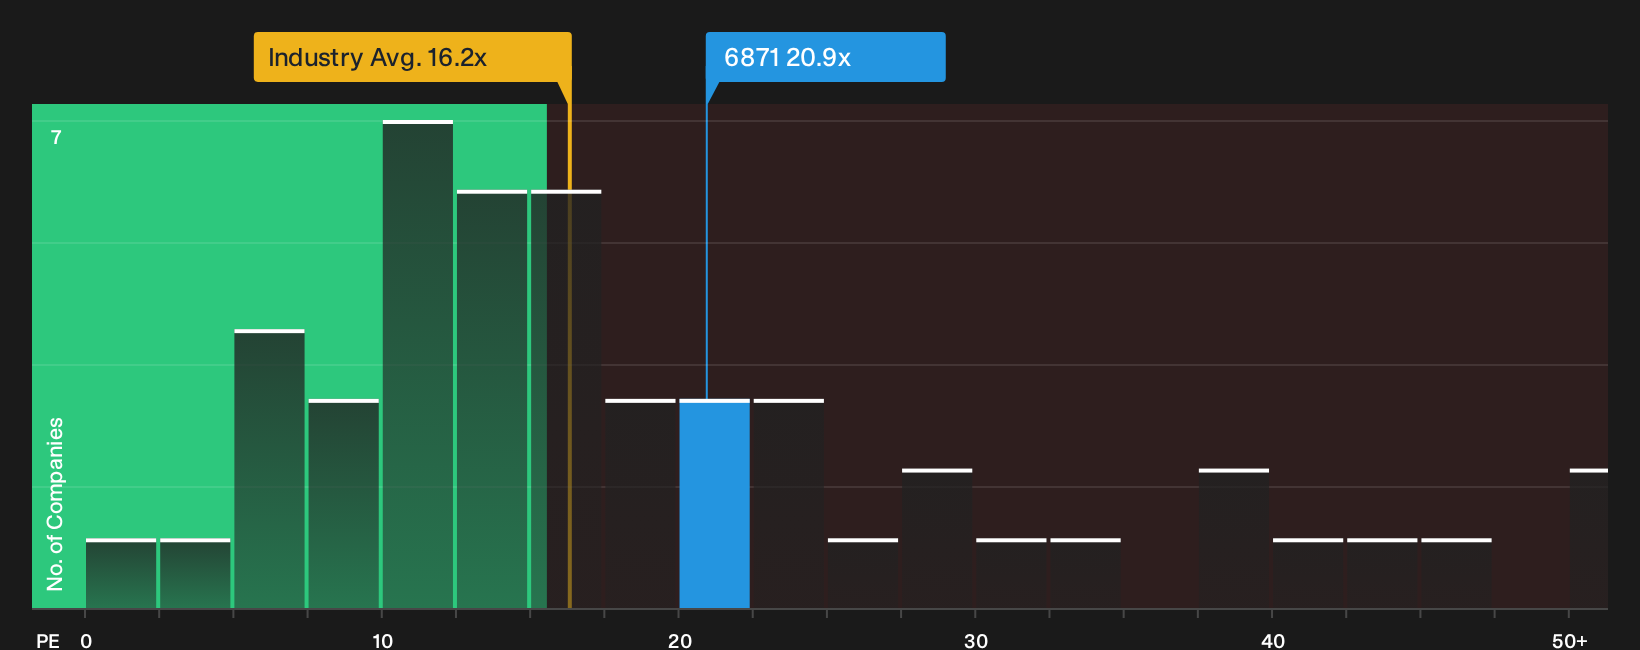
Micronics Japan is directly linked to this fast growing, high insider ownership theme through its probe card and semiconductor testing gear that serve AI and 5G chipmakers, supported by earnings growth that has outpaced the wider Japanese semiconductor group and a P/E multiple above peers that reflects market expectations, although this positioning could change significantly if growth assumptions in that test equipment niche were to shift.
If those assumptions around Micronics Japan’s test equipment growth really are the hinge, the 2 key rewards and 1 important major warning sign shows where expectations could quietly decouple from reality.
Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout stories gain momentum while they are still under the radar for now, and information edge drops fast. Do not delay, get in early.
- Spot under-the-radar value and follow improving momentum with a curated set of 32 high quality undervalued stocks while the rest of the market is still looking elsewhere.
- Back enduring income streams and keep cash flow working for you through a focused group of 6 dividend fortresses before yields get compressed.
- Explore the backbone of AI infrastructure by scanning 53 AI infrastructure stocks that could help power the next leg of computing demand while it still goes largely unnoticed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com