


Expeditors International of Washington (EXPD) is back in focus after reporting higher third quarter and nine month earnings, alongside a new semi-annual dividend of $0.81 per share declared on November 2, 2026.
Recent earnings and the higher semi-annual dividend have arrived against a backdrop of steady share price momentum for Expeditors International of Washington, with the stock delivering a year-to-date share price return of 28.9% and a one-year total shareholder return of 42.8%, indicating that interest has been building rather than fading.
Compare Expeditors International of Washington's earnings momentum and dividend story with a curated group of logistics and transportation players by using our list of solid balance sheet and fundamentals (23 results) to find potential peers with similar financial resilience.
After a near 29% year to date run, Expeditors International of Washington now trades slightly above the average analyst target, while internal fair value work points to a wide discount. Where does a reasonable valuation actually land?
Most Popular Narrative: 4.1% Overvalued
On the analyst consensus Narrative on Simply Wall St, Expeditors International of Washington screens as slightly overvalued, with a fair value of $187.93 versus the last close at $195.67. This frames today’s price as already baking in strong expectations while using a 7.72% discount rate.
The current valuation implies that the share price already reflects a strong outlook for cash generation and capital returns, with limited room for disappointment, given that some commentators view the stock as modestly or fully overvalued.
See why 3 investors see Expeditors International of Washington as 4% overvalued.
Result: Fair Value of $187.93 (OVERVALUED)
Still, if Expeditors International of Washington’s premium P/E relative to US logistics peers unwinds, or recent airfreight strength cools, today’s valuation case could quickly look stretched.
Find out about the key risks to this Expeditors International of Washington narrative.
Another View: DCF Points To Undervaluation
While Simply Wall St’s analyst consensus work frames Expeditors International of Washington as about 4.1% overvalued at $195.67 versus a fair value of $187.93, the SWS DCF model presents a very different picture. On that framework, the stock screens as undervalued, with an estimate of future cash flow value at $306.22 per share. Which lens do you think better reflects the risk you are actually taking?
Look into how the SWS DCF model arrives at its fair value.
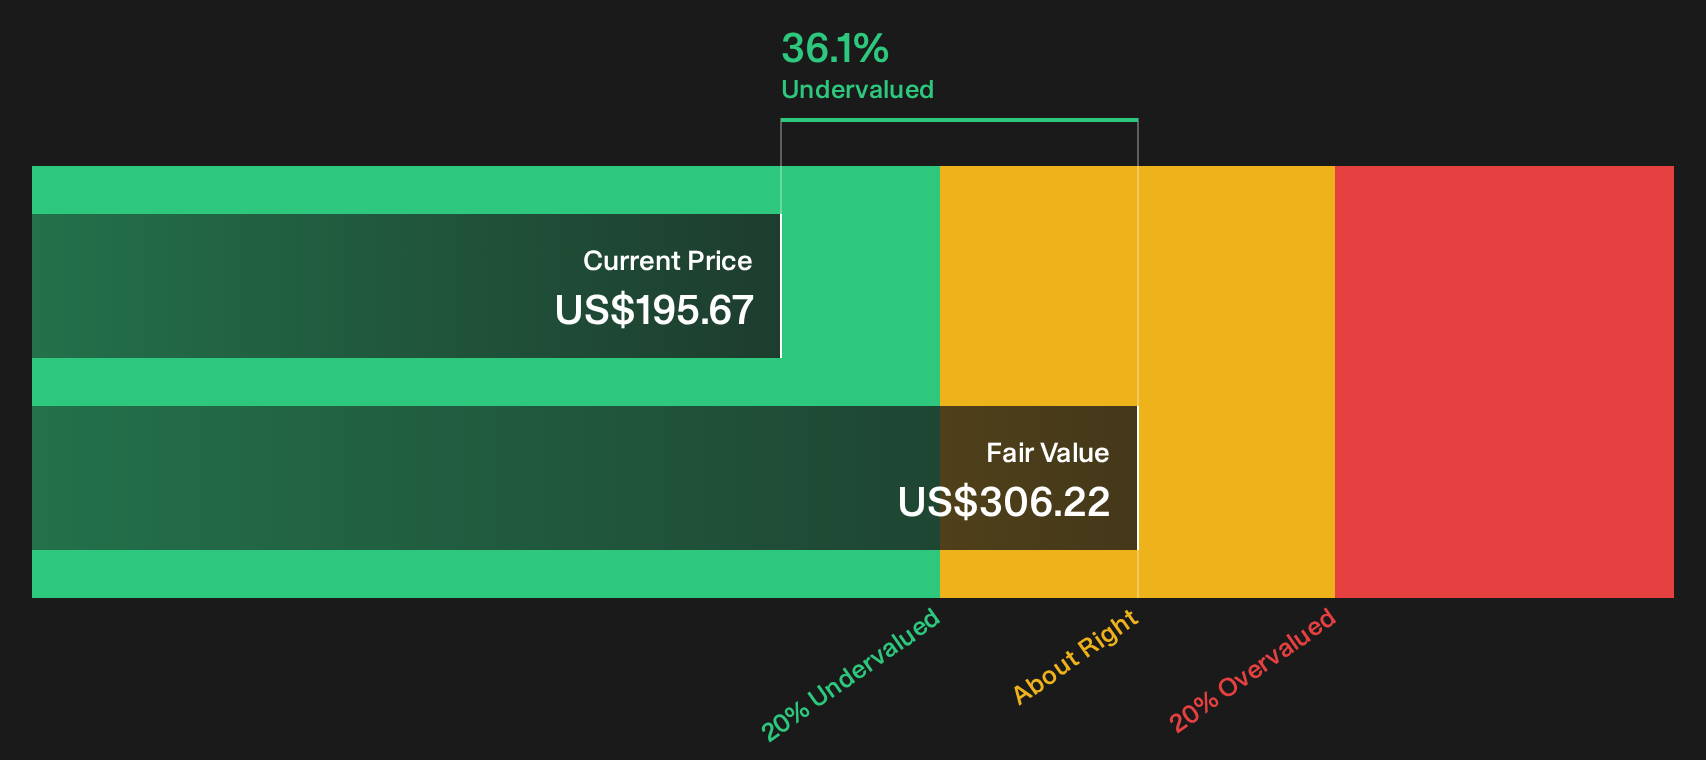
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Expeditors International of Washington for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment looks split on Expeditors International of Washington right now, so act quickly, review the underlying data, and pressure test the bullish angles for yourself by checking the 2 key rewards.
Looking for more investment ideas beyond Expeditors International of Washington?
If Expeditors International of Washington has sharpened your focus on quality, then broadening your watchlist with fresh, well filtered ideas can help you stay one step ahead.
- Target strong fundamentals and resilient balance sheets by reviewing the list of solid balance sheet and fundamentals (23 results), which filters for financially robust companies built to handle tougher conditions.
- Hunt for potential value opportunities early and scan the 20 high quality undiscovered gems, which highlights lesser known businesses with solid financial profiles before the crowd pays attention.
- Prioritise consistency and income potential by assessing the 6 dividend fortresses, which focuses on higher yielding stocks supported by underlying financial strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com