


Why Teradyne’s recent drop and new AI push matter now
Teradyne (TER) is coming off a sharp move, with the stock down about 21% in the week to November 6 as worries around AI regulation and slower data center spending hit semiconductor equipment peers.
The selloff arrived just after Teradyne reported 70% third quarter revenue growth, record Memory and Integrated Systems Test sales, fresh guidance that points to flat fourth quarter trends, and the launch of its Omnyx Edge platform aimed at physical and edge AI hardware.
Set against that steep weekly slide, Teradyne’s recent 7 day share price return of about 24% points to a fast rebound from the selloff. At the same time, a 30 day share price decline of roughly 31% and a 90 day drop of about 37% suggest momentum has cooled after a strong run earlier in the year.
Even with that reset, the stock’s year to date share price return of about 27% and 1 year total shareholder return of roughly 56% indicate that long term holders have still seen substantial gains, supported by product launches like Omnyx Edge and ongoing dividend payments that contribute to overall shareholder outcomes.
Spot 53 AI infrastructure stocks that, like Teradyne, are tied to the buildout of AI compute and edge hardware but are still moving under many investors' radar.After that swing, Teradyne now trades well below the average analyst target and slightly above one recent intrinsic value estimate. Is this reset a bargain, or is it a warning about where fair value really sits?
Most Popular Narrative: 50% Undervalued
Teradyne’s latest close at $263.75 sits well below the bullish narrative fair value of about $528. This frames the recent pullback as a sizable gap to what optimistic analysts think the business could justify. That view comes from the bullish analyst Narrative on Simply Wall St, which leans on the highest analyst targets and more upbeat forecasts rather than a single commentator’s opinion.
AI data-center build-out is widening Teradyne’s wafer to data-center test footprint across compute, memory, storage and board test, which could support a higher long term revenue base as ATE spending tracks a larger share of semiconductor capital investment.
Rising test intensity for complex multi-die AI accelerators and high bandwidth memory is pushing test toward a higher share of semiconductor CapEx. This could give Teradyne incremental pricing power and support gross margin resilience as customers prioritize quality and reliability.
See why 15 investors see Teradyne as 50% undervalued.
Result: Fair Value of $528 (UNDERVALUED)
Still, this bullish Teradyne narrative can crack if hyperscaler AI spending slows more than expected or if lower margin memory testing continues to weigh on profitability.
Find out about the key risks to this Teradyne narrative.
Another View: What Teradyne’s P/E Is Really Telling You
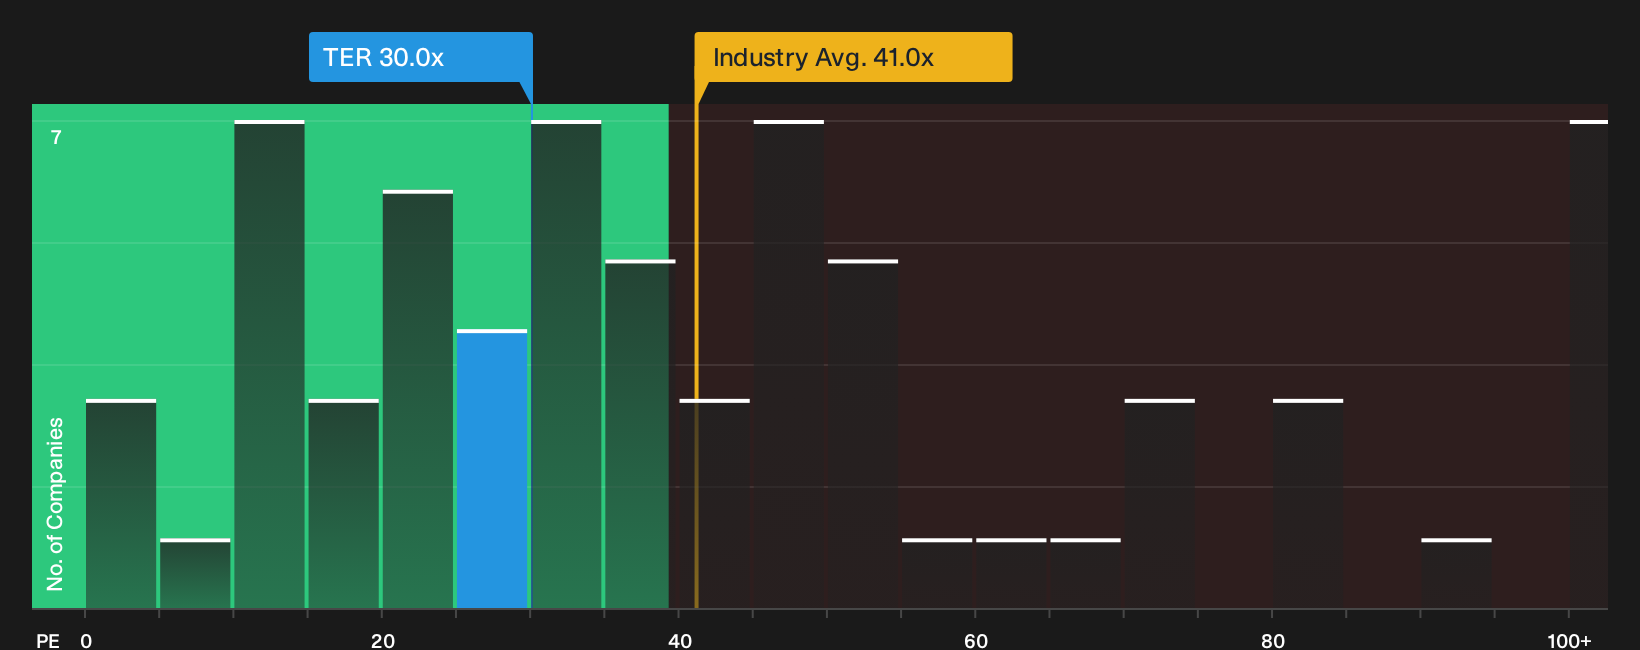
Teradyne’s first narrative leans on bullish analyst fair value, yet the current P/E of about 30x undercuts both the estimated fair ratio of 35.8x and the US Semiconductor peer average of 41x. That gap points to either a cushion or a value trap. Which side do you think it sits on?
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Teradyne for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Teradyne’s story here mixes optimism and concern, and that tension is exactly where thoughtful investors can do their best work if they move quickly and carefully evaluate the full picture for themselves using the 5 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Teradyne?
If Teradyne has sparked fresh thinking, do not stop here. Use Simply Wall Street’s screener to uncover other opportunities that fit your style and risk comfort.
- Target potential value opportunities by reviewing companies that screen as 32 high quality undervalued stocks based on their cash flows and balance sheets.
- Secure your income focus by scanning for 6 dividend fortresses that aim to combine higher yields with resilient payouts.
- Reduce portfolio stress by filtering for 29 resilient stocks with low risk scores that show stronger financial health and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com