


What the latest earnings and dividend reveal
Wynn Resorts (WYNN) just reported third quarter 2026 results that showed lower quarterly revenue and net income compared with a year earlier, alongside growth over the nine month period and a fresh cash dividend declaration.
The headline numbers matter because they give you a split screen. One view shows softer recent trading, with third quarter sales of US$1,311.97 million and revenue of US$1,689.05 million coming in below the prior year period. The other view shows progress over the longer stretch, where sales reached US$4,245.18 million and revenue hit US$5,402.75 million for the nine months ended September 30, both above the levels recorded a year ago.
Profitability followed a similar contrast. Third quarter net income was US$17.32 million, far below the US$88.34 million booked a year earlier, which translated into basic and diluted earnings per share from continuing operations of US$0.17. Across the first three quarters, Wynn Resorts reported net income of US$277.84 million, with basic EPS from continuing operations of US$2.71 and diluted EPS of US$2.58, each higher than the prior year period.
Alongside those figures, the Board continued returning cash to shareholders. Management declared a quarterly dividend of US$0.25 per share, payable on November 30, 2026 to investors on record as of November 16. That payout decision landed on the same day as the earnings release and arrives while the stock is down over the past year but has gained over the past month. This gives shareholders a mix of income and recent price recovery to factor into any assessment of Wynn Resorts today.
Wynn Resorts now trades at US$83.02, with a 30-day share price return of 9.68% that contrasts with a much weaker year-to-date share price return, and a 1-year total shareholder return that has also declined 31.88%.
The earnings release and dividend announcement on November 5 appear to have stirred some interest, with the recent share price rebound hinting at investors reassessing either the company’s earnings trajectory, its income profile, or the risk they are willing to attach to the stock.
Spot fresh ideas by comparing Wynn Resorts with a curated 32 high quality undervalued stocks that pair cash generation, balance sheet strength, and recent share price pressure.Bulls point to Wynn Resorts’ nine month profit and dividend, while bears highlight the weaker quarter and the share price slide over the past year. Which story does the current valuation actually support?
Most Popular Narrative: 31.8% Undervalued
Wynn Resorts closed at $83.02, while the analyst consensus Narrative on Simply Wall St assigns a fair value of $121.65 using a 12.54% discount rate. That gap frames a valuation story built on premium properties, capital projects, and future cash flow.
Expansion of Wynn Resorts' premium-focused footprint through the Enclave tower at Wynn Palace, which is planned to add 432 all-suite rooms and materially increase room and suite capacity in Macau, could support higher gaming and non-gaming revenue once ramped. Management estimates point to roughly US$400 million of incremental gross gaming revenue and US$150 million to US$175 million of EBITDA.
See why 31 investors see Wynn Resorts as 32% undervalued.
Result: Fair Value of $121.65 (UNDERVALUED)
Still, the story can change quickly if rising labor and operating costs, or ongoing disruption at Encore Boston Harbor, keep squeezing Wynn Resorts’ margins and cash generation.
Find out about the key risks to this Wynn Resorts narrative.
Another View: What Wynn Resorts' P/E Is Telling You
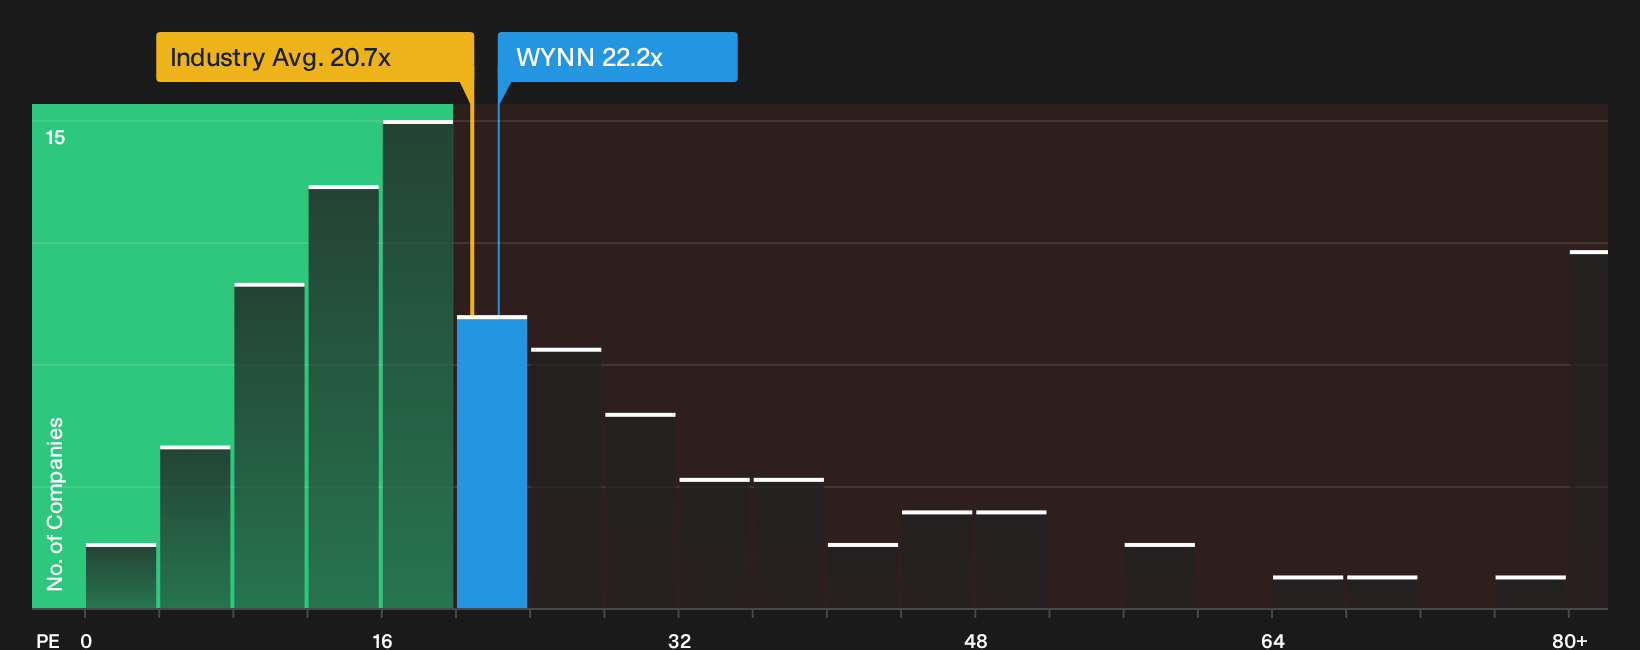
The DCF work presents Wynn Resorts as undervalued, yet the market’s simple P/E check sends a very different signal. At 22.2x earnings, the stock trades richer than both the US Hospitality group at 20.7x and its own 21.1x fair ratio. That richer tag can either compress or hold if sentiment or earnings shift from here.
Numbers like these do not give a single right answer, but they do frame risk. A premium P/E with a low value score of 3/6 suggests less room for disappointment than the DCF implies. The question is which signal matters more for your process: the income-driven fair value, or the shorter term multiple that peers trade on.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on Wynn Resorts so far, right. If you want to move fast and rely on your own judgment, start by weighing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Wynn Resorts?
If Wynn Resorts has sharpened your focus today, do not stop there. Broaden your watchlist now so you are not catching up after the next move.
- Target resilient cash generators that still look out of favor using our 32 high quality undervalued stocks.
- Prioritize income by scanning for companies built around robust payouts with the 6 dividend fortresses.
- Tilt toward stability and stronger financial footing by running a list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com