


Helios Technologies guidance reset gives investors fresh reference points
Helios Technologies (HLIO) just tightened the story for 2026, pairing a raised full year sales outlook of US$895 million to US$902 million with fresh fourth quarter revenue guidance of US$205 million to US$212 million.
Helios Technologies shares have come under heavy pressure, with the 30 day share price return down 31.34% and the 90 day move down 41.48%, even though management raised 2026 sales guidance after reporting higher quarterly sales and earnings year on year. At the latest share price of US$47.69, short term momentum looks weak, while the 3 year total shareholder return of 15.06% contrasts with a much lower 5 year total shareholder return of 56.74%, highlighting how sharply sentiment has swung over different timeframes.
Compare Helios Technologies to other industrials that have been hit hard yet still screen well on quality and valuation by scanning the 32 high quality undervalued stocks.
Helios Technologies now trades at a steep discount to both analyst targets and some intrinsic value estimates after a sharp sell off. Is that gap a cushion, or a clear warning on market caution?
Most Popular Narrative: 46% Undervalued
On the analyst consensus Narrative on Simply Wall St, Helios Technologies screens as materially undervalued, with a fair value of $87.67 against the latest close at $47.69. That framework leans heavily on forecasts for revenue, margins and cash generation under a single discounted cash flow style view.
The main priority is that Helios converts its recent margin gains and cash generation into sustained operational efficiency and disciplined capital allocation, including footprint actions, automation investments, and a continued balance between reinvestment, acquisitions, and shareholder returns.
Strong free cash flow, evidenced by record Q2 2026 operating cash flow of US$42 million and free cash flow of US$31 million, together with net debt-to-EBITDA at 1.4x, gives Helios Technologies room to increase capex, pursue acquisitions, and return more capital to shareholders. This can influence future EPS and support higher cash returns.
See why 6 investors see Helios Technologies as 46% undervalued.
The valuation work in that Narrative applies an 8.73% discount rate to analysts' forecasts and arrives at a fair value that is about 46% above the current share price. At a high level, that gap reflects expectations for earnings to reach $112.0 million by about 2029, with profit margins moving from 8.7% to 11.1% and a future P/E of 31.9x on those earnings.
Price targets inside the same framework are not tightly clustered. The highest analyst fair value is $110 and the lowest is $65, which shows a wide range of views on how far Helios Technologies can push margins and how much investors might eventually be willing to pay for that earnings profile.
For readers who want to stress test those assumptions themselves, it helps to focus on three levers. First, whether revenue can reach the $1.0b mark implied by the Narrative. Second, whether the mix shift toward electronics and electro hydraulic solutions can support the margin step up that is baked into the model. Third, whether a P/E of 31.9x in 2029 feels realistic compared with the current US Machinery industry level of 23.2x.
Result: Fair Value of $87.67 (UNDERVALUED)
Still, Helios Technologies faces real pressure if cyclical end markets stay weak and if traditional hydraulics lose share faster than electronics and electro hydraulic offerings can expand.
Find out about the key risks to this Helios Technologies narrative.
Another View: What Helios Technologies' P/E Is Really Saying
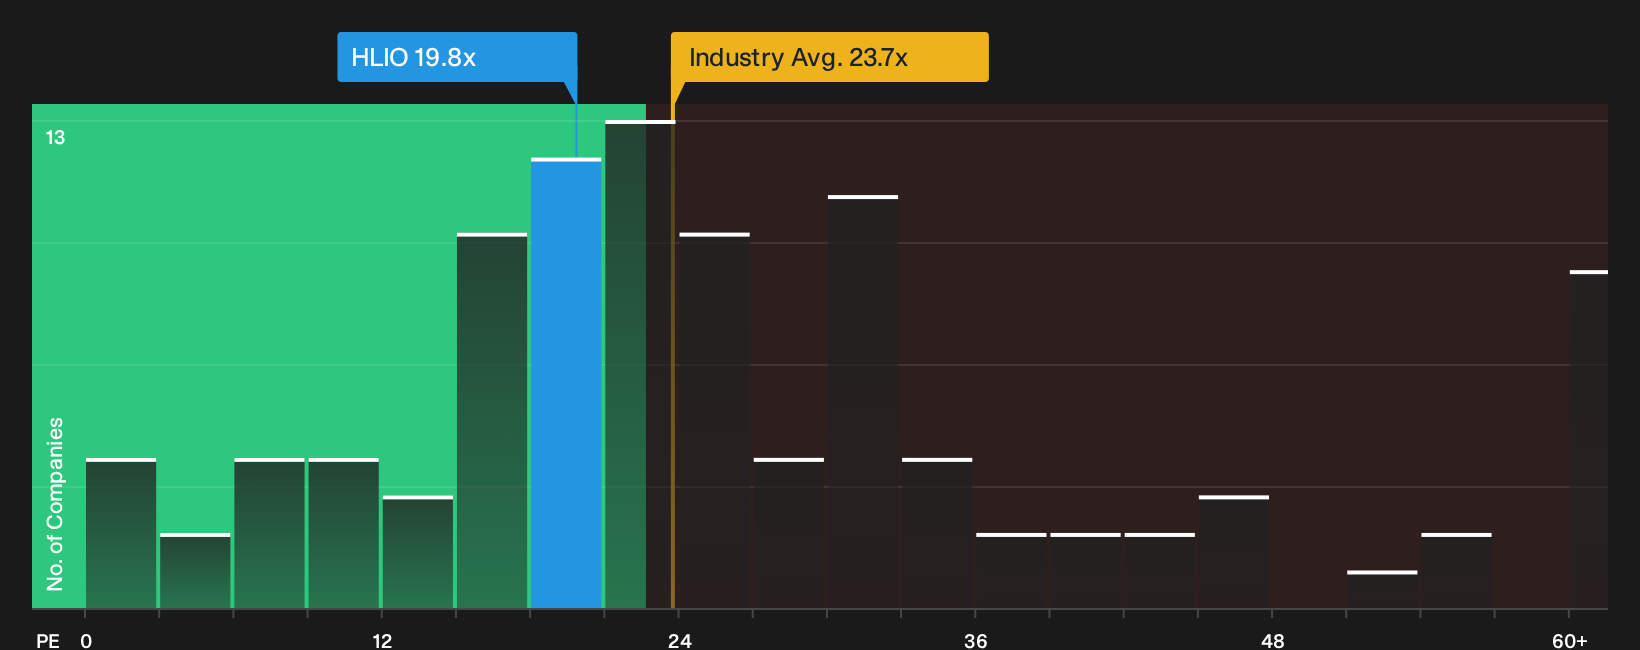
The DCF style framework paints Helios Technologies as materially undervalued, yet the simpler P/E lens tells a tighter story. HLIO trades on a 19.8x P/E. That is slightly above its own fair ratio of 19.1x and above peer averages at 18.1x, although still below the broader US Machinery sector at 23.8x. In practice, that points to a stock that already embeds some quality premium, with less obvious room for multiple expansion if earnings or sentiment falter.
With one model flagging a 50% discount to future cash flow value and the P/E picture looking far more balanced, which signal do you trust more for your own process: the narrative rich model, or the blunt multiple comparison? And how much conviction do you really have in those long term forecasts to back it?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment across Helios Technologies is mixed, which is exactly why it pays to move fast, review the numbers yourself, and reach your own verdict. To see the key upsides investors are focused on, take a close look at the 3 key rewards.
Looking for more investment ideas beyond Helios Technologies?
If Helios Technologies has you rethinking your watchlist, use this moment to widen the lens and hunt for opportunities that better fit your risk and return preferences.
- Target income resilience by scanning companies with stronger payouts and balance sheet support through the 6 dividend fortresses.
- Hunt for mispriced quality by filtering for businesses that pair solid fundamentals with appealing valuations using the 20 high quality undiscovered gems.
- Prioritize capital protection by focusing on businesses that carry lower risk profiles through the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com