


Golden cross event puts OneSpaWorld Holdings in focus
A recent golden cross in OneSpaWorld Holdings (OSW), where its 50 day moving average moved above the 200 day trend, has pulled fresh attention to the spa operator's shares.
The technical shift follows a 33.5% gain over the past month, alongside improved earnings estimates for the current quarter that keep investors watching how this cruise and resort wellness business executes.
Momentum in OneSpaWorld Holdings has been building, with a 27.2% 30 day share price return and a 48.7% year to date share price gain contributing to a 46.6% 1 year total shareholder return and a 180% 3 year total shareholder return.
Scan for other potential momentum breakouts with a similar technical and earnings backdrop to OneSpaWorld Holdings by reviewing the curated 32 high quality undervalued stocks in the same session.
So is OneSpaWorld Holdings’ sharp move a clean read on a steadily expanding wellness business, or mostly a burst of optimism that pushed the price up faster than the fundamentals? The valuation picture has to answer that.
Most Popular Narrative: 6% Undervalued
On the numbers, the analyst consensus Narrative on Simply Wall St puts OneSpaWorld Holdings’ fair value at $32.60 against a last close of $30.69. This frames the golden cross within a story of modest undervaluation built on cruise wellness growth and cash generation assumptions.
For OneSpaWorld, analysts expect expanding cruise partnerships, a growing ship count and a richer mix of wellness and medi-spa services to be associated with higher revenue and earnings over time.
The main factor is that medi-spa services, AI tools across the fleet and rising prebooked service volumes are expected by analysts to be associated with higher revenue per guest and better margins without offsetting cost pressures.
See why 5 investors see OneSpaWorld Holdings as 6% undervalued.
Result: Fair Value of $32.60 (UNDERVALUED)
Still, the OneSpaWorld Holdings story can be challenged if cruise traffic is disrupted or if resort and product softness offsets shipboard momentum and pressures earnings.
Find out about the key risks to this OneSpaWorld Holdings narrative.
Another View: OneSpaWorld Holdings Looks Expensive On Earnings
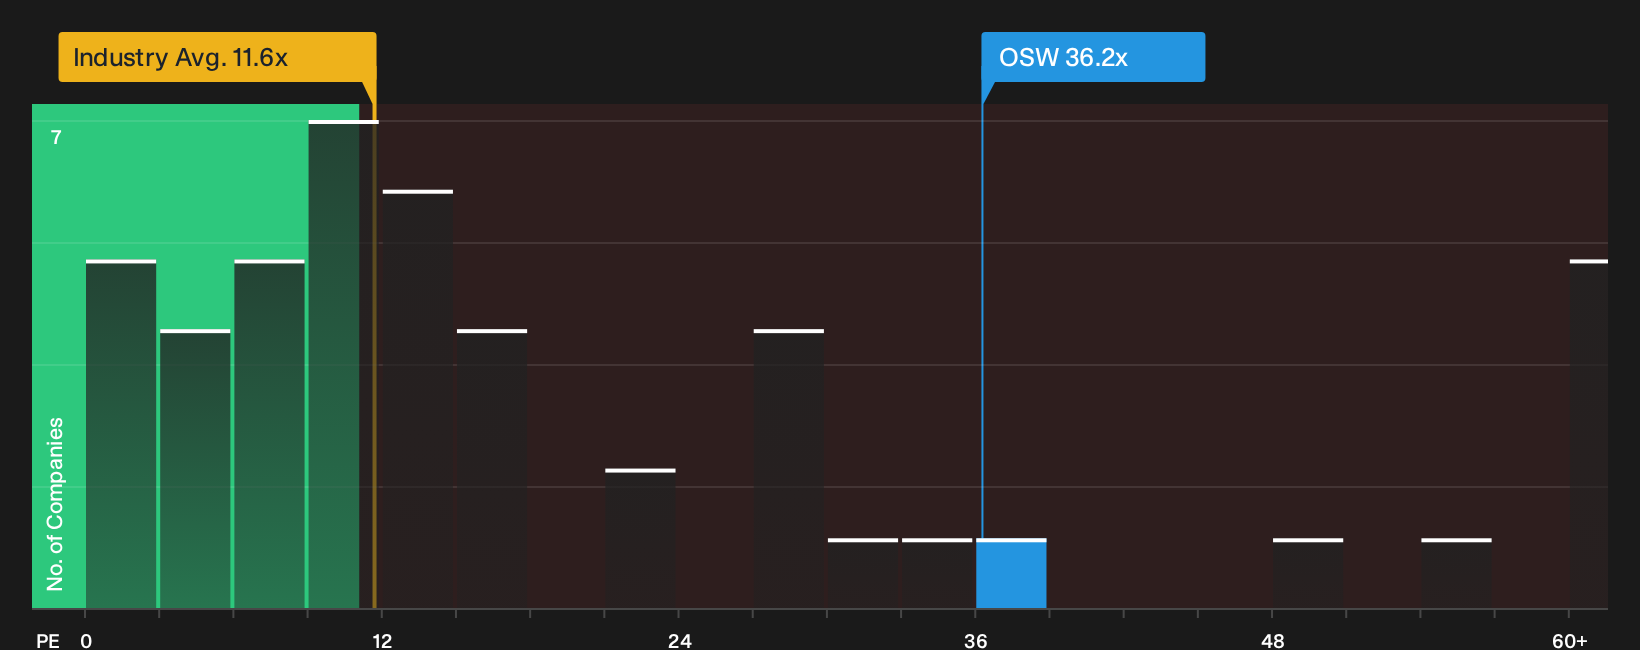
The first story paints OneSpaWorld Holdings as 6% undervalued on future cash flows. However, its current P/E of 36.2x is far richer than both the US Consumer Services industry at 11.8x and peers at 13.7x, and is also well above a fair ratio of 20.6x. Is that gap a premium worth paying or a valuation risk waiting to be repriced?
See what the numbers say about this price in more detail by reviewing the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around OneSpaWorld Holdings feels familiar, use it as a prompt to move quickly and review the data directly. Then weigh the upside alongside the weak spots by working through the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond OneSpaWorld Holdings?
Do not stop with OneSpaWorld Holdings. Use this momentum as a springboard to scan fresh opportunities that match your risk profile and return goals.
- Target potential mispricings by reviewing the 32 high quality undervalued stocks that combine solid fundamentals with prices that may not fully reflect their financial strength.
- Build a steadier core by checking the 29 resilient stocks with low risk scores that aim for resilience when markets turn rough.
- Spot future leaders early by assessing the 20 high quality undiscovered gems before they hit everyone else's radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com