


Why Wendy's stock is back in focus after a rejected buyout
Wendy's (WEN) has swung back into the spotlight after rejecting a roughly $1.4 billion takeover proposal from an investor group led by Nelson Peltz and putting a poison pill in place.
The refusal of the bid, plus the cancelled plan to acquire the remaining 83.70% stake in Wendy's, signals that the board sees more value than the offer implied and is willing to defend control. That matters for you if you are weighing takeover speculation against fundamentals.
At a share price of US$8.18, Wendy's has seen a sharp 28.82% 1 month share price return as takeover headlines and a fresh quarterly earnings release hit the tape. However, the 1 year total shareholder return is slightly negative and the 5 year total shareholder return shows a steep decline, suggesting short term momentum has picked up while longer term holders have yet to fully recover.
See how Wendy's compares with other potential targets by applying the same takeover and value thesis across our curated list of 32 high quality undervalued stocks in similar consumer-facing industries.
The rejected bid, the poison pill and a 29% one month jump now collide into a simple issue for Wendy's investors: Does the current price still leave enough upside to justify the takeover risk and recent earnings wobble?
Most Popular Narrative: 2% Overvalued
On the analyst consensus Narrative on Simply Wall St, Wendy's fair value sits at $8.04, just below the last close at $8.18. This frames a tight valuation gap for anyone eyeing the rejected bid and current price.
The numbers imply the share price reflects significant skepticism that Wendy's can execute its turnaround plan, improve U.S. traffic, and grow into the international and digital investments the company is currently funding.
See why 28 investors see Wendy's as 2% overvalued.
Result: Fair Value of $8.04 (OVERVALUED)
Still, pressure on U.S. franchisee economics and inflation in key inputs like beef could undercut Wendy's turnaround plan and keep recent momentum fragile.
Find out about the key risks to this Wendy's narrative.
Another View: What Wendy's P/E Is Saying
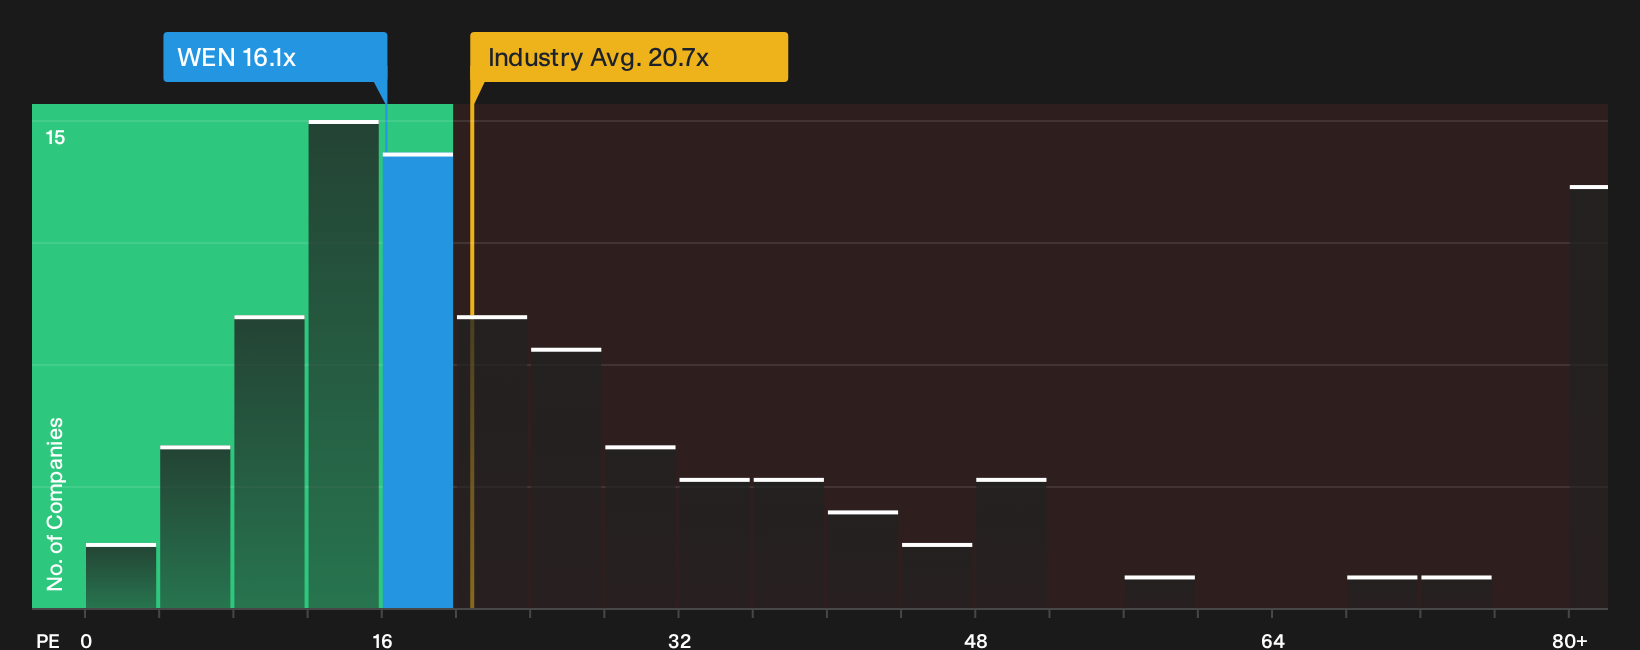
Where the analyst narrative pegs Wendy's as about 2% overvalued on fair value of $8.04, the market’s own yardstick tells a looser story. At a P/E of 16.1x, Wendy's trades well below the US Hospitality average of 20.7x and under the 18.5x fair ratio estimate.
That gap suggests investors are pricing in more risk around execution and debt than either peers or the fair ratio imply, even after the rejected buyout and recent rally. The question is simple for you now: Is that discount a margin of safety, or a warning sign about how fragile the turnaround could be?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Wendy's story so far. Act while the data and sentiment are fresh, weigh the risks against the potential rewards, and ground your own thesis using the 3 key rewards and 3 important warning signs.
Looking for more ideas beyond Wendy's?
If you stop with Wendy's, you only see one angle. Cast the net wider with screeners that surface different types of opportunities tailored to your risk and income goals.
- Target resilience by reviewing companies that pass strict balance sheet filters through our list of solid balance sheet and fundamentals (23 results).
- Pursue reliable income by focusing on companies in the 6 dividend fortresses that pair higher yields with supporting fundamentals.
- Hunt for future standouts by scanning the 20 high quality undiscovered gems before wider attention and capital arrive.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com