


Realty Income has delivered a solid multi year return, which puts fresh focus on whether the current share price at around US$59 is properly supported by the earnings behind it. With new expansion moves reshaping the business, the key issue for you is how much of that story is already reflected in the multiple investors are paying today.
- Over the past 3 years the stock has returned about 31.7%, which raises the question of how much future earnings strength is already embedded in that gain.
- Management is pushing harder into Europe, industrial properties, data centers and private funds, which can reshape expectations for long term cash generation and the level of earnings the current valuation assumes.
- Your read on Realty Income is one view; the desks covering it have another. See what analysts think Realty Income's shares could be worth.
The issue now is whether Realty Income's current share price is justified by the earnings power that investors can reasonably expect from this expanded portfolio.
If you want to test the same earnings question you are asking of Realty Income across a wider field of potential ideas, scan through the 32 high quality undervalued stocks.
Has Realty Income Run Too Far on Earnings?
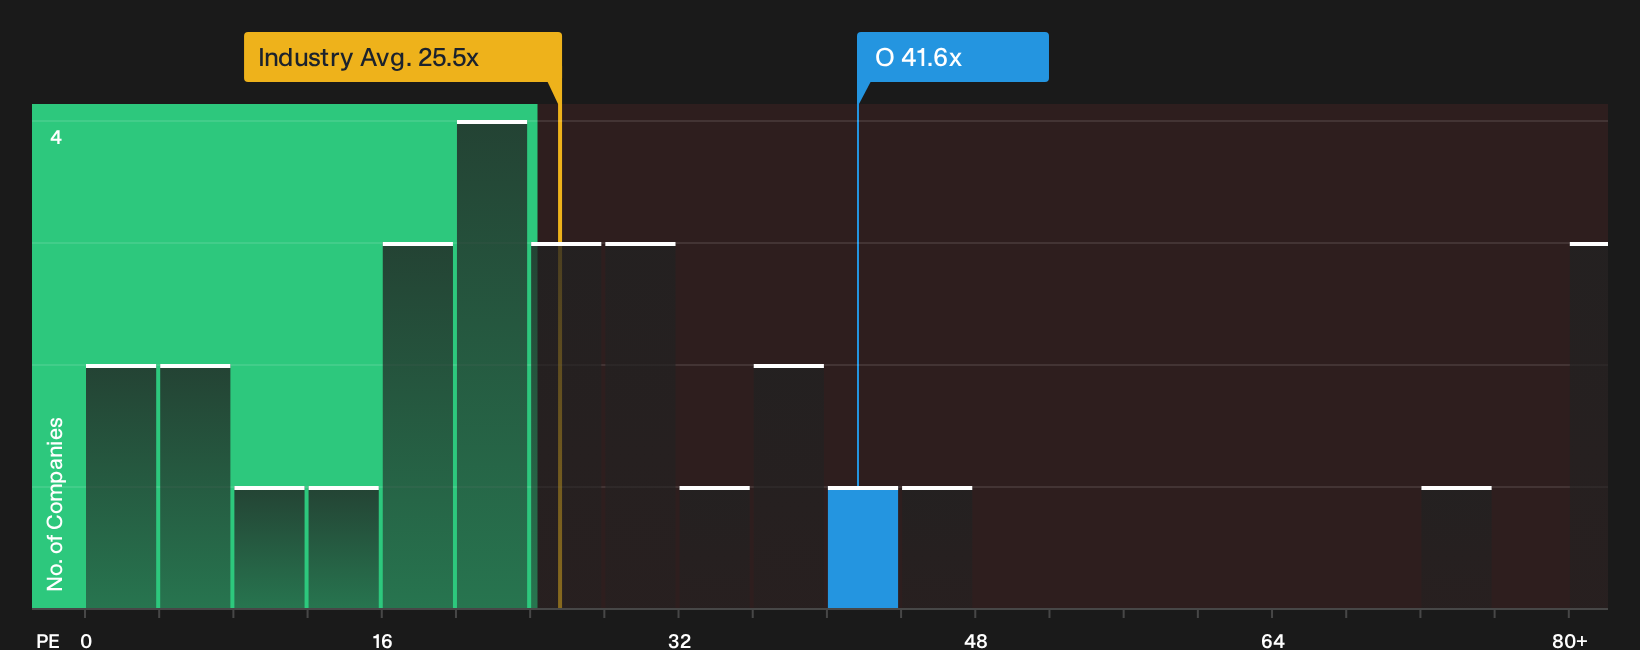
The P/E ratio fits Realty Income because earnings remain the core yardstick most investors use to frame a net lease REIT. At roughly 41.6x earnings, the stock trades well above the Retail REITs sector average of about 25.5x and also ahead of the peer group on roughly 26.5x. That means each dollar of Realty Income earnings currently carries a steeper price tag than many comparable landlords.
On a more tailored view that blends its growth profile, margins, market size and risks, the multiple sits above the level the fair value model would usually assign, which screens the shares as overvalued on this P/E lens. Because the 2026 AFFO guidance was raised on the back of European and industrial expansion, investors appear willing to pay a premium for that earnings stream even relative to other retail focused REITs. If you are weighing whether that premium still makes sense at around US$59, it helps to compare this headline P/E against the detailed fair multiple and cash flow work in the tool behind it. Explore the numbers behind Realty Income's P/E valuation.
The Realty Income Narrative: What Would Justify Today's Price?
Simply Wall St Narratives give you a structured way to answer the question that hangs over Realty Income's valuation work you just saw, by spelling out which future paths for growth, margins and earnings would need to play out for the shares to be worth materially more or less than today. Each one anchors its number to a clear view on how Realty Income's expansion, profitability and risk profile might evolve, so you can revisit those assumptions as fresh information emerges on the Community page.
One of the top community narratives on Realty Income: roughly fairly valued
According to andre_santos, a Simply Wall St Community investor who wrote this Narrative, Realty Income is best considered through its dividend profile.
"Given the fact that Realty Income is a dividend focused company, I will value it using only valuation methods related with dividends…"
Discover why this Narrative puts Realty Income at roughly fairly valued.
Before acting on Realty Income's valuation, there is one more angle worth checking
Price, cash flow and yield only tell you so much when you do not yet know who is steering Realty Income or how their incentives line up with yours. See who runs Realty Income and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com