


- AL Sydbank reported third quarter 2026 net interest income of DKK 1,764 million and net income of DKK 1,072 million, with nine month figures of DKK 5,265 million and DKK 2,833 million respectively.
- Despite higher net interest income and net income over both periods, AL Sydbank's basic earnings per share from continuing operations were lower than a year earlier, which points to changes in share count, costs, or mix that investors will need to unpack.
- Attention now turns to how AL Sydbank's net interest income performance, alongside lower earnings per share, influences the broader investment narrative for the bank.
See how AL Sydbank's earnings story compares with other banks that pair strong balance sheets with resilient income streams by checking our hand picked list of solid balance sheet and fundamentals (200 results)
What Is AL Sydbank's Investment Narrative?
AL Sydbank asks you to believe in a fairly simple story. A traditional bank, focused on Danish clients, trying to convert solid net interest income into consistent per share value. The latest quarter fits that picture only partly. Net interest income and net profit are higher than a year ago, yet basic EPS is lower, and margins sit at 22.1% compared with 33.2%. That combination suggests you are paying for strong activity and volume, while accepting some dilution and a less efficient bottom line.
In the short term, the key driver remains how AL Sydbank manages credit quality, funding costs, and any further one off items after the DKK 2.7b loss flagged in the 12 month figures to 30 September 2026. The bank is running with a 2.5% bad loan ratio and a 64% allowance, so loan performance and provisioning choices matter more than headline growth. The recent earnings release reinforces that tension, because stronger income is clear while per share earnings pressure and prior dilution sit in the background.
Yet all of that sits next to one uncomfortable detail that could matter far more if conditions turn just a little...
There's only one way to know the right time to buy, sell or hold AL Sydbank. Head to Simply Wall St's company report for the latest analysis of AL Sydbank's Fair Value.
Exploring Other Perspectives
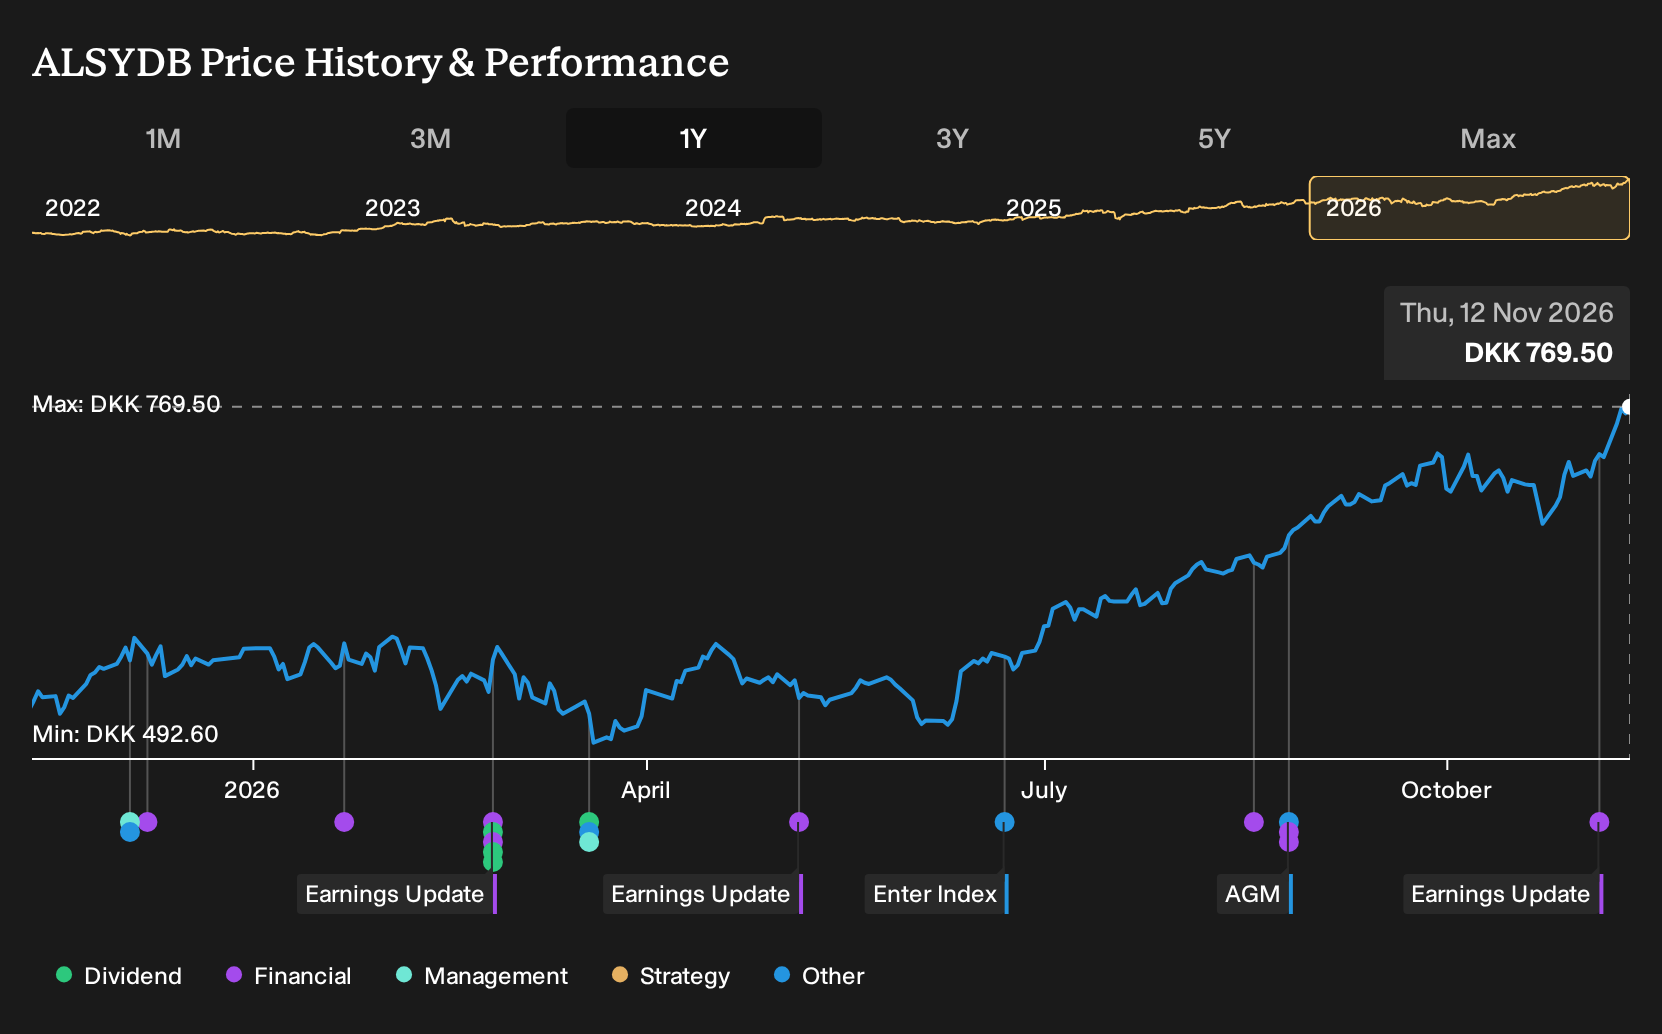
Two fair value estimates from the Simply Wall St Community span roughly DKK 812 at the low end to about DKK 1,280 at the high end, which already shows how wide opinions on AL Sydbank can run. Those views were formed before the latest earnings report, so you may want to revisit them in light of the recent EPS pressure.
Explore another AL Sydbank fair value estimate, including one that suggests it could be worth just DKK812.00.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your AL Sydbank research is our analysis highlighting 3 key rewards and 6 important warning signs that could impact your investment decision.
- See our latest analysis for AL Sydbank. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AL Sydbank's overall financial health at a glance.
Looking For More Investment Ideas Beyond AL Sydbank?
If AL Sydbank's latest earnings have sharpened your focus on balance sheets, income resilience, and valuation, it can be useful to compare that story with other listed businesses that share similar strengths or offer a very different profile.
- For investors who want potential upside with strict attention to financial strength, consider reviewing a 205 resilient stocks with low risk scores that combine resilience with measured risk.
- If reliable income is your priority, you can scan for companies that prioritize steady cash returns to shareholders through our 216 dividend fortresses built around higher yielding payers.
- If you prefer opportunities that the market may not be fully focused on yet, filter for quality fundamentals using a curated 565 high quality undiscovered gems that still fly under most radars.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com