


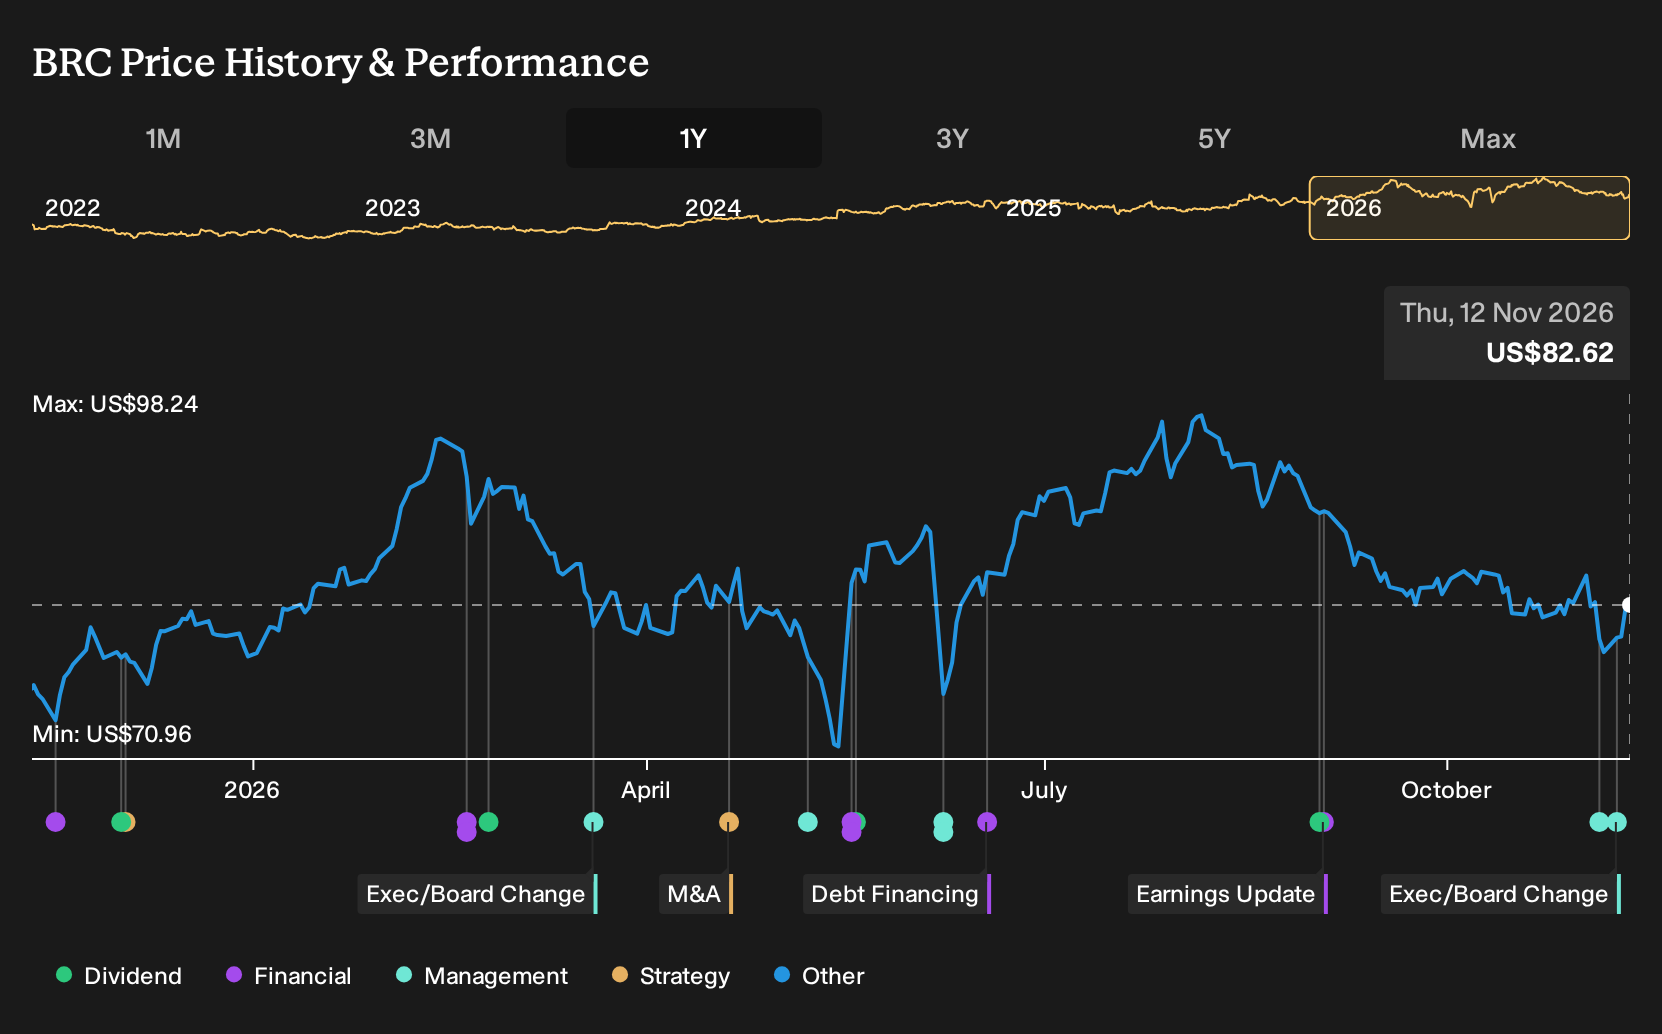
- Brady Corporation reported that Scott J. Robinson and Kenneth J. Spangler joined its Board of Directors in November 2026, while long serving director Pat Allender retired after 19 years of service.
- Following a share exchange, Dr. Bruno now controls more than 50% of Brady’s voting power. The Board plans to keep applying full NYSE corporate governance standards rather than using controlled company exemptions.
- We will now look at how Brady’s controlled company status and refreshed board could influence the existing IPS focused investment narrative.
Brady Investment Narrative Recap
To own Brady, you need to believe the identification and workplace safety specialist can keep turning its R&D spend and the IPS acquisition into higher quality earnings over time. The analyst consensus Narrative on Simply Wall St frames IPS integration and cost synergies as the key near term swing factor, with inflation in electronics and diesel still a pressure point for margins.
The controlled company status and new directors do not materially change those operating drivers in the short term. The biggest operational risk remains slower than expected IPS margin improvement combined with higher leverage from roughly US$1.3b of new debt, which could restrict future capital returns if cash generation disappoints.
The most relevant recent update is Brady confirming that, even after Dr. Bruno gained over 50% voting power, the Board plans to keep following full NYSE corporate governance standards. For an investor focused on IPS execution, that matters because committee independence and oversight around compensation, capital allocation and integration targets remain in place.
Brady also removed Dr. Bruno from committees that must be composed of independent directors, which keeps a formal check on related party risk and major decision making. That structure can help support the catalysts in the analyst consensus Narrative on Simply Wall St, especially the targeted IPS cost synergies and margin recovery, while investors watch leverage, input cost inflation and any integration hiccups.
What The Current Brady Forecasts Assume
Brady's current analyst narrative points to revenues of US$3.8b and earnings of US$404.8m by 2029, built on forecast revenue growth of 31.8% a year and a move from US$204.6m of earnings today to that higher 2029 consensus, which is roughly a 2x step up in profit.
Uncover why Brady's fair value indicates a 33% potential upside to its current price, which could narrow quickly if Brady executes on the IPS plan.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span roughly US$75 to about US$228, so some retail investors see Brady as heavily undervalued while others set a much higher bar. You are weighing that spread against IPS integration risk, input cost pressure and a larger debt load, which can all shift future return potential.
Explore 3 other Brady fair value estimates, including one that suggests up to 176% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Brady research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Brady. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Brady's overall financial health at a glance.
Looking For More Investment Ideas Beyond Brady?
Once you have a view on Brady, it can help to compare it with other opportunities that share some of the qualities you care about, whether that is resilience, income or potential mispricing on fundamentals.
- If you care most about quality at a fair price, line up Brady against a wider field of potentially underpriced opportunities using 32 high quality undervalued stocks.
- For investors who prize income and want yield to do more of the work, scan through 6 dividend fortresses that may offer robust payouts with room for further research.
- If balance sheet strength is your anchor, benchmark Brady against a list of solid balance sheet and fundamentals (23 results) so you can focus on companies that start from a position of financial resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com